Galway Metals Lands Funding and Cornerstone Investor as Clarence Stream Nears PEA


Michael Gentile leads $14M Galway Metals raise as Clarence Stream's 2.7Moz gold resource, antimony upside and C$120/m drilling head into a Q1 2027 PEA.
- Michael Gentile led Galway Metals' C$14 million flow-through financing and now holds approximately 10.94% of the company, subject to a 12-month lock-up.
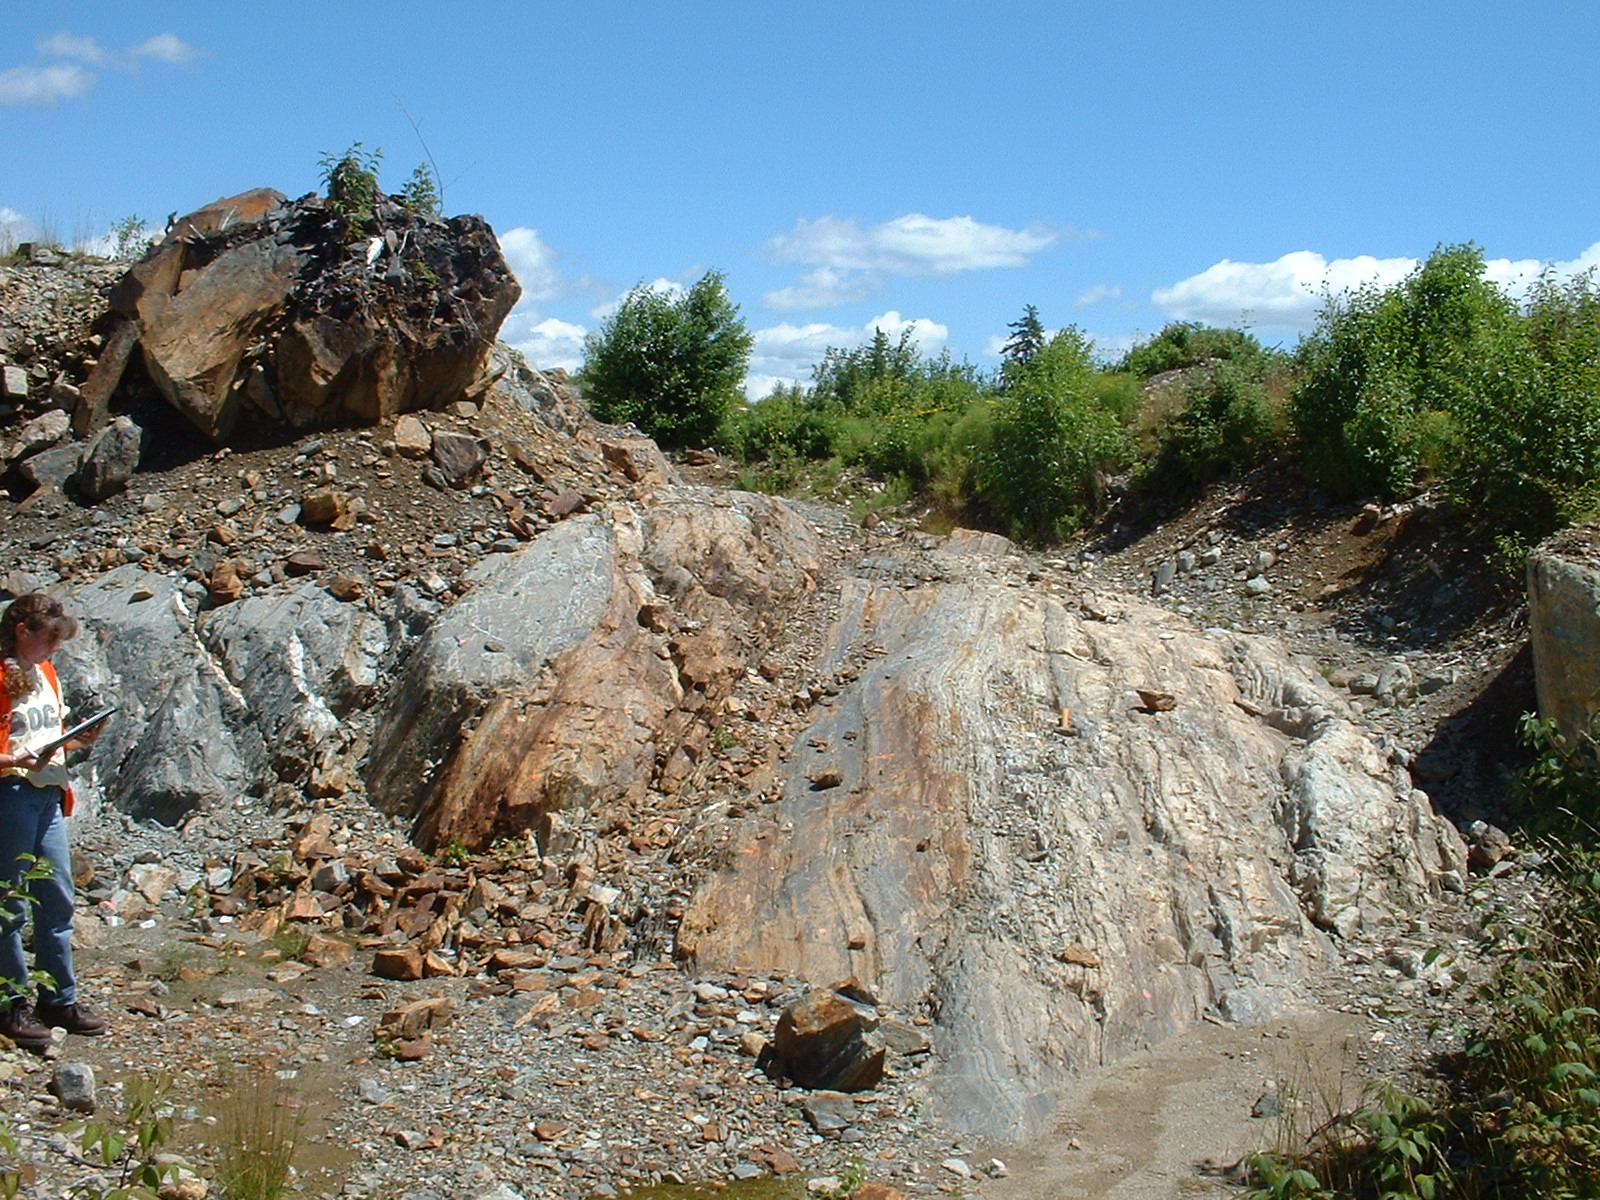
- Clarence Stream hosts roughly 2.7 million ounces of gold, with higher-grade North and South deposits positioned to supply early production.
- Recent Southwest Deposit drilling, including 2.8 g/T gold over 48.0 metres in BL-332, points to high-grade shoots outside the current resource model.
- All-in drilling costs of about C$120 per metre and established road, port and power infrastructure could accelerate resource growth at lower cost.
- A BBA-led PEA due in Q1 2027 is the key catalyst, while antimony recoveries, warrant dilution and Inferred ounces remain the main risks.
Galway Metals Inc. (TSXV:GWM, OTCQB:GAYMF) has gained a cornerstone shareholder at a pivotal stage for its Clarence Stream gold project in southwest New Brunswick. In an interview at the London Mining Forum, President and CEO Robert Hinchcliffe and Strategic mining investor Michael Gentile argued that the market still views Clarence Stream as a lower-grade, high-strip-ratio open pit. In his view, the project is now closer to the opposite.
A preliminary economic assessment (PEA) covering all three Clarence Stream deposits is expected in the first quarter of 2027, and the company plans around 70,000 metres of drilling next year. For investors, the central questions are whether grade, antimony content and infrastructure can translate into strong first-pass economics, and whether unusually cheap drilling can keep adding ounces at pace.
Aligned Management Team with Cornerstone Investor
Gentile led a $14 million brokered flow-through financing that closed on 14 October 2026, leaving him with approximately 10.94% of the company. The financing comprised 19,437,000 flow-through units priced at $0.72. Gentile acquired 17,150,000 of those units and held no Galway securities beforehand. Assuming exercise of his warrants, his stake would rise to approximately 19.72%. He has also agreed to a 12-month lock-up on the securities purchased. Closing of the Offering is still subject to the final acceptance of the TSX Venture Exchange.
Gentile said he first reviewed Galway three to four years ago and concluded the asset was not yet ready. His approach is to hold positions for three to 10 years in projects with the attributes to become producing mines. On a second look, he found that infill drilling had raised the ounce count, improved grade and cut the strip ratio from around 10 or 11 to one down to five or six to one. He also highlighted Hinchcliffe's consistent open-market share buying over the past five years as a sign of alignment.
Hinchcliffe brings around 30 years in mining. His previous company, Galway Resources, was built in Colombia and sold for US$340 million. Project manager Jesse Fisher has been with Galway for more than six years. Senior advisers include Phillip Walford, former CEO of Marathon Gold, and Allan Moran, a senior geologist with three decades at SRK.
Clarence Stream: Grade, Scale & Antimony Kicker
Clarence Stream hosts 1.42 million ounces of gold in the Indicated category at 1.62 g/t and a further 1.29 million ounces Inferred at 1.40 g/t. The estimate was prepared by SLR Consulting with an effective date of 29 May 2026. That totals roughly 2.7 million ounces across three deposits: North, South and Southwest. The district has an exploration strike length of approximately 65 kilometres. Hinchcliffe said Galway acquired the project for $3.25 million, payable over three years.
Hinchcliffe highlights the as central to the development case,
"The north and south deposits are where the antimony is and there's where also where you can get some of the higher grade ounces. One of the big benefits of this project is to be able to get the higher grade ounces in production in the early years."
Gentile's team includes a trained metallurgist and mine builder, who also invested in the financing. Gentile said he modelled the project assuming no antimony credit at all. His priority was confirming that antimony would not behave as a deleterious element that hurts recoveries. He now expects it to be a net positive. He pointed to starter pits of roughly one million ounces at around 2 g/t gold, with antimony as an additional source of value in the first five to six years.
Interview with Michael Gentile, Strategic Investor, & Robert Hinchcliffe, CEO of Galway Metals
Drilling Points to High-Grade Shoots at Depth
Recent drilling at the Southwest Deposit tested a gap in the resource model along an interpreted southwest-plunging trend. Hole BL-332 returned 2.8 g/t gold over 48.0 metres, including 16.7 g/t over 5.0 metres. Separate intervals in the same hole returned 3.9 g/t over 30.0 metres and 4.5 g/t over 13.0 metres.
Results intersected mineralisation outside current resource wireframes. The company says the results support its interpretation of repeated high-grade shoots that could be followed with deeper drilling. Hinchcliffe said Galway has issued four or five drill-result releases since the updated resource, with long intercepts grading 2-4 g/t. Gentile described the Southwest Deposit as the source of the project's bulk ounces, adding that it continues to grow with each hole.
Low Drill Costs & Established Infrastructure
Gentile said Clarence Stream has the lowest drilling cost he has seen, at about C$120 per metre all-in. He attributed this to shallow holes, competent rock, strong productivity and a local workforce keen to work close to home. On his estimate, the $14 million raised could fund up to around 100,000 metres of drilling. Hinchcliffe's stated plan for next year is around 70,000 metres.
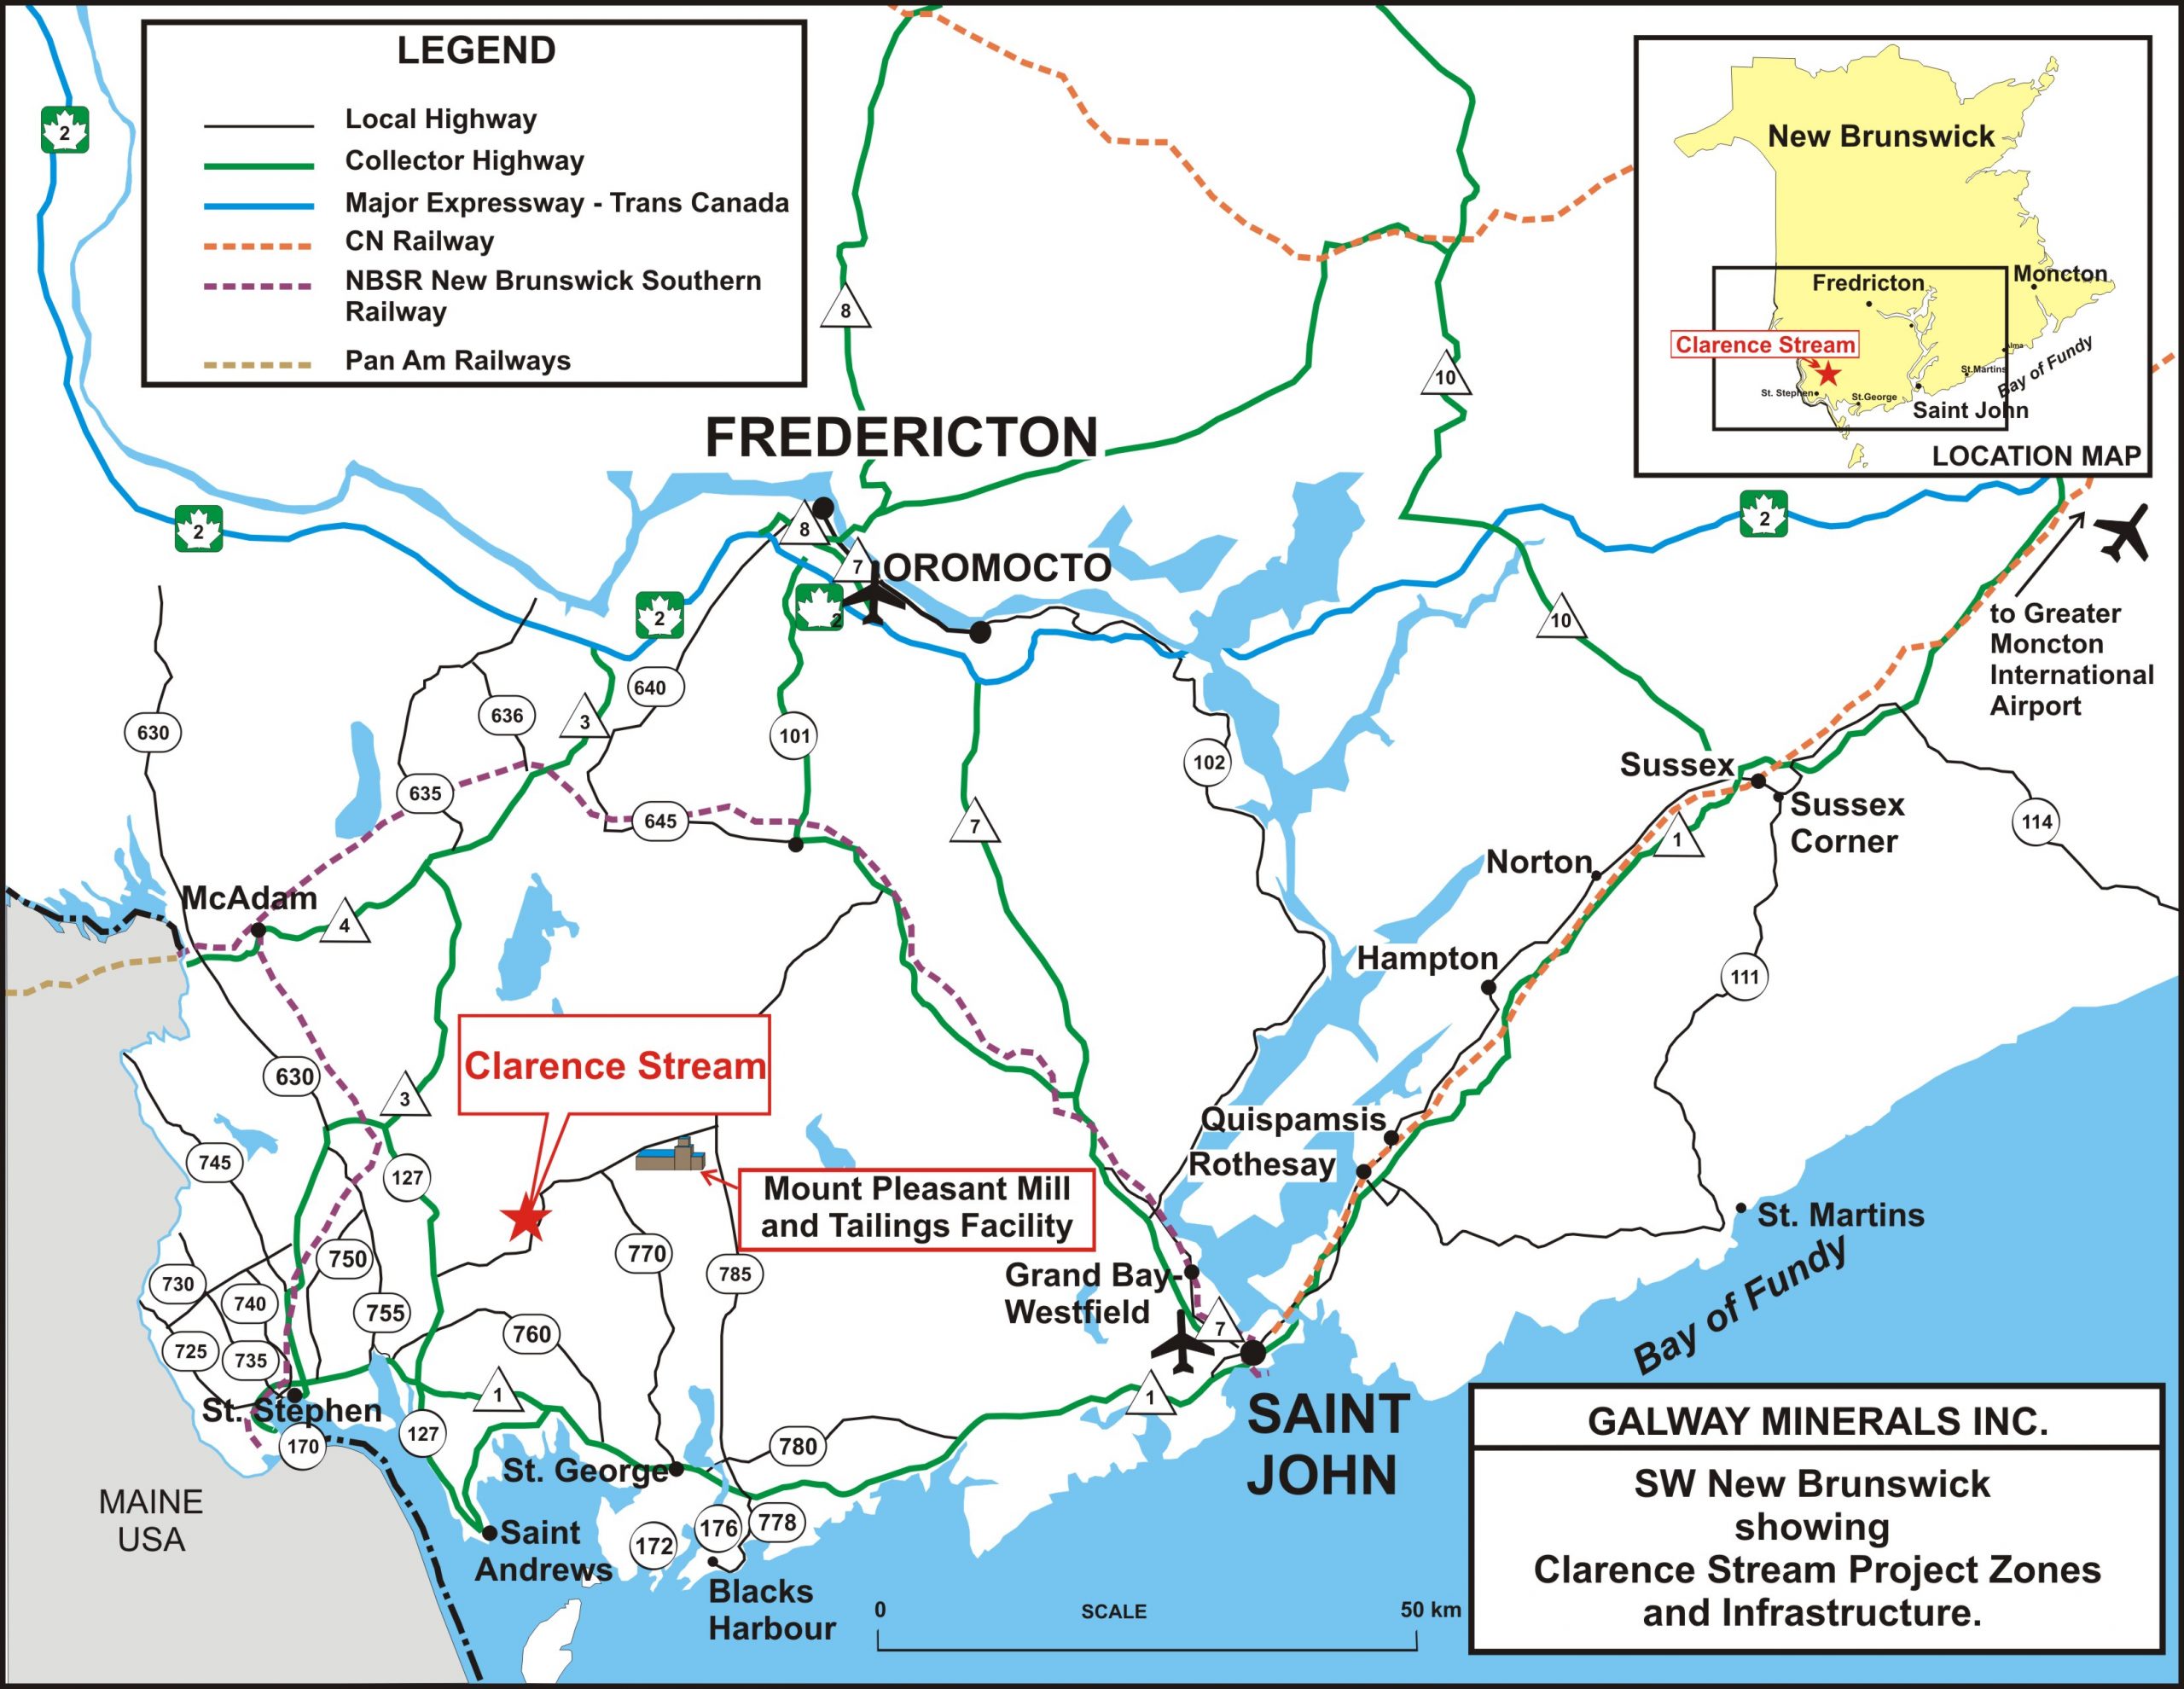
Infrastructure is the other pillar of the case. Gentile noted highways running through the project area, a deep-water port, power and a town 45 minutes away. Hinchcliffe said drill permits in New Brunswick are approved in under three weeks, which he described as the fastest turnaround in Canada. He also pointed to rising mining activity across the province. This includes the selection of a subsidiary of Agnico Eagle to negotiate an exploration agreement for the former Lake George antimony mine. Hinchcliffe added that the land package Galway assembled in 2014 and 2015 captures the most prospective gold ground in the southern half of the province.
Catalysts: The PEA and an Expanded Drill Programme
The PEA is being prepared by BBA and will cover the North, South and Southwest deposits. Hinchcliffe described it as the first pass at the project's basic economics, setting out the capital needed for production and the expected returns. Metallurgical work continues in parallel, with around 50 samples sent for testing roughly a month before the interview.
Drilling intensity will rise sharply once the new capital is deployed.
"We're going to be super aggressive and 70,000m or so of drilling. So, the news flow is going to be robust beyond robust."
Gentile outlined the path he expects from here. Once the PEA is published, the company would infill drill aggressively towards a pre-feasibility study (PFS) or feasibility study (FS) while testing how large the system can become. At C$120 per metre, he argued, infill drilling that is usually expensive at that stage becomes far more affordable.
Investment Thesis for Galway Metals
- Gentile's lead role in the $14 million financing and his 12-month lock-up give Galway a well-funded, long-horizon cornerstone shareholder ahead of its first Clarence Stream economic study.
- A resource of roughly 2.7 million ounces, with higher-grade North and South deposits suited to early production, underpins the development case.
- Drill costs of about C$120 per metre could allow the company to add and upgrade ounces faster and more cheaply than many peers.
- Road, port, power and a nearby town reduce the capital burden that typically weighs on remote Canadian projects.
- Antimony could add value, but recoveries are not yet confirmed and Gentile's own analysis assumes no credit for it.
- Investors should monitor the Q1 2027 PEA, metallurgical results and follow-up drilling on the southwest-plunging shoots as the next re-rating catalysts.
- Warrant dilution and the February 2027 expiry of the hold period are supply factors worth tracking.
Macro Thematic Analysis
Gentile's broader argument is that Canada is entering a period of renewed investor attention for mine development. He pointed to measures introduced under Prime Minister Mark Carney, which he described as tax incentives worth around 20% on large new capital projects, combined with efforts to shorten timelines to production. In his view, these policies make Canadian development assets more valuable to potential acquirers.
He also tied the theme to how major producers allocate capital.
"I think there's going to be a thematic push towards Canada the next couple of years ahead and not all Canada is created equal. Major mining companies can only build one or two projects at a time. Not all of Canada is going to get acquired."
Gentile contrasted projects in remote northern Ontario or Québec, hundreds of kilometres from roads and power, with deposits sitting on existing infrastructure. He estimated that the difference can amount to billions of dollars in savings. Clarence Stream falls into the second group.
Geology is also shifting perceptions. Hinchcliffe said that when Galway entered the area in 2015, many believed multi-million-ounce deposits were unlikely in eastern Canada and the eastern United States. The Appalachian trend, which runs from the Carolinas along the east coast into Atlantic Canada and Europe, has since produced a series of significant deposits.
Valuation is where Gentile sees the opportunity. He said Galway trades at C$30 to C$40 per ounce in the ground, against a gold price he put at US$4,000 per ounce. For a project in a supportive jurisdiction with established infrastructure, he argued, that gap is unlikely to persist once the PEA gives the market its first full economic picture.
TL;DR
Michael Gentile led Galway Metals' $14 million flow-through financing, taking a 10.94% stake with a 12-month lock-up. The funding backs aggressive drilling at Clarence Stream in New Brunswick, which hosts roughly 2.7 million ounces of gold across three deposits. Higher-grade North and South deposits could feed early production, with antimony as potential upside that Gentile excluded from his own modelling. Recent Southwest Deposit holes, including 2.8 g/t gold over 48.0 metres pointing to high-grade shoots at depth. Drilling costs of about C$120 per metre and established road, port and power infrastructure support the case. A BBA-led PEA covering all three deposits is due in Q1 2027.
FAQs (AI Generated)
Analyst's Notes





Subscribe to Our Channel

Stay Informed