Integra Has Funded DeLamar's Early Works; 2 Events in 2027 Test the Re-Rating


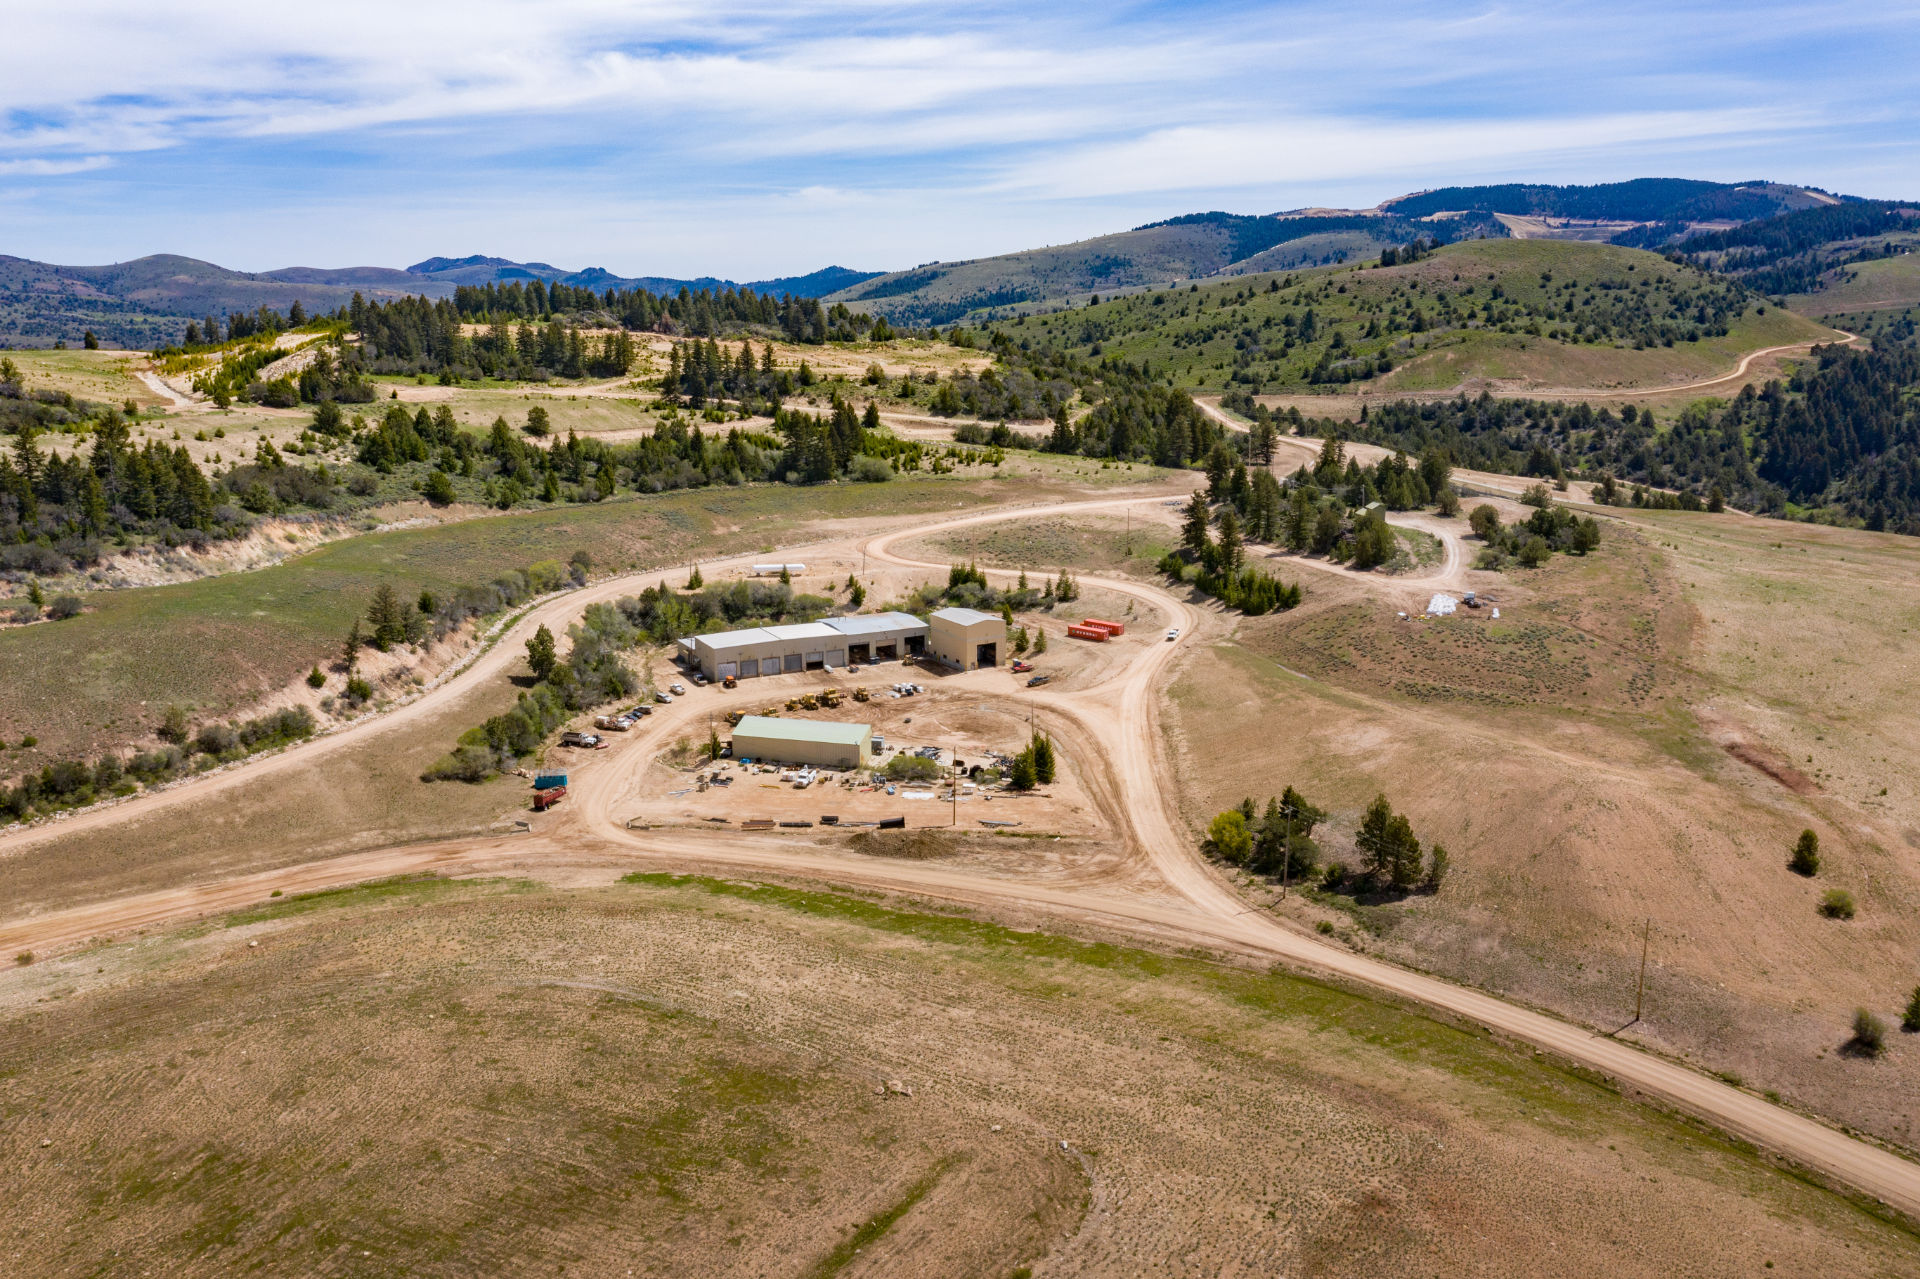
Integra Resources raised US$61 million for DeLamar early works and procurement; Florida Canyon costs and a targeted 2027 Record of Decision shape valuation.
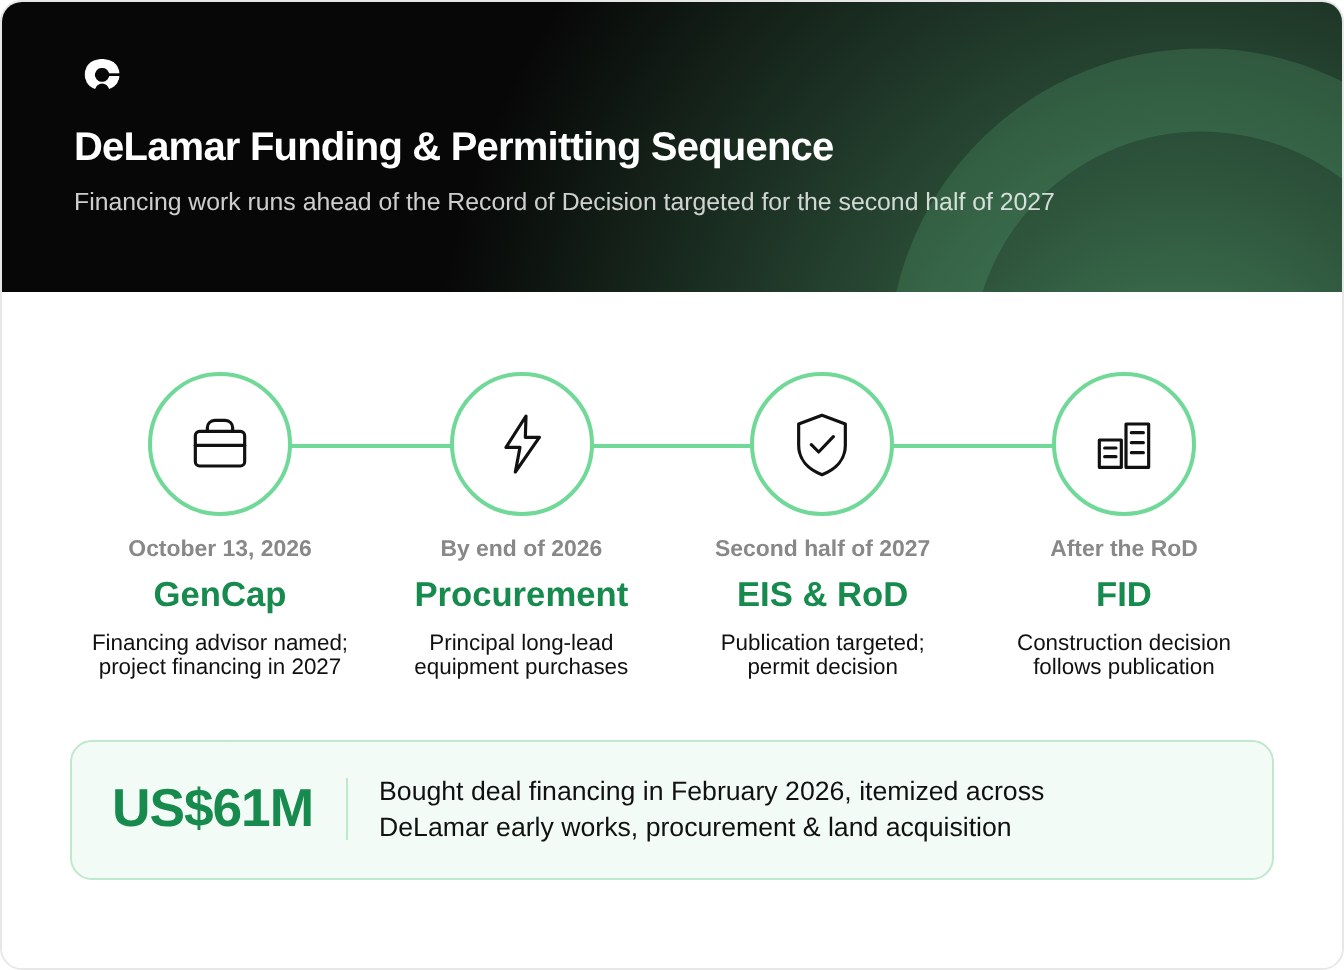
- Integra Resources closed a US$61 million bought deal financing in February 2026, with proceeds itemized across DeLamar early works, procurement and land acquisition for 2026 and 2027.
- Cash totaled approximately US$111 million at June 30, 2026, against 202.9 million basic shares and 216.7 million fully diluted shares.
- DeLamar's feasibility study shows initial capital of about US$389 million, project financing is planned for 2027, and GenCap Mining Advisory has been appointed to evaluate and structure the financing alternatives.
- Florida Canyon's 2026 investment of US$75 million includes a heap leach pad expansion pulled forward from 2027, ahead of a targeted run rate of 80,000 to 85,000 ounces of gold per year.
- Integra is targeting publication of the Environmental Impact Statement and Record of Decision for DeLamar in the second half of 2027, with a final investment decision to follow.
Capital Structure Ahead of a Construction Decision
Integra Resources (TSXV: ITR | NYSE American: ITRG) held approximately US$111 million in cash at June 30, 2026, with 202.9 million basic shares outstanding and 216.7 million on a fully diluted basis. The balance sits against 2 capital demands of very different sizes. The first is pre-construction work at the DeLamar gold-silver project in Idaho. The second is the build itself, which the feasibility study (FS) prices at about US$389 million of initial capital, including US$42 million for owners' costs and bonding cash collateral.
The February 2026 bought deal financing of US$61 million addressed the first demand, with approximately US$16.0 million for 2026 early works, US$12.0 million for 2026 procurement, US$12.5 million for land acquisition, US$4.5 million for 2027 early works and US$12.5 million for 2027 procurement. Management says cash flow from Florida Canyon is stabilizing and that the treasury is still building while funding the investments at both Florida Canyon and DeLamar. For the build, Integra announced the appointment of GenCap Mining Advisory on October 13, 2026, to evaluate and structure financing alternatives, and plans to secure project financing in 2027.
First Event: Florida Canyon's 2027 Production & Cost Test
Florida Canyon in Nevada, acquired for US$68 million in 2024, supplies the cash flow. The first 2 quarters of 2026 came in below quarterly production guidance, and management says haulage, the movement of ore from the open pits to the crusher or directly to the leach pad, was roughly 9/10ths of the problem and is resolved, as are the heap leach pad circulation issues from blending fine low-grade stockpile material. The site has reported record ounces stacked, record ore movement and record waste ripping, and 2026 guidance of 70,000 to 75,000 ounces of gold, cash costs of US$2,300 to US$2,500 per ounce sold and mine-site all-in sustaining costs (AISC) of US$3,300 to US$3,500 per ounce sold remain in place.
Management puts 2026 investment at the site at US$75 million, to be completed by year-end, and the largest remaining item is the heap leach pad expansion. It adds to 2026 AISC, and management is targeting being past that spending in the first quarter of 2027.
President and Chief Executive Officer of Integra, George Salamis, described why the expansion moved into 2026:
"We're moving the record amounts of tons to the existing heap leach pad. We need to expand far quicker than we thought. Brand new capacity, which we're doing at the end of this year. That was supposed to be a next year piece."
The 2027 case rests on ore quality. The central orebodies scheduled for 2027 carry almost twice the grade of the material now being processed, with better leach kinetics and less fine material, and management is targeting a run rate of 80,000 to 85,000 ounces of gold per year. The updated technical report delivered in June 2026 shows life-of-mine (LOM) average production of 82,000 ounces, LOM mine-site AISC of US$2,331 per ounce, a mine life to 2033 plus 2 years of residual leaching, and an after-tax net present value at a 5% discount rate (NPV5%) of US$601 million under the base case gold price deck and US$723 million at a US$4,200 per ounce spot assumption.
Second Event: DeLamar's Record of Decision
DeLamar entered the FAST-41 Transparency Projects Program in January 2026, and posted the scoping report on September 21, 2026. The Environmental Impact Statement (EIS) comes next, and Integra is targeting publication of the EIS and the Record of Decision (RoD) in the second half of 2027, with a final investment decision (FID) to follow. Salamis says community support for DeLamar is overwhelming, state-level permits for water use, sanitation, and air quality are gaining pace, and the RoD will answer many of the remaining questions.
DeLamar's FS, with an effective date of December 8, 2025, shows 119,000 gold-equivalent ounces per year in years 1 to 5 and 106,000 on a LOM average, over a 10-year mine life, at LOM AISC of US$1,480 per gold-equivalent ounce. At US$3,000 per ounce gold and US$35 per ounce silver, the after-tax NPV5% is US$774 million, the after-tax internal rate of return (IRR) is 46%, and payback is 1.8 years. At US$4,500 per ounce gold and US$65 per ounce silver, the FS's current-price case lifts those figures to an NPV5% of US$1.9 billion, an IRR of 97% and a payback of 1.0 year.
Work ahead of the RoD is already in motion. Integra is targeting its principal long-lead purchases by the end of 2026, covering the Merrill-Crowe plant, the crushing plant and electrical equipment, and the crushing pilot plant mobilized in July 2026 has processed about 39,000 tons of backfill material. Ausenco was appointed lead engineering partner in June 2026, and an existing agreement with Idaho Power Company covers certain long-lead equipment related to the renewal of Idaho Power's plant and equipment, with a subsequent agreement targeted by the end of 2026.
Valuation: What the Discount Waits On
Management considers the current valuation unfair and ties it to 2 outcomes still ahead: Florida Canyon's 2027 production and cost results and the DeLamar permit. For Florida Canyon, the test is whether 2027 production reaches 80,000 to 85,000 ounces of gold per year at costs materially below US$3,000 per ounce. For DeLamar, the test is the RoD.
Nevada North is Integra's third asset. Its 2023 preliminary economic assessment (PEA) shows a 13-year mine life, about 1 million gold-equivalent ounces in total, an average of about 80,000 gold-equivalent ounces per year, LOM AISC of US$973 per ounce on a co-product basis, an after-tax NPV5% of US$310 million at US$1,700 per ounce gold, an IRR of 37% and a payback of 3 years. Management is updating the PEA with new capital costs, operating costs, and gold prices, and the longer Florida Canyon mine life changes the staffing plan.
Salamis said the longer runway at Florida Canyon means Nevada North would need its own team:
"Now that Florida Canyon, and this is a good problem to have, has a much longer runway in terms of mine life, those 2 operations will be running in parallel. So they'll need their own equipment. They'll need their own staff."
Both events are targeted for 2027, as is the DeLamar project financing, so evidence on cost, permits, and financing terms arrives close together.
The Investment Thesis for Integra Resources
- DeLamar early works, procurement, and land acquisition through 2027 are funded by the February 2026 raise, leaving the build's initial capital of about US$389 million to be financed.
- GenCap Mining Advisory is evaluating financing alternatives ahead of project financing planned for 2027, the year the Environmental Impact Statement and Record of Decision are targeted.
- Florida Canyon's 2027 results will show how far costs move from 2026 mine-site all-in sustaining cost guidance of US$3,300 to US$3,500 per ounce toward the US$2,331 life-of-mine figure.
- DeLamar's after-tax net present value at a 5% discount rate rises from US$774 million at US$3,000 per ounce of gold to US$1.9 billion at US$4,500 per ounce of gold.
- Management ties the valuation discount to Florida Canyon reaching 80,000 to 85,000 ounces of gold per year at costs materially below US$3,000 per ounce and to the DeLamar permit.
- Nevada North's 2023 preliminary economic assessment, which used US$1,700 per ounce of gold, is being updated with new capital costs, operating costs, and gold prices.
The pre-construction budget at DeLamar is funded, leaving Florida Canyon's 2027 production and cost results, the permit decision, and build financing as the items to watch, all targeted for 2027. Each has a stated figure or timeline to measure against, and management ties the valuation discount to the first 2.
TL;DR
Integra raised US$61 million in February 2026 for DeLamar early works, procurement and land acquisition, held approximately US$111 million in cash at June 30, 2026, and has appointed GenCap Mining Advisory ahead of 2027 project financing against US$389 million of initial capital. Florida Canyon is targeting 80,000 to 85,000 ounces of gold per year from 2027 at costs materially below US$3,000 per ounce, and the EIS and RoD are targeted for the second half of 2027, with the FID to follow.
FAQs (AI-Generated)
Analyst's Notes





Subscribe to Our Channel

Stay Informed