




Tariff Arbitrage Collapse Strands US Copper, Lifting Ex-US Pricing


A projected 104,000-tonne surplus masks tighter overseas supply, with 70% of visible copper stocks held in US warehouses, favoring LME-linked producers.
- On October 14, 2026, the International Copper Study Group (ICSG) raised its 2026 refined copper surplus forecast to 104,000 tonnes and maintained its 2027 forecast at 368,000 tonnes.
- COMEX-approved US warehouses held roughly 70% of visible global copper stocks as of October 14, 2026, after inventories rose nearly 750% since February 2025 to more than 714,000 tonnes.
- The COMEX-LME price spread narrowed to about $310 per tonne from a record above $3,000 in July 2025, removing the incentive to ship copper into the US.
- Refined copper remains untaxed under the August 5, 2025 Federal Register proclamation, which imposed a 50% tariff on semi-finished copper products and derivatives but only recommended 15% and 30% duties for January 1, 2027 and 2028, respectively.
- A Commerce decision against refined copper tariffs could reverse the COMEX-LME spread and encourage US copper exports.
US Copper Stockpiles Support Higher LME Prices Despite Surplus
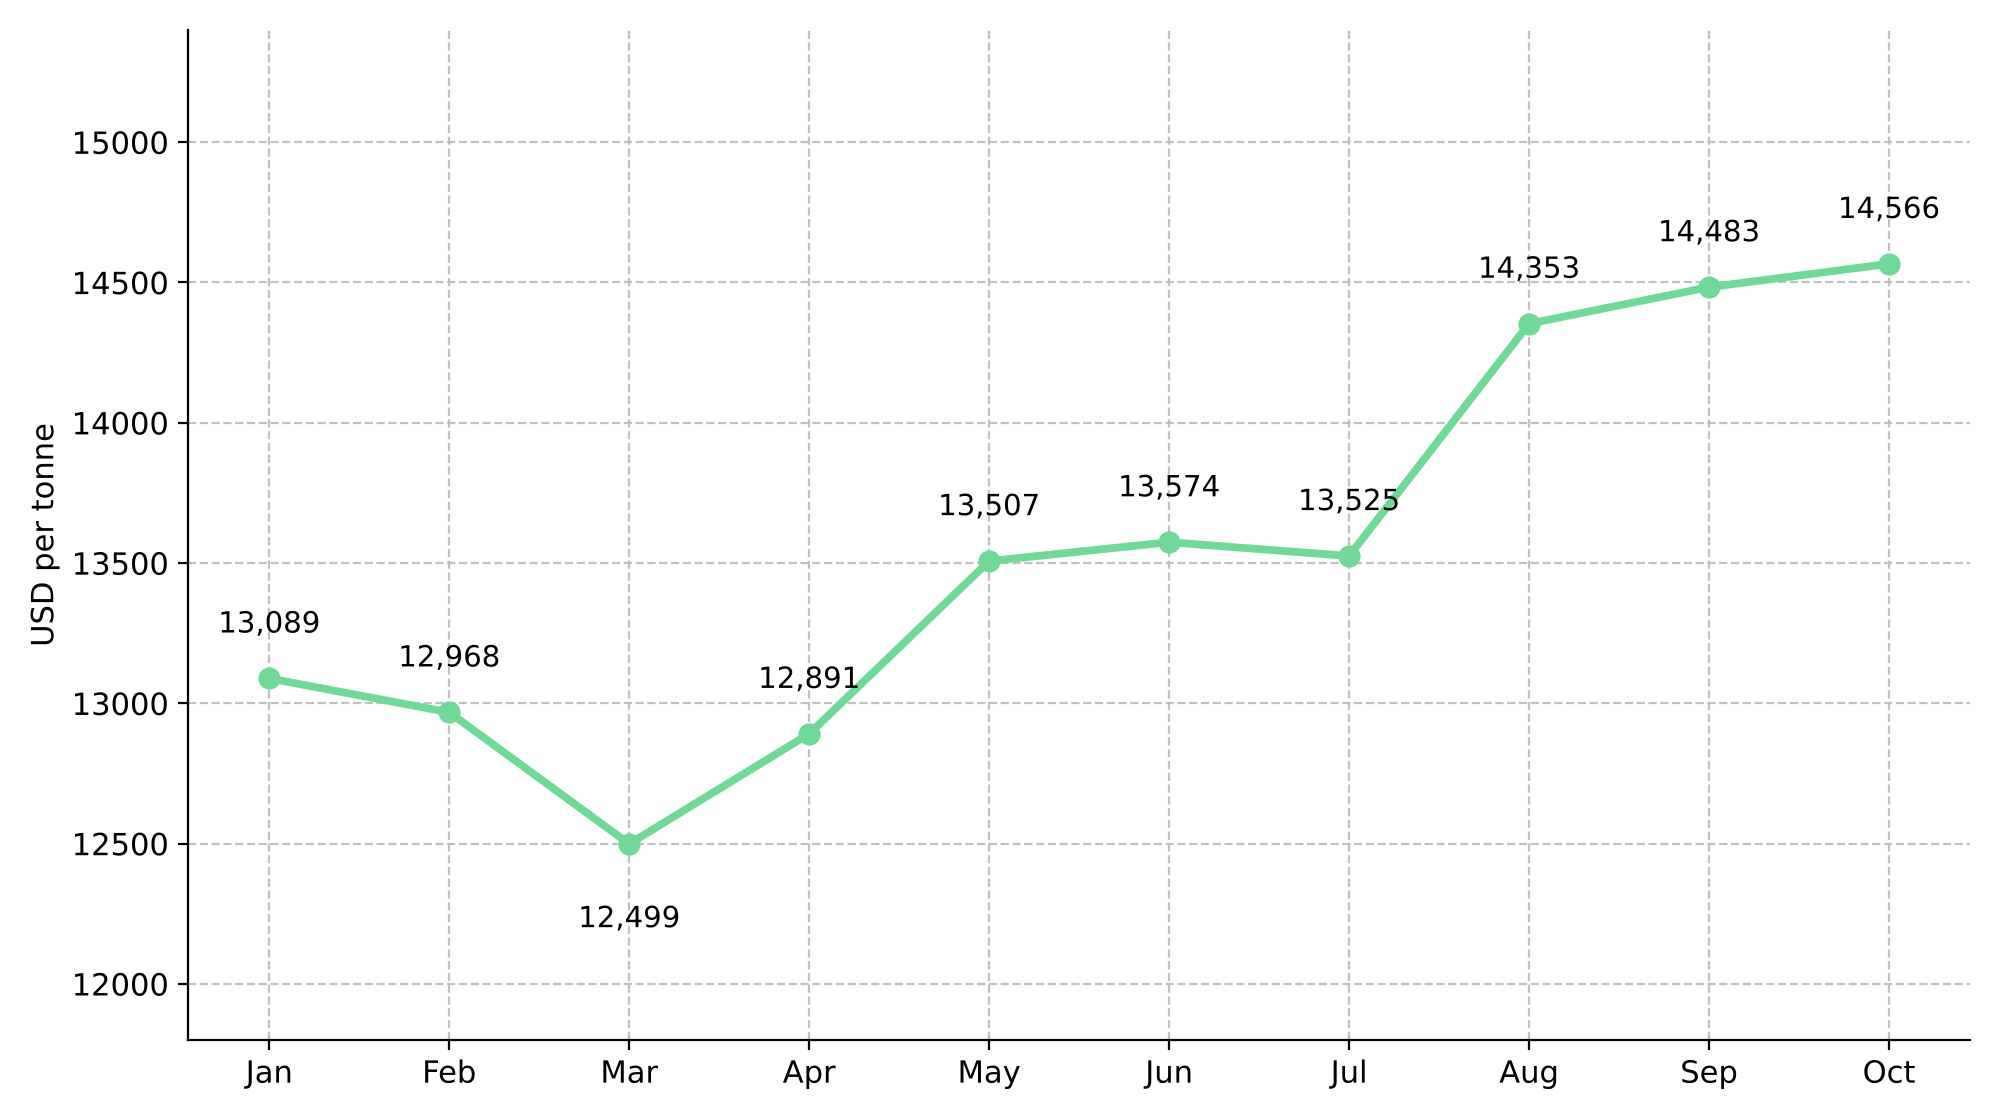
ICSG raised its 2026 refined copper surplus forecast to 104,000 tonnes and maintained its 2027 forecast at 368,000 tonnes. The COMEX-LME price spread narrowed from over $3,000 per tonne in July 2025 to about $310, reducing incentives to ship copper into the US. Despite projected surpluses, LME cash copper averaged $14,566 per tonne in October to date, up from $13,089 in January.
Copper prices have risen despite a forecast surplus as inventories remain concentrated in the US. COMEX-approved US warehouses hold roughly 70% of visible global copper stocks after inventories rose nearly 750% since February 2025 to more than 714,000 tonnes, limiting supply elsewhere and supporting higher ex-US prices.
Tariff Fears Build 1.6M-Tonne US Copper Inventory
President Trump's February 2025 Section 232 investigation triggered US copper inflows, with imports rising 80% to over 1.62 million tonnes in 2025 against domestic production of 1 million tonnes. Macquarie estimates total US copper stocks at about 1.6 million tonnes, limiting supply available outside the US.
The August 2025 proclamation imposed a 50% tariff on semi-finished copper products and derivatives but exempted refined cathode. It required a Commerce report by June 30, 2026, yet no decision has been published on the proposed 15% and 30% refined copper tariffs.
COMEX Premium Restrains Copper Exports Despite Slower Imports
Charles Cooper, Analyst at Wood Mackenzie, said the collapsed COMEX-LME price spread has weakened incentives to ship copper into the US. However, about 100,000 tonnes booked earlier are still due to arrive through October. Exports require LME and Shanghai prices to rise well above COMEX, allowing producers outside the US to benefit from tighter supply and higher prices in those markets.
Tight Ex-US Supply Supports LME-Linked Producer Revenues
Tariff concerns raised COMEX-linked copper costs for US fabricators, with prices reaching a record $15,057 per tonne. Meanwhile, producers selling at LME and Shanghai prices benefit from tighter ex-US supply, with LME inventories at 229,650 tonnes.
COMEX or LME pricing affects producer revenue, but output and costs also matter. Antofagasta guided 2027 production to 630,000 to 690,000 tonnes, below its initial 2026 guidance of 650,000 to 700,000 tonnes, while raising cash cost guidance to $2.60 to $2.70 per pound. Shares fell 6.5%, highlighting how lower output and higher costs can offset stronger copper prices.
No refined copper tariff decision has followed the June 30 Commerce reporting deadline. Macquarie considers continued inaction the most likely outcome, exposing positions tied to a January decision to potential losses. Tight ex-US copper supply offers an investment opportunity less dependent on tariff timing.
Who Benefits If Copper Turns Deficit
US copper stockpiles grew over fears of a refined copper tariff that was never imposed. COMEX prices remain above LME prices, discouraging exports and keeping supply tighter outside the US regardless of the pending tariff decision.
Roughly 1.6 million tonnes of copper held in the US limits supply available to overseas buyers, supporting LME-linked revenues for producers outside the US. If the market shifts into deficit, concentrated US stocks could leave overseas buyers with less available copper than the global surplus suggests.
Analyst's Notes





Subscribe to Our Channel


Stay Informed


