

Discovery Mining
NYSE: CLOSED
TSE: CLOSED
LSE: CLOSED
HKE: CLOSED
NSE: CLOSED
BM&F: CLOSED
ASX: CLOSED
FWB: CLOSED
MOEX: CLOSED
JSE: CLOSED
DIFX: CLOSED
SSE: CLOSED
NZSX: CLOSED
TSX: CLOSED
SGX: CLOSED
NYSE: CLOSED
TSE: CLOSED
LSE: CLOSED
HKE: CLOSED
NSE: CLOSED
BM&F: CLOSED
ASX: CLOSED
FWB: CLOSED
MOEX: CLOSED
JSE: CLOSED
DIFX: CLOSED
SSE: CLOSED
NZSX: CLOSED
TSX: CLOSED
SGX: CLOSED

By Metal or Resource

By Project Stage
By Exchange
By Geography
By Investment Theme
Americas Gold & Silver Corporation

Crux Investor Index
9
–
Market Cap (USD)
1258647000
Symbol
TSX:USA
Stage of development
Production
Primary COMMODITY
Silver
Additional commodities
Gold
Antimony
Company Overview
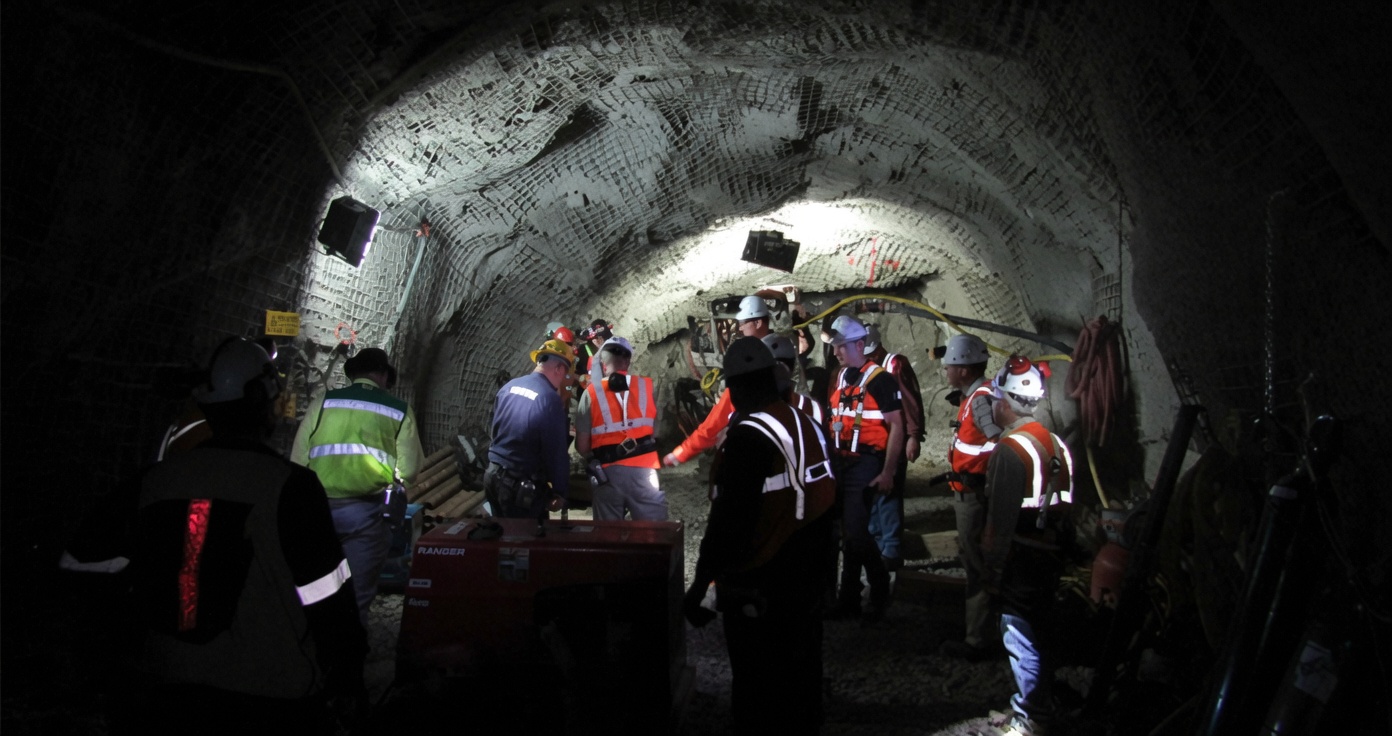
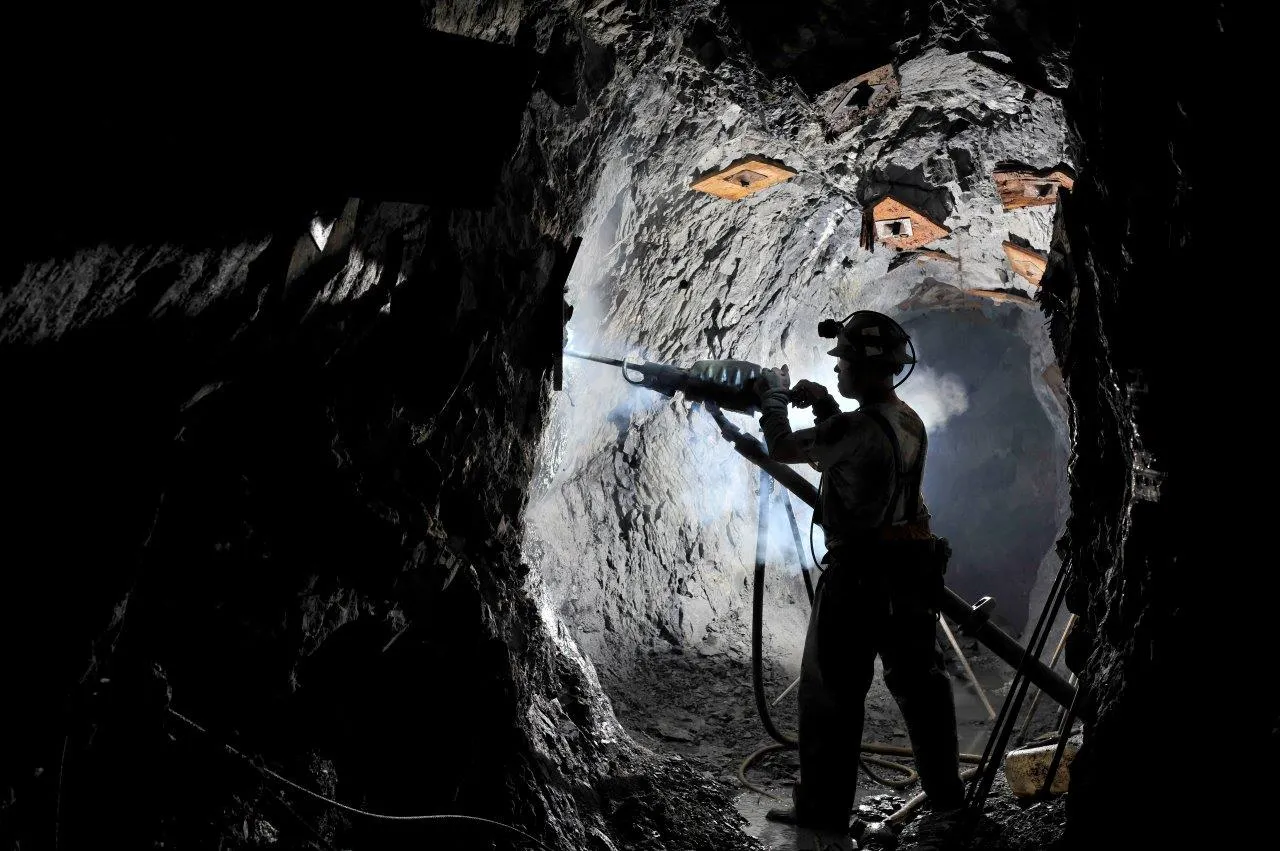
Americas Gold and Silver Corporation (TSX: USA | NYSE American: USAS) is a North American producer of silver and other critical minerals supporting artificial intelligence, electrification, national security, and advanced manufacturing. Its flagship, 100%-owned Galena Complex sits in Idaho's Silver Valley, one of the premier silver mining districts in the US, and includes the largest antimony mine in the US. The nearby Crescent Silver Mine is fully permitted, and the company also owns and operates the Cosalá Operations in Sinaloa, Mexico, where the EC120 high-grade silver-copper mine is being scaled. Approximately 90% of revenue came from silver as of the first half of 2026.
The stated strategy is to become one of North America's leading silver producers while establishing a secure domestic supply of antimony, through a 51/49 joint venture with US Antimony to build a fully integrated supply chain from mine to finished product. Americas produced a record 800,458 ounces of silver in the third quarter of 2026 and remains on track for 2026 guidance of 3.2 million to 3.6 million ounces. It was named to the 2026 TSX30, the Toronto Stock Exchange's ranking of the 30 top-performing companies by dividend-adjusted share price over 3 years, in which its share price increased by 477%. Between 2025 and the first quarter of 2026, the stock was included in the VanEck Junior Gold Miners exchange-traded fund and the SIL exchange-traded fund.
Eric Sprott is the largest shareholder at approximately 14%, and the company reports that about 60% of shares are held by management, institutions, and insiders. As at May 28, 2026, Americas had 338 million common shares outstanding and 362 million fully diluted shares, and 8 analysts covered the stock with price targets from C$8.50 to C$15.00. Market capitalization was approximately US$1.7 billion as of August 7, 2026, and unaudited cash stood at US$63 million as of September 30, 2026.
Opportunity
The investment case rests on high-grade, primary silver in a district with existing infrastructure. Galena's 2025 average silver head grade of 473 grams per tonne (g/t) ranks second among 5 high-grade silver mines, behind Keno Hill at 994 g/t. As at October 31, 2025, consolidated Proven and Probable silver reserves total 26 million ounces, Measured and Indicated resources total 116 million ounces at 240 g/t, and Inferred resources total 133 million ounces at 264 g/t. At the Galena Complex alone, Measured and Indicated resources total 87.9 million ounces at 501 g/t and Inferred resources total 105.7 million ounces at 498 g/t.
Reserves were estimated at US$34.00 per ounce of silver and US$4.25 per pound of copper, well below third-quarter realized prices of US$60.54 per ounce and US$6.41 per pound. Antimony adds a second critical mineral stream: Galena produced approximately 561,000 pounds in 2025 and more than 20 million pounds since 2001, and metallurgical testwork achieved 99%+ antimony extraction from copper concentrate, while historical Galena production has averaged approximately 0.7 pounds of antimony per pound of copper. In the third quarter, Galena produced 101,011 pounds of antimony and sold 121,691 pounds at a realized price of US$8.79 per pound.
Much of the near-term opportunity sits outside the current resource. The 2026 program of approximately 64,000 meters across Idaho and Mexico is the largest in company history, and the September drill results were not included in the 2025 Mineral Resource and Reserve statement. At Galena, a new vein on the 49 level returned 1.3 meters at 1,062 g/t silver and 0.7% copper; the 9 Vein returned 0.4 meters at 7,123 g/t silver, 3.24% copper, and 1.81% antimony in an area without vein projections; and the 520 Vein at Coeur now measures 200 meters along strike and 200 meters in vertical extent. At Cosalá, drilling returned 20.5 meters at 654.7 g/t silver and 1.5% copper, about 30 meters outside the 2025 inferred resource boundary, and Crescent drilling returned 1.3 meters at 1,891 g/t silver and 0.3% copper.
Management
Chairman and Chief Executive Officer Paul Andre Huet has more than 35 years of leadership experience, including as Chair and Chief Executive Officer of Karora Resources, which merged with Westgold, and as Chief Executive Officer of Klondex Mines, which was acquired by Hecla Mining. Chief Operating Officer Mike Doolin has more than 35 years of operations experience, increased throughput at Karora from 340,000 to 1.6 million tons per year, and previously served as Chief Operating Officer of Klondex Mines.
Chief Financial Officer Warren Varga has more than 25 years in finance, was Chief Financial Officer of US Silver & Gold, and held senior corporate development roles at Barrick Gold. Oliver Turner, Executive Vice President, Corporate Development, has more than 15 years of capital markets experience, including as Senior Vice President, Mining Equity Research at GMP Securities and as a mining engineer at Wardrop Engineering (now Tetra Tech).
The board also includes Peter Goudie, a Karora director from 2008 until its 2024 merger and a former Executive Vice President, Marketing at Inco; Bradley R. Kipp; Tara Hassan, a mining engineer and former Senior Vice President, Corporate Development at SilverCrest Metals; Meri Verli; Gordon Pridham; and Shirley In't Veld. The company points to the Klondex sale to Hecla Mining for C$740 million in 2018 and the Karora merger with Westgold as the team's track record, a mix of mine-building, operating, and capital markets experience suited to a company scaling production.
Growth Strategy
Growth centers on scaling Galena through mechanization. The company reports a 300% increase in mining productivity since 2024, from approximately 50 tons per shift in 2024 to up to approximately 200 tons per shift in 2026, with 17 long hole panels now mined to design widths. Hoisting capacity has doubled through the No. 3 Shaft upgrades, and the Coeur Shaft hoist motor has been replaced and a spare motor added for redundancy; the Galena mill is targeted to expand from approximately 750 to 1,200 short tons per day (stpd), and a paste fill plant under construction supports a targeted 70%/30% split between long hole stoping and underhand cut and fill. In the third quarter, management also added 4 grizzlies above ore shoot loading pockets, cutting the time to load one 4-ton car from 5 minutes to 20 seconds, and began the waste development needed to set up long hole stoping in the higher-grade silver-copper-antimony veins.
Crescent is the next source of mill feed. Acquired on December 12, 2025, for approximately US$65 million, consisting of US$20 million in cash and approximately 11.1 million common shares valued at US$45 million, it has the potential to add approximately 1.5 million ounces of silver per year, according to the company. Of 45 holes drilled to date, 12 have been reported, and 33 are pending, supporting ongoing mine planning and an updated Mineral Resource estimate in 2027. At Cosalá, EC120 entered commercial production at approximately 1,550 tons per day; the operation produced a record 1.2 million ounces of silver in 2025 at all-in sustaining costs (AISC) of US$26.52 per ounce, and third-quarter silver production rose 23% quarter over quarter to 415,879 ounces. The company is targeting mine development to access the Upper and Lower 120 zones in the second half of 2027, with the next resource estimate and mine plan also in 2027.
The antimony joint venture, announced on February 10, 2026, is to build an antimony processing hub at the Galena Complex, with Americas providing the Galena site and feedstock and the structure targeting downstream profits and third-party processing revenue. Further upside lies at depth: all 2026 drilling at Galena has been above the 6,000-foot level, and neighboring operating mines along strike extend deeper than 10,000 feet.
Financial Overview
Americas produced a record 800,458 ounces of silver in the third quarter of 2026, with Galena contributing 384,579 ounces and Cosalá 415,879 ounces, and sold a record 860,850 ounces. Consolidated production also included 964,551 pounds of lead, 918,456 pounds of copper and 101,011 pounds of antimony, for 936,870 silver equivalent ounces produced and 1,010,649 sold at realized prices of US$60.54 per ounce of silver, US$6.41 per pound of copper, US$0.83 per pound of lead and US$8.79 per pound of antimony. Silver production for the first 3 quarters stands at 2.3 million ounces, in line with 2026 expectations.
2026 guidance is 3.2 million to 3.6 million ounces of silver at AISC of US$30 to US$35 per ounce, approximately 30% above 2025 production of 2.65 million ounces, with total capital investment of US$90 million to US$120 million (sustaining US$30 million to US$40 million and growth US$60 million to US$80 million) and exploration of US$15 million to US$20 million. First-half AISC averaged US$36.92 per ounce, with US$34.12 in the first quarter and US$40.63 in the second quarter, above the top of guidance, and management is targeting production weighted to the second half with lower costs. Second-quarter revenue rose 71% to US$46.3 million.
Unaudited cash was US$63 million as of September 30, 2026, in line with expectations as capital is deployed into the revitalization and growth plan, down from US$88.9 million at the end of the second quarter, and available liquidity was US$113 million, including US$50 million available under the existing credit facility with SAF. The company has raised more than US$300 million through equity and debt financings in 2024 and 2025 and, through settlements with Sprott Mining Inc. (592,000 ounces of silver) and Royal Gold (8,861 ounces of gold) that closed on June 11, 2026, eliminated US$76 million of future variable obligations and more than US$28 million in annual debt service for approximately 3.3% dilution. The company cites an average price to net asset value of approximately 1.17x for intermediate to senior silver producers and shows Americas trading below that average as of August 7, 2026.
Risk Factors and Mitigation
- Commodity Price Volatility: Approximately 90% of revenue came from silver in the first half of 2026, which the company presents as leverage to the silver price, and it lists fluctuating mineral and commodity prices as a risk. Guided AISC of US$30 to US$35 per ounce compares with a third-quarter realized silver price of US$60.54 per ounce, and reserves estimated at US$34.00 per ounce provide a conservative base. The 2026 settlements removed US$76 million of metal price-linked obligations, which reduces derivative and mark-to-market volatility.
- Regulatory & Permitting Risks: The company lists uncertainty around regulatory requirements and approvals, permitting timelines, and adverse changes in trade policies among its risks, and its guidance assumes timely receipt of required permits and licenses. Crescent is described as fully permitted, and Galena and Cosalá are existing operations.
- Technical & Operational Risks: Galena had temporary production interruptions in the second quarter, first-half AISC of US$36.92 per ounce was above the top of guidance, and guidance assumes the Galena shaft repair and rehabilitation work is completed on schedule and within budget. Cosalá produced 415,879 of the 800,458 ounces of silver in the third quarter, and guidance assumes no further adverse impacts there from blockades or work stoppages. Inferred resources of 133 million ounces are well above Proven and Probable reserves of 26 million ounces, and the highest-grade Galena intercepts are narrow, such as 0.4 meters at 7,123 g/t silver. Hoisting upgrades, new grizzlies, fiber optic communications and the transition to long hole stoping are intended to remove bottlenecks and improve operating flexibility.
- Environmental & Social Risks: The company lists environmental risks, reclamation activities, labor relations, and illegal blockades among its risk factors. Its first Corporate Sustainability Report, for 2025, completed an environmental, social and governance (ESG) materiality assessment identifying 17 material factors, established a 2025 baseline for Scope 1 and 2 greenhouse gas emissions across all operating sites, and reports Health and Safety, Environment and Supplier Code of Conduct policies approved and implemented during 2026. The board oversees the program, and Galena Complex and Cosalá have recorded zero lost-time accidents since March 2025 and April 2025, respectively.
- Financing Risk: Cash fell to US$63 million on September 30, 2026, from US$88.9 million at the end of the second quarter, while 2026 guidance calls for US$90 million to US$120 million of capital investment and US$15 million to US$20 million of exploration. The company states that, should it experience negative operating cash flows in future periods, it may need to raise additional funds through the issuance of equity or debt securities, and the Sprott and Royal Gold settlements involved share issuances. Available liquidity of US$113 million, US$50 million available under the credit facility, cash generation from Cosalá, and more than US$300 million raised in 2024 and 2025 reduce reliance on new capital, and the company describes itself as fully financed for growth projects in Idaho and Mexico.
- Execution Risk: The plan depends on delivering a second-half-weighted 2026, completing the paste fill plant and the mill expansion to 1,200 stpd, completing the transition to long hole stoping, accessing the Upper and Lower 120 zones at Cosalá in the second half of 2027, and building the antimony processing hub with US Antimony. At the time of the Crescent acquisition, the company expected it to supplement Galena mill feed as early as mid-2026, while the latest drilling results are described as supporting ongoing mine planning and an updated Mineral Resource estimate in 2027. Management's record at Klondex and Karora, and the hoisting and equipment upgrades already completed, reduce but do not eliminate the risk of delays and cost overruns.
Conclusion
Americas Gold & Silver offers exposure to high-grade silver and the largest antimony mine in the US, with operations at Galena and Cosalá that produced a record 800,458 ounces of silver in the third quarter, the fully permitted Crescent mine next door, and drilling at Galena, Crescent and Cosalá that is regularly returning grades above the current resource model. Management attributes the acceleration of its Galena optimization work to the strong cash generation of Cosalá.
The main uncertainties are whether fourth-quarter production delivers on the second-half weighting of guidance, whether costs return to US$30 to US$35 per ounce after first-half AISC of US$36.92 per ounce, and whether the Galena infrastructure projects deliver the capacity long-hole stoping requires. With the stock trading below the approximately 1.17x price-to-net-asset-value average of intermediate to senior silver producers as of August 7, 2026, fourth-quarter production against guidance, development of the Upper and Lower 120 zones at Cosalá in the second half of 2027, and the Crescent and Cosalá resource estimates, both targeted for 2027, are the milestones for investors to track.
Article
Americas Gold & Silver Corporation Analyst Notes

Company Resources
Submitted by or sourced from
Americas Gold & Silver Corporation
Charts
Similar Companies
Stay Informed
Sign up for our FREE Monthly Newsletter, used by +45,000 investors
By clicking send you'll receive occasional emails from Crux Investor. You always have the choice to unsubscribe within every email you receive.

