




New Gold Inc.
NYSE: CLOSED
TSE: CLOSED
LSE: CLOSED
HKE: CLOSED
NSE: CLOSED
BM&F: CLOSED
ASX: CLOSED
FWB: CLOSED
MOEX: CLOSED
JSE: CLOSED
DIFX: CLOSED
SSE: CLOSED
NZSX: CLOSED
TSX: CLOSED
SGX: CLOSED
NYSE: CLOSED
TSE: CLOSED
LSE: CLOSED
HKE: CLOSED
NSE: CLOSED
BM&F: CLOSED
ASX: CLOSED
FWB: CLOSED
MOEX: CLOSED
JSE: CLOSED
DIFX: CLOSED
SSE: CLOSED
NZSX: CLOSED
TSX: CLOSED
SGX: CLOSED

By Metal or Resource

By Project Stage
By Exchange
By Geography
By Investment Theme
West Red Lake Gold Mines

Crux Investor Index
7
–
Market Cap (USD)
303100000
Symbol
TSXV:WRLG
OTCQB:RLGMF
FRA:HYK
Stage of development
Development
Primary COMMODITY
Gold
Additional commodities
No items found.
Company Overview
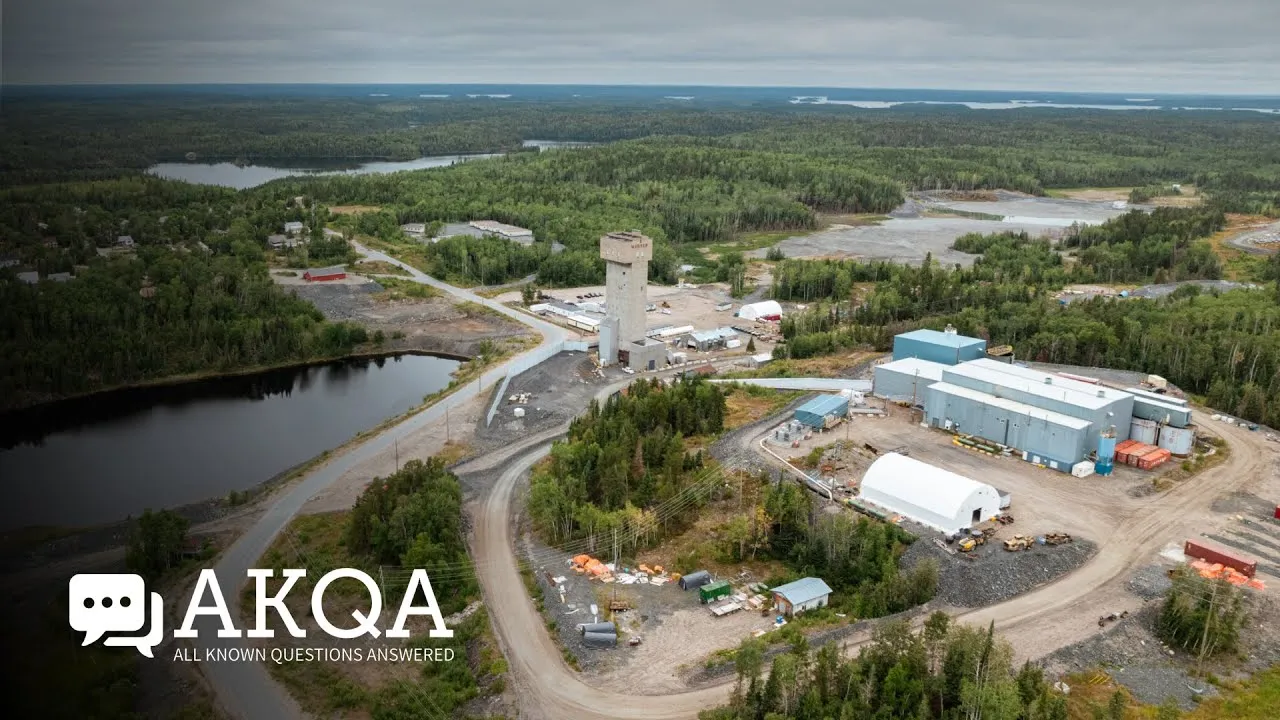
West Red Lake Gold Mines Ltd. (TSX-V: WRLG, OTCQX: WRLGF, FRA: UJ0) is a Canadian gold producer operating the Madsen Mine in the Red Lake district of northwestern Ontario, a district that has historically produced more than 20 million ounces of gold. Madsen declared commercial production on 1 January 2026 and is positioned as the central hub of a multi-asset platform built on a 47 km² land package. The company also owns the 31 km² Rowan property, which hosts three past-producing mines (Rowan, Mount Jamie and Red Summit) and sits approximately 80 km by road from the Madsen mill.
The longer-term plan is a hub-and-spoke operation in which satellite deposits feed the Madsen mill, with a stated target of more than 150,000 ounces of gold per year through organic growth and regional consolidation. Gold-focused institutions hold approximately 30% of the company and insiders approximately 10%. West Red Lake Gold was added to the VanEck Junior Gold Miners ETF (GDXJ) effective 20 March 2026, and the stock is covered by three brokerage analysts.
The company had 413.0 million shares outstanding and 554.5 million fully diluted shares as at 1 August 2026, including 110.5 million warrants. At CAD$0.75 per share on 5 August 2026, the market capitalisation was approximately CAD$310 million. Cash and cash equivalents stood at CAD$31.2 million at 30 June 2026.
Opportunity
The investment case rests on a permitted, high-grade underground mine with infrastructure already built. More than $350 million was invested at Madsen before West Red Lake Gold took ownership, and the company has added approximately $150 million since. The 100% owned Madsen mill is fully permitted, with an 800 tpd throughput rate, 1,100 tpd nameplate capacity and expansion potential, leaving room to process ore from satellite deposits without building a second plant.
Madsen hosts Indicated resources of 1.65 million ounces at 7.4 g/t gold (6.9 million tonnes) and Inferred resources of 0.37 million ounces at 6.3 g/t (1.8 million tonnes), estimated at a gold price of US$1,800 per ounce. Probable reserves total 478,000 ounces at 8.16 g/t within 1.82 million tonnes, estimated at US$1,680 per ounce, a reserve grade that ranks fourth among 17 Canadian underground mines in an analyst comparison presented by the company. Both estimates use gold prices far below the second-quarter realised price of US$4,288 per ounce. The company identifies a further area with resource potential of approximately 200,000 ounces at 7.3 g/t that was left out of the current Pre-Feasibility Study (PFS) on price grounds.
Much of the near-term opportunity sits in ground that was never mined. The Austin 904 Complex is an approximately 200 m by 200 m panel of intact mineralisation at 650 m to 700 m depth, which the company expects to allow larger, more efficient stopes than the remnant areas typical of older parts of Madsen. September 2026 definition drilling returned 5.3 m at 176.04 g/t gold, including 1 m at 925.52 g/t, at 904, alongside 6.85 m at 35.72 g/t at the neighbouring 955 Complex and 4.5 m at 128.32 g/t at South Austin.
Management
President and Chief Executive Officer Shane Williams has more than 25 years of experience in mine construction, underground development and project execution, and led the restart of Madsen and its return to production. Chief Financial Officer Harpreet Dhaliwal has more than 20 years of experience as a resource sector finance executive across producing mines. Jason Billan, Vice President Corporate Development, has more than 20 years of experience across RBC equity research and senior M&A roles, and Jaclyn Ruptash, Vice President Communications and Investor Relations, has more than 20 years in the resources sector.
The operating and technical team is led by Hayley Halsall-Whitney, P.Eng., Vice President Operations, who has more than 20 years at Canadian mining operations, including as General Manager at Wesdome Gold Mines, and is responsible for the Madsen ramp-up. Will Robinson, P.Geo., Vice President Exploration, has more than 20 years of exploration experience and was formerly Exploration Manager at Coeur Mining. Derek Teevan, Vice President Community Affairs, is a career community relations specialist in gold and diamond mining.
The board comprises Executive Chairman Tom Meredith, Shane Williams, Duncan Middlemiss, Susan Neale and John Heslop. That mix of mine-building, operating and capital markets experience suits a company completing a ramp-up while funding growth from cash flow.
Growth Strategy
The company's roadmap moves from ramp-up in 2026 to what it describes as operating leverage in 2027 and a multi-asset platform from 2029. Near-term growth centres on the 904 Complex and the Fork satellite deposit, both expected to enter the production profile in 2027. Fork is a near-surface, non-remnant deposit approximately 250 m from existing Madsen infrastructure, with resources of 20,900 ounces Indicated and 49,500 ounces Inferred at an average 5.2 g/t. Access development is under way and the company targets a high-grade core of 130,000 to 150,000 tonnes at 8 to 9 g/t for 33,000 to 43,000 ounces. The 13 Level East Drive is also advancing towards the Derlak Complex to open further mining fronts.
Rowan is the second engine of growth. The June 2026 Mineral Resource Estimate reports Indicated resources of 335,058 ounces at 13.04 g/t and Inferred resources of 179,029 ounces at 15.31 g/t, at a 2.00 g/t cut-off, and was accompanied by a maiden estimate for the Mount Jamie deposit 2 km away. A Preliminary Economic Assessment (PEA) outlines a 400 tpd underground mine producing approximately 35,000 ounces per year over five years at an average diluted grade of about 8 g/t, with ore trucked to Madsen so that no mill or tailings facility is required at Rowan. Permitting has started, initial construction is targeted for 2029 with a production ramp-up targeted for the first half of that year, and Rowan is being evaluated alongside Madsen in a proposed combined PFS.
Beyond the mine plan, the company is testing several targets close to the mill. Starratt-Olsen, 1.1 km southwest of Madsen, produced approximately 164,000 ounces at 6.17 g/t between 1948 and 1956, and the first five holes of a 12-hole, 4,100 m program returned 1.5 m at 16.16 g/t and 4.5 m at 5.16 g/t. The larger target is a down-plunge panel of approximately 300 m by 400 m with potential above 10 g/t, supported by a 2016 hole that returned 3 m at 104.1 g/t and reachable from a historic Madsen drive on 16 Level that comes within 200 m. Further upside lies in the Upper 8 discovery, the North Shore target and depth extensions at Madsen, which is defined to roughly 1.2 km while comparable Red Lake deposits extend beyond 3 km.
Financial Overview
Gold production rose 51% to 8,576 ounces and sales rose 34% to 8,260 ounces, generating revenue of CAD$49.0 million and income from mine operations of CAD$20.1 million at a 41% operating margin. Adjusted EBITDA increased 54% to CAD$22.1 million and adjusted net earnings 98% to CAD$12.6 million, or CAD$0.03 per share.
Cash costs decreased 23% to US$2,000 per ounce and all-in sustaining costs (AISC) 30% to US$3,284 per ounce, within 2026 guidance of US$2,800 to US$3,600 per ounce, although first-half AISC averaged US$3,879 per ounce. Free cash flow was CAD$9.7 million in the quarter, compared with an outflow of CAD$6.1 million in the first quarter, after sustaining capital of CAD$12.3 million and growth capital of CAD$6.3 million, mainly for the Fork access drift and shaft refurbishment.
The mine processed 842 tpd in the second quarter at 95% recovery, with 75,524 tonnes mined at 4.3 g/t, and built a surface stockpile of 10,768 tonnes containing approximately 1,500 ounces. The company expects processing to rise to approximately 1,000 tpd in the second half. 2026 guidance of 35,000 to 45,000 ounces is weighted about 60% to the second half, which, after first-half production of 14,243 ounces, implies roughly 20,800 to 30,800 ounces in the remaining two quarters. The market capitalisation of approximately CAD$310 million equates to roughly CAD$120 per ounce of combined Madsen and Rowan resources.
Risk Factors and Mitigation
- Commodity Price Volatility: Earnings are highly leveraged to the gold price in both directions. The second-quarter realised price was 13% lower than in the first quarter, so revenue rose only 17% on 34% higher sales. Second-quarter AISC of US$3,284 per ounce leaves a wide margin at current prices, and reserves estimated at US$1,680 per ounce provide a conservative base.
- Regulatory & Permitting Risks: Madsen and its mill are fully permitted, with permits held in good standing with the Ministry of Mines and the Ministry of the Environment, Conservation and Parks. Rowan has only started permitting, and its 2029 timeline depends on approvals, as would any future production from Starratt-Olsen or other satellites.
- Technical & Operational Risks: The ramp-up is incomplete. Second-quarter mined grade of 4.3 g/t was well below the 8.16 g/t reserve grade, first-half AISC sat above the top of guidance, and the high-grade intercepts reported are uncapped values in a deposit where gold is often visible and coarse. Definition drilling, access to non-remnant complexes such as 904, multiple mining fronts and the surface stockpile are intended to improve grade control and operating flexibility.
- Environmental & Social Risks: Madsen is a historic mine site with active water quality and environmental monitoring programs. The company reports ongoing consultation with local First Nations and engagement with municipal, provincial and federal stakeholders, overseen by a dedicated Vice President Community Affairs.
- Financing Risk: Cash of CAD$31.2 million must cover a period of heavy investment in underground development, shaft refurbishment, Fork and eventually Rowan. Further dilution is possible, and most of the 110.5 million warrants are exercisable at CAD$0.90 to CAD$0.95, above the August share price. Positive second-quarter free cash flow and approximately CAD$315 million of tax loss carryforwards reduce reliance on external capital.
- Execution Risk: The plan depends on delivering a back-weighted 2026, bringing 904 and Fork into production in 2027, completing the combined Madsen and Rowan PFS and starting Rowan in 2029. Management's record in restarting Madsen and the existing mill and infrastructure reduce, but do not remove, the risk of delays and cost overruns.
Conclusion
West Red Lake Gold offers exposure to a newly restarted, high-grade underground gold mine in one of Canada's most productive gold districts, with a permitted mill that has spare capacity and a pipeline of satellite deposits within trucking distance. The second quarter of 2026 delivered higher production, lower unit costs and positive free cash flow, while drilling at 904, Fork, Rowan and Starratt-Olsen continues to define the next sources of mill feed.
The main uncertainties are whether mined grades move closer to reserve grade, whether costs hold within guidance through the second half, and whether growth can be funded largely from cash flow. With the stock valued at roughly CAD$120 per resource ounce, second-half production against guidance, the combined PFS and first production from 904 and Fork in 2027 are the key milestones for investors to track.
Article
West Red Lake Gold Mines Analyst Notes

No analyst notes
Company Resources
Submitted by
West Red Lake Gold Mines
Charts
Similar Companies

Stay Informed
Sign up for our FREE Monthly Newsletter, used by +45,000 investors
By clicking send you'll receive occasional emails from Crux Investor. You always have the choice to unsubscribe within every email you receive.

