




Santacruz Silver Reviews More Acquisitions in Growing Silver-Zinc Empire


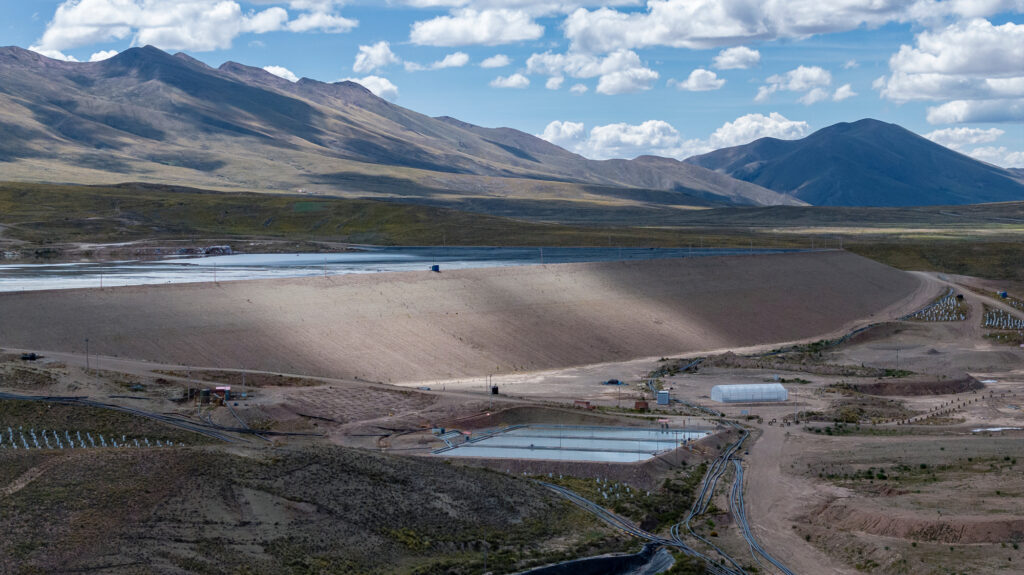
Santacruz Silver CEO Arturo Préstamo on Bolivar's recovery, Soracaya permits, a 10% production growth target for 2027 and two acquisitions under review.
- Santacruz expects Bolivar to be fully dewatered in Q4 2026, and two newly identified blocks grading 400 to 500 g/t silver could lift the mine's output by 8% to 10% from early 2027.
- The acquisition of a dedicated mill for the San Lucas ore feed business should release around 500 tonnes per day of capacity for the company's own mines, supporting further organic growth.
- Soracaya permits are expected within weeks, and the company is targeting first production by December 2026, although the resource is currently classified as Inferred only.
- Management expects Bolivar, San Lucas and Zimapan together to deliver around 10% production growth in 2027, funded entirely from cash flow with no equity raise planned.
- With cash rising from $72.8 million at June 2026 toward a CEO-stated figure of close to $120 million by end of Q3, Santacruz is seriously reviewing two acquisitions and has ruled out a dividend for now.
Santacruz Silver Mining Ltd. (NASDAQ:SCZM, TSXV:SCZ) realised an average of $76.33 per silver ounce sold in the first half of the year, up 130% from $33.13 of the previous year. This price has turned the Bolivia- and Mexico-focused producer into a strongly cash-generative business. Executive Chairman and CEO Arturo Préstamo Elizondo shared the company had held 60 meetings in three days with institutional funds, family offices, banks and other institutions. Their questions centre on two issues: how much more production the existing assets can deliver in 2027, and what the company will do with its cash.
A Year of Growth and Recovery
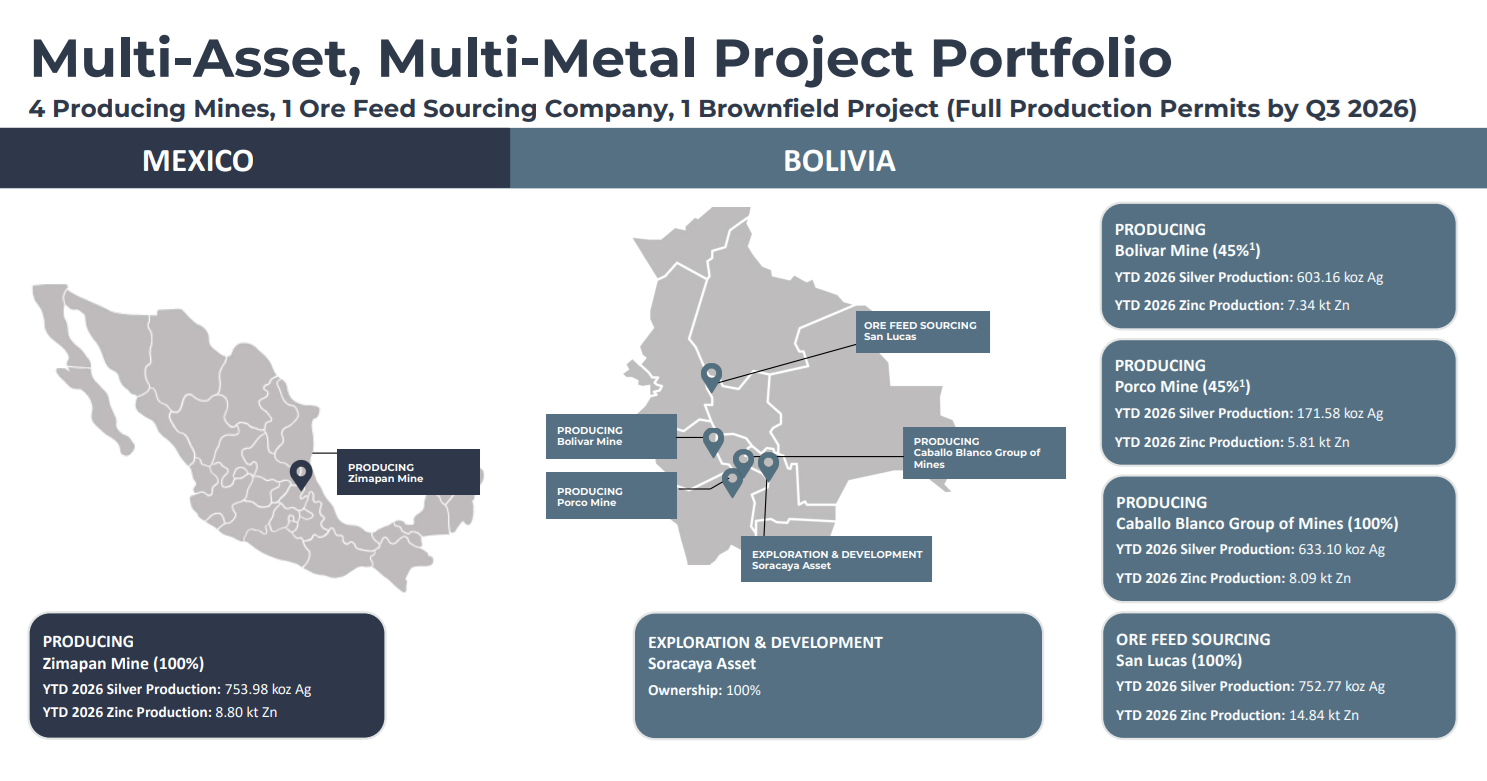
The Bolivar mine in Oruro suffered a water inflow in May 2025 that flooded two of its five veins. According to Préstamo Elizondo, the mine was producing around 1 million silver equivalent ounces per quarter before the event. Dewatering is running to schedule and the mine is expected to be fully dewatered and back at level 380 in Q4 2026, producing again from the high-grade Pomabamba and Nané veins. Bolivar milled 72,081 tonnes in Q2 2026 and produced 343,522 silver ounces, a 32% increase on the previous quarter.
Back to Pre-Flood Levels and Beyond
The flooding also prompted a review of the mine's historical records. That work identified two blocks, Pomabamba and Nané, grading 400 to 500 g/t silver. Santacruz has since drilled them, built a block model and completed a mine plan, with production targeted for early 2027. Préstamo Elizondo estimated the two blocks could lift Bolivar's output by 8% to 10%. He was clear about the direction of travel.
"Next quarter the mine will be fully dewatered will be at level 380 again and producing from high-grade silver Pomabamba and Nané veins. Early next year this mine is going to come back even stronger than when it was before the flooding."
Dedicated Mill to Free Up Capacity
San Lucas is the company's ore feed sourcing business. It buys third-party ore from regional suppliers and processes it through Santacruz's Bolivian plants. In Q2 2026 it milled 115,424 tonnes and produced 411,367 silver ounces. However, as the company's own mines grow, San Lucas increasingly competes with them for mill time. Préstamo Elizondo explained that each of the three mills serves one of the company's mines.
Santacruz has addressed this by acquiring a $14 million dedicated mill for San Lucas in the centre of the Potosí district. Préstamo said the mill will release around 500 tonnes per day of capacity on average for the company's own operations. For Porco, that equates to roughly 15% to 20% of capacity. The mill's central location should also lower transport costs, which Préstamo Elizondo said would mean cheaper ounces.
Interview with Arturo Préstamo Elizondo, Executive Chairman & CEO of Santacruz Silver
Soracaya Permits Expected Within Weeks
Soracaya is the company's exploration and development asset in Bolivia. It hosts an Inferred Resource of 4.14 million tonnes grading 260 g/t silver, containing 34.6 million silver ounces. The permitting process, which began last year, is nearing completion, and permits are expected within weeks. They had not been received at the time of the interview.
Santacruz plans to start production by December 2026 at a modest rate and ramp up gradually. At full capacity, the mine should produce close to 2.5 million ounces. The resource is entirely Inferred, so early production will also test the geological model.
Higher Grades From Untested Ground
In Mexico, Santacruz has run three drill rigs at Zimapan in Hidalgo over the past 15 months. Two of them are working in an area that had never been explored or drilled. Drilling has identified zones grading around 200 g/t silver and 7% zinc, with some copper. The first blocks from these areas are being prepared for production in 2027.
The company expects this material to lift average head grades at the mill from 78 to 80 g/t silver to close to 100 g/t. Zinc should rise from 2.7% to 3-3.5%, and copper from 0.25% to 0.40%. Throughput is set to increase from 74,000 tonnes a month to 80,000 tonnes, with 6,000 tonnes a month coming from the new high-grade areas. Capital invested in the mill this year has also improved silver recoveries. Taking Bolivar, San Lucas and Zimapan together, the company expects production to rise by around 10% in 2027.
Financial Growth Funded From Cash Flow
First-half 2026 revenue reached $241.0 million, up 68% year on year. Adjusted EBITDA rose 64% to $89.2 million. The consolidated all-in sustaining cost (AISC) was $25.34 per silver ounce sold, leaving a realised margin of $51.00 per ounce.
Cash and marketable securities stood at $72.8 million at 30 June 2026. Préstamo Elizondo stated the figure was close to $120 million as the third quarter drew to a close. He confirmed that the organic growth programme is being funded entirely from cash flow, with only standard sustaining costs required and no equity raise planned.
Capital Allocation, Two Deals Under Serious Review
With cash building, Préstamo Elizondo was direct about priorities. He does not consider this the right moment to begin paying a dividend. Instead, the company wants to keep growing through acquisition, and it is seriously reviewing two deals. Santacruz is already spending money on that process. No transaction has been agreed.
The criteria are specific.
"We want to keep growing the company with new acquisitions. The acquisition needs to be accretive to our investors as we have done the previous acquisitions in the past, and it needs to be an asset where we can add value. We feel in the Americas is our place to be especially South America in strong jurisdictions."
Santacruz wants an asset that is preferably already producing, with output above 3 million ounces of silver or the gold equivalent. Préstamo Elizondo sees the team's strength in underground narrow-vein mining and wants a project where it can add value technically, operationally and geologically. A precious metals acquisition would also rebalance a revenue base that is currently 53.2% silver and 40.3% zinc. Its past acquisitions include Zimapan in 2021 and the Bolivian assets bought from Glencore in 2022.
The Investment Thesis for Santacruz Silver
- Bolivar's recovery offers a near-term catalyst, and investors should monitor the Q3 2026 production release, due within weeks, for further quarter-on-quarter gains.
- Full dewatering in Q4 2026, followed by two 400 to 500 g/T silver blocks entering production in early 2027, could take Bolivar beyond its pre-flood run rate.
- Management expects production to rise by around 10% in 2027 from Bolivar, San Lucas and Zimapan, funded from cash flow rather than new equity.
- Soracaya permit approval is the next hard milestone, and a December 2026 start would add a new high-grade silver source, although its resource is currently Inferred only.
- Two acquisitions are under serious review, so investors should watch any announcement for purchase price, funding structure and whether it is accretive on a per-share basis.
- The company reports an enterprise value of 3.2 times annualised adjusted EBITDA, which suggests the market is not yet pricing in the planned growth.
- Key risks include Bolivian political and regulatory exposure, the COMIBOL joint operation at Bolivar and Porco that runs until 2028, and sensitivity to silver prices.
Macro Thematic Analysis
The rise in silver prices over the past year has changed the financial position of mid-tier producers. Santacruz is a clear example. It paid off its Glencore debt in 2025 and is now building a treasury that management says has grown quarter after quarter. For these companies, the central question has shifted from survival to capital allocation.
That choice typically comes down to four options. Producers can reinvest in drilling, buy back shares, pay dividends or pursue acquisitions. Santacruz is putting drilling and acquisitions ahead of shareholder returns for now.
Préstamo Elizondo framed the company's readiness in terms of its fundamentals.
"The best way to return a good investment to our investors is through growth. I think the company It's not the right moment to to start paying a dividend but we have the management in place. We have assets that are strong and cash flow producers and we have a very clean balance sheet."
The acquisition market is also changing. Rising prices lift the cash flow of potential buyers, but they also lift sellers' expectations. Préstamo Elizondo says there is no fixed formula for structuring deals, because every seller has different needs. His target of producing, underground, narrow-vein assets in the Americas narrows the field considerably. In that niche, specialist operating expertise can matter as much as balance sheet size.
The stated wish to tilt the portfolio toward precious metals is also worth noting. Zinc still accounts for around 40% of Santacruz's revenue, and the company's realised zinc margin per tonne fell 22% in the first half. A larger precious metals weighting would give investors more direct exposure to the silver and gold price.
TL;DR
Santacruz Silver (NASDAQ:SCZM, TSX:SCZ) is converting record silver prices into cash and growth. CEO Arturo Préstamo Elizondo expects Bolivar to be fully dewatered in Q4 2026, with two newly identified 400 to 500 g/T silver blocks entering production in early 2027. A dedicated $14 million San Lucas mill frees capacity at the company's own plants. Soracaya permits are expected within weeks, targeting first production by December. New high-grade zones at Zimapan should lift grades and throughput. Management expects around 10% production growth in 2027, funded from cash flow. Cash reached $72.8 million at 30 June and, per Préstamo, close to $120 million by quarter-end. Two acquisitions are under serious review. A dividend is not planned for now.
FAQ (AI-generated)
Analyst's Notes





Subscribe to Our Channel
Stay Informed


