Abitibi Metals' B26 at C$0.13 per Pound: 8 Questions Behind the Valuation Gap


Abitibi Metals' B26 trades at C$0.13/lb copper equivalent versus FireFly and Foran. Inferred conversion and the 2027 PEA will test the copper-gold valuation gap.
The Valuation Question at B26
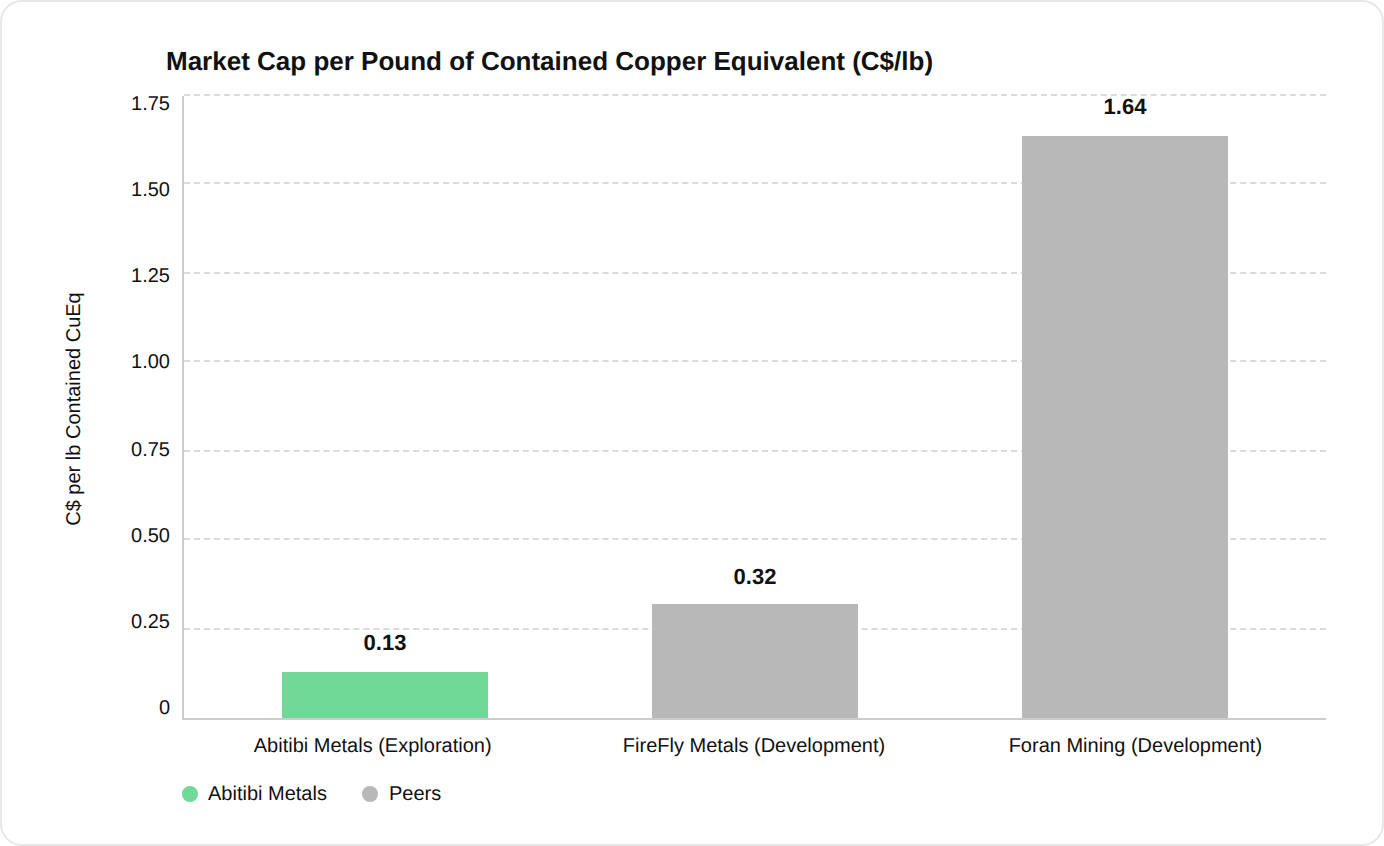
Abitibi Metals Corp. (CSE: AMQ | OTCQB: AMQFF | FSE: FW0) owns 100% of the B26 polymetallic copper-gold deposit in Québec, which hosts 12.96 million tonnes Indicated at 2.08% copper equivalent and 12.34 million tonnes Inferred at 2.20% copper equivalent. In the company's own peer comparison, the market values that metal at C$0.32 for FireFly Metals and C$1.64 for Foran Mining. The discount lines up with 3 measurable differences: project stage, resource confidence, and completed study work. Each can be tracked against Abitibi's stated schedule through 2027.
1. The C$0.13 Figure Is a Company Screen, Not a Valuation Multiple
Abitibi calculates the ratio by dividing its market capitalization of C$170 million by the contained copper equivalent in its resource: 664 million pounds Indicated and 646 million pounds Inferred. Contained metal is calculated at spot prices as of October 6, 2026, including $6.55 per pound of copper and $4,140 per ounce of gold, before metallurgical recoveries.
The number has 3 limitations. The calculation counts Inferred tonnes, which have lower confidence and cannot be converted directly to mineral reserves. It uses market capitalization without adjusting for Abitibi's C$34 million in cash. And Foran's figure is priced as of April 15, 2026, its last full trading session before delisting, while the Abitibi and FireFly figures use October 6, 2026, closes.
The market assigns less value per pound to B26 than to 2 peers. It does not explain the difference, and on its own it is not evidence that B26 is undervalued.
2. FireFly & Foran Are Priced as Development-Stage Companies
Abitibi’s comparison labels both peers as development-stage and B26 as exploration-stage. FireFly’s Green Bay deposit holds 60.2 million tonnes measured and indicated (M&I) at 2.41% copper equivalent and 23.5 million tonnes inferred at 2.51% copper equivalent on the spot basis, or 3,196 million pounds and 1,299 million pounds of contained copper equivalent, against a market capitalization of 1,421 million Canadian dollars. Abitibi’s comparison lists a preliminary economic assessment (PEA) for Green Bay at about 4,800 tonnes per day.
Foran’s McIlvenna Bay holds 38.6 million tonnes M&I at 2.04% copper equivalent on a same-spot basis and 4.5 million tonnes Inferred at 1.73% copper equivalent, or 1,737 million pounds and 172 million pounds of contained copper equivalent, against a final pre-delisting market capitalization of C$ 3,122 million. Abitibi lists the project at production of about 4,900 tonnes per day. The C$ 3.8 billion figure Abitibi cites for the Eldorado Gold and Foran Mining merger is the value of a corporate transaction for Foran as a company. It is not a valuation of the McIlvenna Bay project in isolation, nor is it a price for B26-type assets.
Abitibi's stated route to narrowing the gap is de-risking. Chief Executive Officer of Abitibi Metals, Jonathon Deluce, described the intended endpoint as a sale to a producer that would build the mine:
"While we are positioning ourselves to be capable of constructing the mine, we anticipate reaching a valuation sweet spot where Discovery Silver or another mid-tier/senior producer acquires the asset to build it."
3. Half the Tonnage Is Inferred, So Conversion Is the First Test
By tonnage, B26 splits 12.96 million tonnes Indicated and 12.34 million tonnes Inferred. By contained metal on the spot basis, the split is 664 million pounds Indicated and 646 million pounds Inferred: the Inferred category's higher grade narrows, but does not close, the gap left by its smaller tonnage. For either measure, close to half of the metal in the C$0.13 calculation falls into the lower-confidence category.
Management states that internal conversion milestones have been met and that drilling is now weighted toward Inferred growth. Deluce outlined the target for the next update:
"We are balancing all objectives. The resource stands at 25 million tonnes today, and our goal for the next update is 30 to 35 million tonnes, while maintaining strong conversion progress."
Tonnage growth and conversion answer different questions. Added Inferred tonnes raise the denominator in the per-pound screen, while conversion moves metal into the higher-confidence Indicated category. The category split in the next update will show which of the 2 the program has delivered.
4. Full Ownership Gives a Buyer 1 Counterparty & a 1% Royalty
Abitibi optioned B26 in November 2023 from SOQUEM, the Québec government subsidiary that explored the deposit for 25 years. The company completed a 7-year option agreement in about 2.5 years and bought the remaining 20% in June 2026. SOQUEM now holds a 1% net smelter return royalty, and Abitibi holds a 10-year right of first refusal over SOQUEM's adjacent Wagosic and Carheil ground.
For valuation purposes, ownership changes who a buyer or financier negotiates with: 1 owner and 1 royalty holder. It does not change the deposit's grade, tonnage, or cost profile, and Abitibi states that no economic study has been completed on B26.
5. Initial 98.2% Copper Recovery Matches the Resource Assumption
Initial metallurgical testwork returned a copper recovery of 98.2%, in line with the 98.3% assumed in the 2026 MRE. Management reports clean chalcopyrite mineralization producing a concentrate grading between 22% and 30% copper. Additional testwork is scheduled through the fourth quarter of 2026.
Abitibi's own comparison places that test result beside the recoveries it lists for its peers: 88.2% copper at McIlvenna Bay, 86.0% at Agnico Eagle's LaRonde mine and 98.0% in the Green Bay PEA.
6. The Balance Sheet Funds the Path to a First Economic Study
As of October 6, 2026, Abitibi held C$34 million in cash, with no warrants outstanding, 242 million shares issued and outstanding, and 251 million shares on a fully diluted basis. The company has 80,000 meters of drilling funded through 2027, including 40,000 meters in 2026, and management expects to end the year with C$28 million to C$29 million in cash. The May 2026 financing was structured to fund operations through 2027 and to deliver both an updated resource estimate and a PEA.
Cost per pound found is the second funding input. Abitibi reports a discovery cost of C$0.13 that the market assigns to it, although the discovery cost is calculated at MRE metal prices, while the C$0.13 is based on October 6, 2026 spot prices.
7. Technical Work Before the PEA Is Still in Progress
Abitibi started an internal scoping study in the first quarter of 2026, with technical studies running from the second through the fourth quarter and the PEA targeted for 2027. The company's schedule lists first-phase geotechnical, hydrogeology, and whole-rock characterization work, followed by second-phase metallurgical, geotechnical, and hydrogeology programs. Early environmental baseline and hydrogeology work has begun, and the company's schedule lists the environmental baseline program to commence in 2027.
Several cost-relevant inputs are already defined. B26 is located 7 kilometers southeast of the former Selbaie mine on a brownfield property, with an existing mill, road, and 120-kilovolt power infrastructure on site. The deposit averages about 8 m wide with a near-vertical dip of about 80°, which Abitibi describes as amenable to conventional underground mining. Dave Bernier, Abitibi's Chief Operating Officer, held the same role at Foran Mining, where he advanced McIlvenna Bay to the construction phase. None of these inputs has a cost estimate attached yet. The PEA will be the first published estimate of capital and operating costs for B26.
8. The Market Has Already Repriced Abitibi Once
Between November 20, 2023 and October 5, 2026, Abitibi's market capitalization rose from about C$17 million to about C$170 million, and its share price rose about 159% from about C$0.27 to about C$0.70. Copper rose about 75% over the same period, from about US$3.74 per pound to about US$6.55 per pound.
Discovery Silver took a 9.9% stake through the May 2026 financing, priced at C$0.58 per share. That entry price is a reference point for what a single producer paid for a minority position at a specific date. It is not a fair-value marker, nor a floor under the share price. The broader register includes the Deluce family office at 20.8%, Beedie Capital at 9.6% and institutions at 15.4%.
Catalysts to Watch
The next resource update is the first test. Its tonnage will be measured against the 30 to 35 million tonne target, and the split between Indicated and Inferred will determine how much of the metal in the per-pound comparison moves into the higher-confidence category. Additional metallurgical testwork through the fourth quarter of 2026 will show whether copper recovery stays near the initial 98.2% result.
The PEA targeted for 2027 will provide the first published estimates of capital cost, operating cost, mine plan and production rate for B26. In the meantime, year-end cash against the C$28 to C$29 million guidance will show whether drilling and study work remain within the funded plan.
Bottom Line
On a peer-comparison basis, Abitibi trades at C$0.32 and C$1.64 relative to 2 development-stage peers. Ownership, funding through 2027, and initial metallurgy are in place. The Indicated-to-Inferred split in the next resource update and the cost estimates in the 2027 PEA will show how much of that discount reflects stage and how much reflects the deposit itself.
Analyst's Notes





Subscribe to Our Channel
Stay Informed