




Silvercorp Dual Mines El Domo and Tulkubash & Kyzyltash Target 2027 Gold Pour


Silvercorp Metals is building El Domo in Ecuador and a heap leach gold mine in Kyrgyzstan as China operations recover from a June safety pause. Here's the plan.
- Silvercorp restarted its Ying operations after a proactive June safety pause, and throughput was close to 90-100% of target by the end of September.
- El Domo in Ecuador remains on track for July 2027 commissioning despite two heavy rainy seasons, and its $284 million capital cost is partly funded by a $175 million Wheaton stream.
- Silvercorp paid an effective $150 million for a 70% controlling interest in around 5.5 million ounces of gold in Kyrgyzstan, an asset previously advanced by Chaarat Gold.
- A permitted Phase 1 heap leach in Kyrgyzstan targets first ore in 2027, and its cash flow is intended to help fund a Phase 2 previously scoped at 200,000-230,000 ounces a year for 18 years.
- Delivering two mine builds at once is both the company's main execution risk and its clearest path to a re-rating away from the China discount.
For most of its history, Silvercorp Metals Inc. (TSX:SVM, NYSE American:SVM) has been valued as a China silver producer. The ounces and cash flow were real, but the market never settled on how to price a business concentrated in one jurisdiction. That profile is now changing. The company is building two mines at once, a copper-gold operation in Ecuador and a heap leach gold operation in Kyrgyzstan, while its Chinese mines continue to generate cash.
President Lon Shaver said sector sentiment remains positive despite recent volatility. For investors, the central question is whether Silvercorp can deliver both builds on time.
China Operations Return After Safety Review
In June, a fatal accident at a coal mine in another region of China prompted a national safety review. The investigation found criminal negligence by mine management and complicity by some local regulators and politicians. New directives followed from central government for provincial authorities to carry out.
Silvercorp responded by proactively shutting its mines to review its own safety systems. Operations at the Ying Mining District have since restarted, and the company is installing the additional safety systems now required. Shaver noted that some measures are better suited to coal mines, which carry different risks from hard rock operations. He nonetheless framed the upgrades as making Silvercorp a safer company over the long term.
There was little output in July. Ying returned to about 60% of targeted throughput in August and was running at close to 90-100% by the end of September. Shaver described the disruption as a one-time event, noting that the mineralisation has not gone anywhere. Several factors should soften the financial impact. Zinc prices have been strong, and zinc treatment and refining charges have moved in miners' favour. Shaver attributed this partly to lost lead-zinc production in China, which has left domestic smelters short of concentrate. Silvercorp sells all of its output domestically in renminbi (RMB), which has strengthened against the US dollar.
El Domo Pushes Toward July 2027 Commissioning
El Domo, the company's copper-gold project in Ecuador, is in the final push toward a July 2027 commissioning target. Weather has been the main challenge. A very wet rainy season in early 2025 was followed by an even wetter one in early 2026, using up some schedule slack. In-country contractors able to deploy large teams and equipment fleets have kept the target within reach. The mill equipment is currently at sea, and the contractor to assemble the process plant has been lined up.
Shaver's lesson is to invest heavily up front in water diversion channels and to use concrete for culverts and roads so they do not wash away.
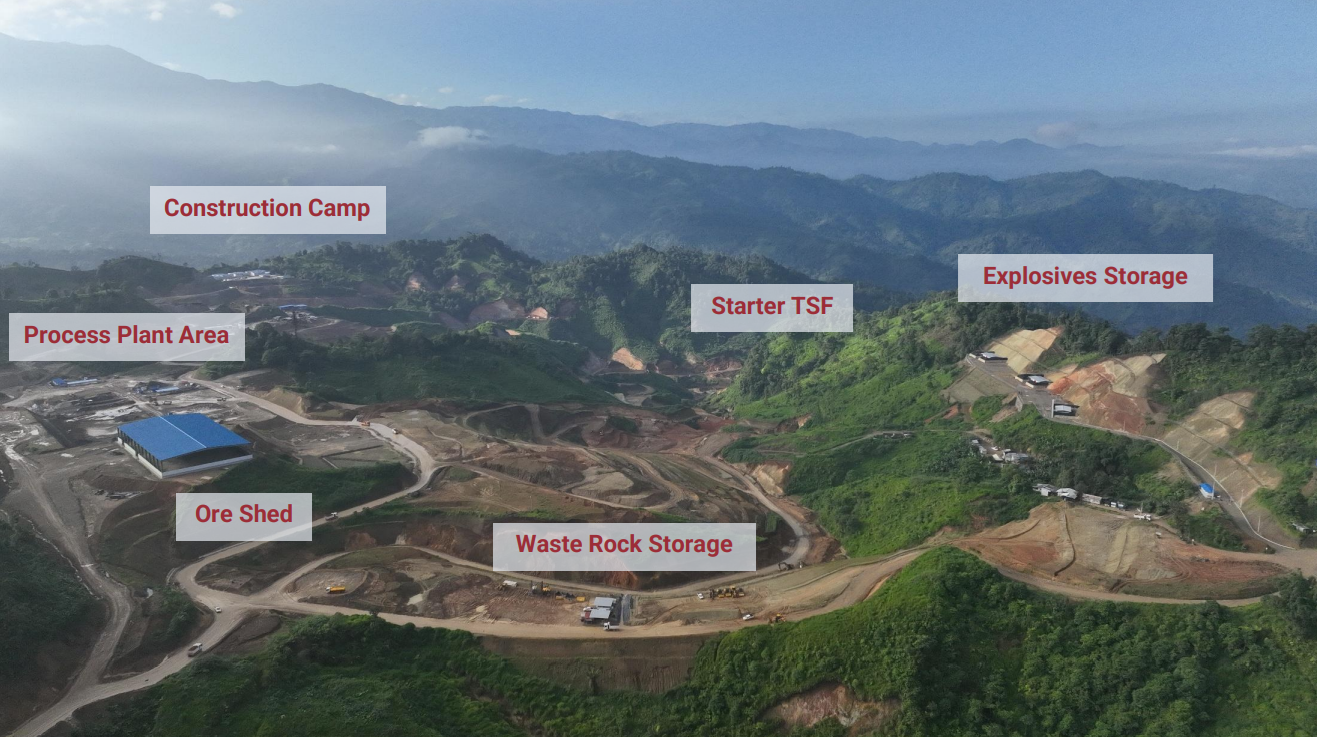
Shaver put the Chinese operations at a revenue run-rate of roughly $550 million. He estimated that El Domo will add roughly $200 million a year, a little under half of it from copper. The capital cost is $284 million. Wheaton Precious Metals is contributing $175 million through a stream, and Silvercorp has drawn about half so far. The two remaining tranches are tied to construction milestones, with the balance funded from cash on hand. Shaver cited a payback of two to three years at $3,350/oz gold and $5/lb copper, both below current spot prices. Exploration around El Domo ishas not yet started while the team focuses entirely on building the mine set out in the feasibility study.
Six Million Ounces at a Distressed Price
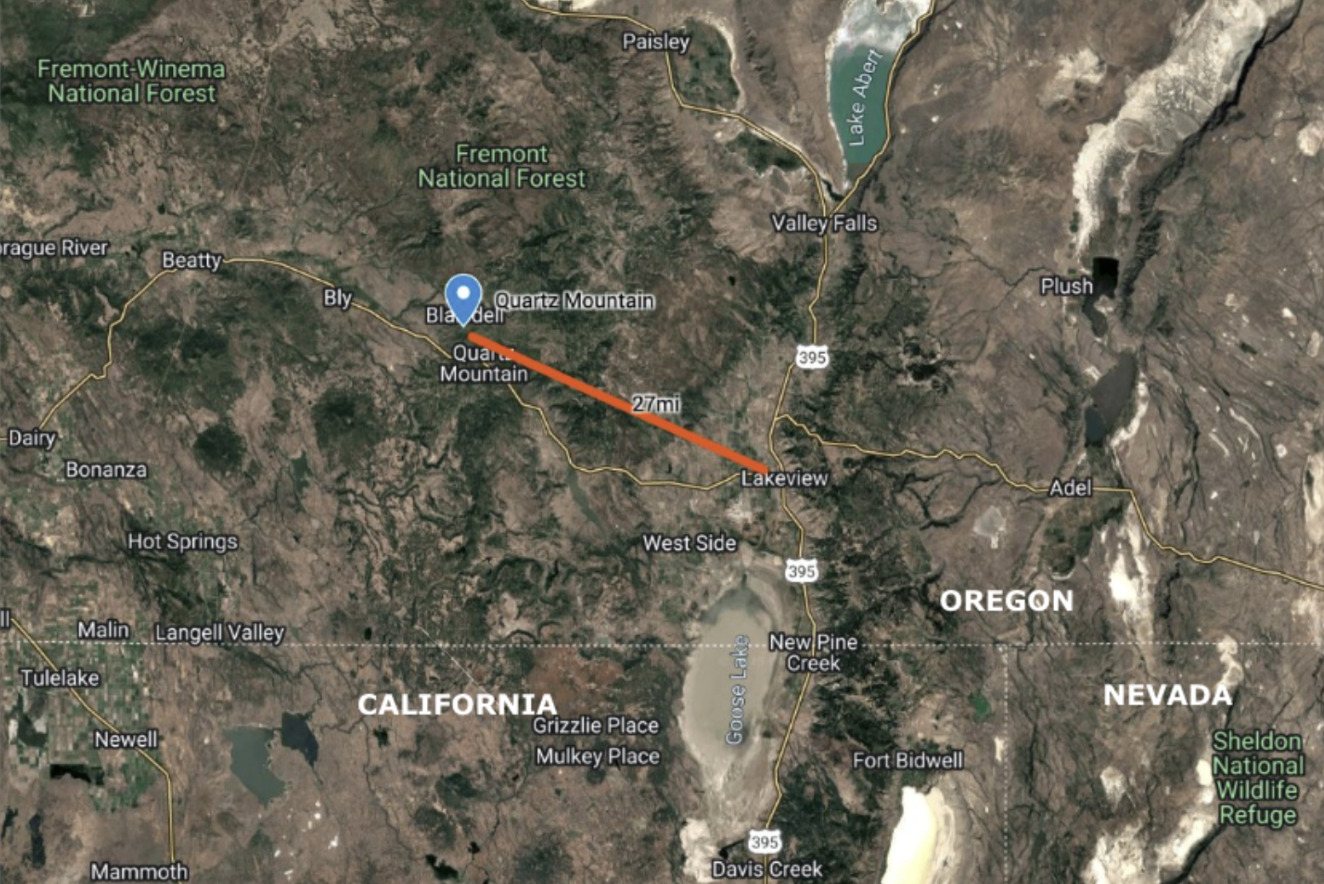
The second build is in Kyrgyzstan, a country many investors associate with Centerra Gold's well-publicised dispute with the government. Shaver noted that other mines have operated there since, several owned by Chinese and Turkish groups. He described dealings with the government as very positive and supportive. Kyrgyzaltyn, the state gold company, holds the minority interest, and two of its board representatives recently visited the site.
The asset was previously advanced by London-based Chaarat Gold, which Shaver said spent around $180 million on it. Chaarat financed the project with a note it failed to refinance. The lenders foreclosed, the company was delisted from London's Alternative Investment Market (AIM) and the asset was put up for sale. Shaver believes it was poorly marketed and misunderstood.
Silvercorp is spending effectively $150 million for a 70% controlling interest in a resource of 5.5 million ounces of gold. Shaver was direct about why the company looks where others do not:
"If you think of the price tag to buy six million ounces of gold permitted, soft of ready-to-go situation, show me a place where you can get that for $150 million. You have to be thinking out of the box and looking into some other jurisdictions where others aren't as active."
He stressed that the approach is backed by due diligence and favours staged development, which limits capital at risk.
Interview with Lon Shaver, President of Silvercorp Metals Inc.
Phase 1 Cash Flow to Fund Phase 2
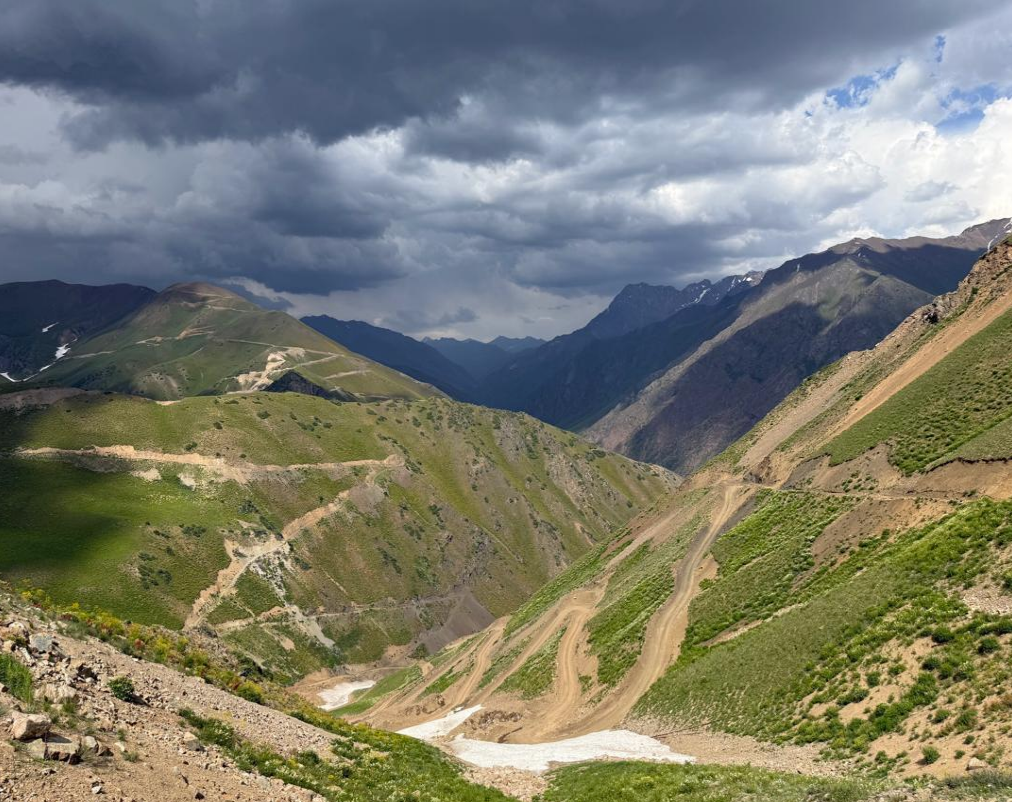
The acquisition closed in January, but the mountain site was snowed in. Silvercorp cleared the roads and gained access in May. Since then it has prepared heap leach pad areas, levelled the crushing plant site and set up solution ponds and space for the adsorption, desorption and recovery (ADR) plant. The same contractor working in Ecuador is stripping the pit and building access roads, and a camp is complete. The target is first ore on the heap leach pads later in 2027.
Phase 1 is a permitted open pit heap leach operation that Shaver said is budgeted at around $160 million. Its current life is about four years, which Shaver believes could be extended by two years or even doubled based on other drilled zones.
Phase 1 cash flow is intended to help fund Phase 2, the larger and longer-life project. As previously scoped, Phase 2 would produce 200,000-230,000 ounces of gold a year for 18 years. Shaver described it as a base-load gold asset that would dramatically change Silvercorp's revenue and cash flow profile.
From Producer to Builder
Few companies are building two mines at the same time. Shaver admitted the position is both exciting and nerve-wracking. Silvercorp is combining staff from China and Vancouver with new hires from across Latin America to create a construction team it can redeploy, including to a second project in Ecuador. The company remains open to acquiring production. With a visible pipeline, Shaver believes it can also take on earlier-stage projects and develop them in-house.
The Investment Thesis for Silvercorp
- Silvercorp is moving from a single-jurisdiction China silver producer to a multi-jurisdictional builder with copper and gold growth.
- Management expects El Domo to add roughly $200 million in annual revenue from a $284 million capital cost, with commissioning targeted for July 2027.
- An effective $150 million bought a 70% controlling interest in 5.5 million ounces of gold, with a permitted first phase already under construction.
- Phase 1 heap leach cash flow is designed to help fund a Phase 2 previously scoped at 200,000-230,000 ounces a year over 18 years.
- Key risks include weather pressure at El Domo, running two builds at once, perceived Kyrgyz jurisdictional risk and evolving Chinese safety regulation.
- Investors should monitor Ying's return to full throughput, any revised fiscal 2027 guidance, the remaining Wheaton tranches and first ore on the Kyrgyz pads in 2027.
Macro Thematic Analysis
Precious metals equities remain well supported despite recent volatility. Shaver frames the current pullback as an opportunity rather than a turning point:
"I think people are viewing it as a re-entry point to get into the sector if they weren't exposed and I think most people are of the view that this mining cycle is still in the early to mid stages and we would tend to agree."
If that reading is right, the companies best placed to benefit are those that can bring new production online within the cycle. El Domo is scheduled to commission in 2027, and the Kyrgyz heap leach is targeting first ore later that year. Both would add copper and gold revenue while prices remain elevated.
Jurisdiction is the second theme. Permitted, multi-million-ounce gold assets in established regions now command premium prices. That has pushed growth-minded producers toward jurisdictions where competition for assets is thinner. The trade-off is higher perceived risk, which Silvercorp is managing through staged development.
Climate is an emerging operational theme. Two consecutive heavy rainy seasons have tested the El Domo schedule. Shaver expects the market to get used to weather-related disruption in both construction and operations.
China's tightening safety oversight also has a market dimension. Lost lead-zinc production has left smelters short of concentrate, improving terms for producers still operating. For Silvercorp, that partly offsets the cost of its own pause.
TL;DR
Silvercorp Metals (TSX:SVM) is transforming from a China silver producer into a multi-jurisdictional builder. Its Ying mines were proactively paused in June after a national safety review and were back near full throughput by late September, with strong zinc terms and a firmer RMB softening the impact. El Domo in Ecuador remains on track for July 2027 commissioning despite two heavy rainy seasons, with a $284 million capital cost partly funded by a $175 million Wheaton stream. In Kyrgyzstan, an effective $150 million bought 70% of around 5.5 million ounces of gold. A permitted Phase 1 heap leach targets first ore in 2027 and is intended to help fund a far larger Phase 2.
FAQ (AI-generated)
Analyst's Notes





Subscribe to Our Channel
Stay Informed


