Empress Royalty's Pending US$62M Tongon Stream Adds Exploration Upside


Empress Royalty (TSXV:EMPR) agrees a US$62M Tongon gold stream, funded by Appian debt. Chairman David Rhodes on terms, margin, exploration and pipeline.
- Empress Royalty has entered into a Stream Purchase Agreement with Appian Tongon Streamco Ltd. to acquire its interest in the gold stream on the Tongon Gold Mine in Côte d'Ivoire for an upfront payment of $62M
- The stream starts at 3.58% of payable gold with an ongoing payment of just 0.5% of the gold price per ounce, giving Empress an unusually high margin on delivered gold.
- Seller Appian is also financing the deal through a US$75 million facility with no principal repayments in the first year, which introduces meaningful leverage for a company valued at about US$98 million.
- Executive Chairman David Rhodes sees exploration by new owner Atlantic Group as the main long-term upside, with production potentially returning towards historical levels.
- The existing four-asset portfolio generated US$17.3 million of revenue in H1 2026, and closing, updated GEO guidance and any follow-on deal are the key catalysts to watch.
Royalty and streaming companies have spent the past two years in an awkward position. Record gold prices lifted the value of existing portfolios, but they also pushed sellers' price expectations to levels that made new acquisitions hard to justify. Empress Royalty Corp. (TSXV:EMPR) has now agreed its largest transaction to date, a US$62 million gold stream on the Tongon mine in Côte d'Ivoire. Speaking at an investor conference in Colorado Springs, Executive Chairman David Rhodes explained how the deal came together and why the company believes it changes its profile. The transaction had not closed at the time of the interview. It remains subject to confirmatory due diligence, the lender's requirements and corporate, counterparty, regulatory and TSX Venture Exchange approvals.
The Tongon Stream
The opportunity came through Endeavour Financial, Empress's investment manager and a significant shareholder. Rhodes said Endeavour Financial has known Appian, the stream's seller, since Appian's inception and does regular business with the firm. Under the agreed terms, Empress will pay US$62 million upfront for 3.58% of payable gold from Tongon until 400,000 cumulative ounces have been delivered. The rate then falls to 2.93%, and later to 0.81% for the remainder of a term of roughly 29 years. Rhodes also referred to contingent payments linked to future production. The ongoing payment on delivery is unusually low at 0.5% of the prevailing gold price for each ounce, according to the company's announcement.
Rhodes contrasted this with streams where the buyer typically pays around 20% of spot on delivery, and credited Appian with negotiating the margin. Tongon produced approximately 125,600 ounces of gold in 2025 and has delivered more than 3 million ounces since commercial production began in late 2010.
Due Diligence and Lender Validation
Asked whether Empress had leaned on the seller's work, Rhodes said the company ran its own process. Technical advisor David Laing, a former chief operating officer of Endeavour Mining with operating experience in Côte d'Ivoire, led the site visit. An independent engineering firm and legal teams reviewed the asset and the documentation. Appian is also providing the acquisition financing. Rhodes said this dual role, with Appian earning from both the sale and the loan, ranked Empress higher in the process. He also pointed to what the financing signals about the underlying asset.
"If someone's lending the money to buy an asset then they must believe in the asset. So, it's a bit of a validation of the quality of the asset because they're willing to lend backed by that asset."
Interview with David Rhodes, Executive Chairman of Empress Royalty Corp.
Financing Structure and Balance Sheet
The acquisition is funded through a US$75 million credit facility from an Appian affiliate. It comprises a US$55 million initial draw and a further US$20 million available for future use. The facility runs for 36 months at 7.50% per year plus three-month Term SOFR, with a 3.50% SOFR floor. There are no scheduled principal repayments in the first 12 months. Appian will receive warrants equal to 2.2% of fully diluted shares for the initial draw.
Rhodes framed the structure as a way to preserve cash and limit dilution. He said the first year would be used to build cash on the balance sheet before a two-year repayment profile begins. As of June 2026, Empress held US$21.1 million in cash and liquid metals, of which US$5.1 million was cash. The US$62 million upfront payment is equivalent to roughly 63% of the company's market capitalisation of about US$98 million as of 25 September 2026.
Portfolio Base and Revenue Growth
Tongon would join four producing interests. These are the Tahuehueto silver stream in Mexico, operated by Luca Mining, the Sierra Antapite gold stream in Peru, the Galaxy gold stream in South Africa and the Manica gold royalty in Mozambique.
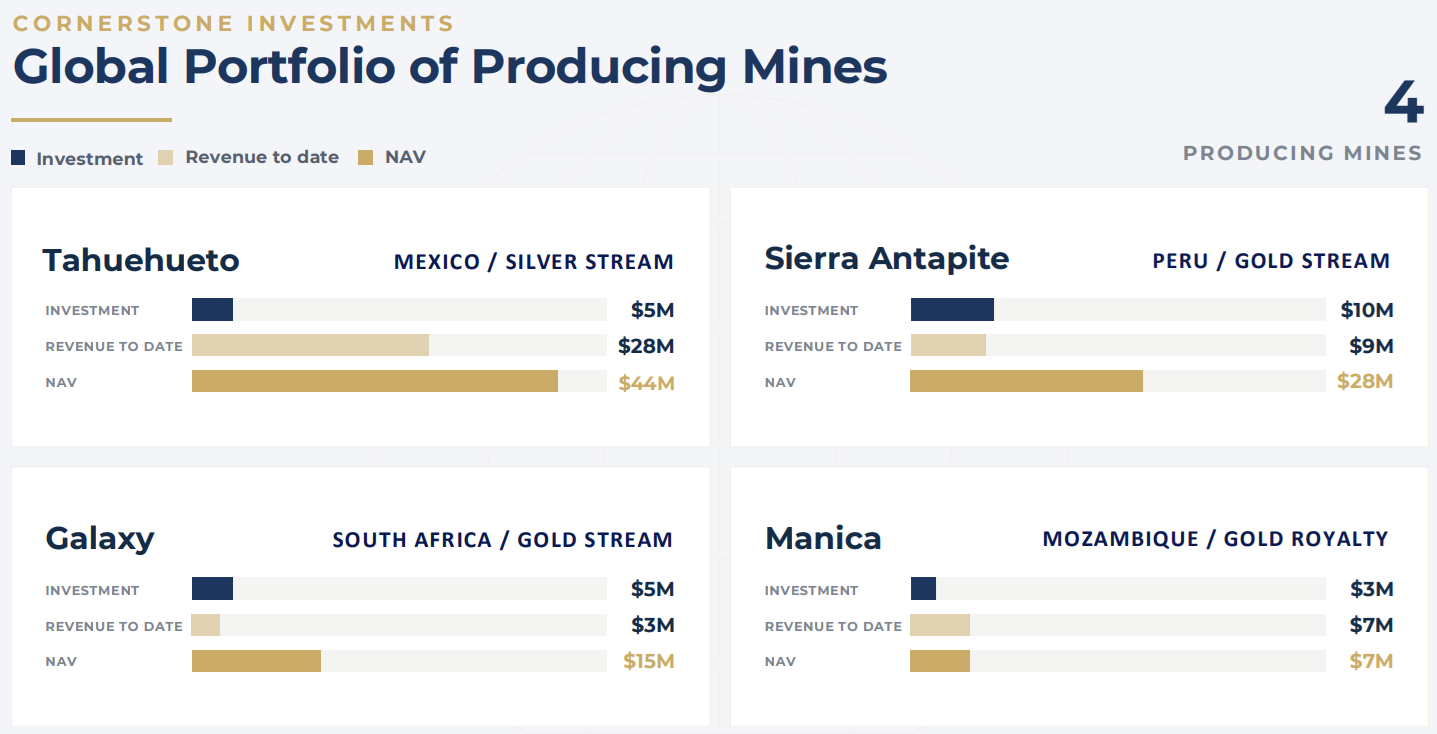
Empress reported record revenue of US$17.2 million for 2025. It then generated US$17.3 million in the first half of 2026, up 166% from US$6.5 million a year earlier. Income from operations rose to US$10.0 million. Full-year 2026 guidance stands at 7,045 to 7,430 gold equivalent ounces (GEOs), based on US$4,000/oz gold and US$70/oz silver. Rhodes said revenue doubled last year and that Tongon should help deliver similar growth again. In July, Empress also added 14 North American net smelter return (NSR) royalties from Almadex Minerals for US$2.5 million. That package offers longer-dated exploration optionality rather than near-term cash flow. The company's presentation places Empress at 3.44x price to 2026 cash flow, against a peer average of 19.37x on consensus estimates.
Exploration Upside and Operator Engagement
Rhodes placed the long-term case for Tongon on exploration rather than current output. The mine was developed by Randgold and later held by Barrick. Rhodes said majors tend to step back from exploration once an asset falls below around 200,000 ounces a year. Atlantic Group, a large African conglomerate, acquired Tongon from Barrick in 2025 and now treats it as a core holding. According to Rhodes, the new owner is reinvesting cash flow from current gold prices into exploration. He said three further deposits are at the exploration stage and that the stream covers a large land package. Empress's site work, he added, confirmed the potential to lift production back towards the levels achieved under previous ownership. Because Empress will not operate Tongon, information flow matters. Rhodes said the company holds monthly calls with Atlantic's management and receives monthly reports.
Capital Discipline and Deal Pipeline
Rhodes acknowledged that the deal took a long time to arrive. When gold traded near US$5,000/oz, he said, counterparties were pricing deals on long-term assumptions of US$6,000/oz, and Empress saw no value in transacting. A later pullback in the gold price made sellers more realistic. He rejected the suggestion that the market had marked the company down for inactivity.
"We're never going to be a company that just does a deal for press release. It's not the style. Rome wasn't built in a day. We're building a long-term sustainable business."
Rhodes said Empress rejects many transactions on technical, financial and environmental, social and governance (ESG) grounds, but more deals are now passing those tests. He confirmed that Appian holds further assets it is looking to sell. He also expects the size of the Tongon deal to put Empress on the radar of private equity firms seeking to monetise their streams. The company's presentation cites more than US$50 million of deals under review.
The Investment Thesis for Empress Royalty
- Tongon would add a large, long-life gold stream to a portfolio currently built on four smaller producing interests.
- The 0.5% ongoing payment per ounce leaves Empress with an unusually high margin on delivered gold compared with conventional stream structures.
- Exploration by a well-funded new owner offers potential upside that is not paid for in the upfront price.
- The deal remains pending, so investors should watch for confirmation of closing and the first reported deliveries from Tongon.
- The US$55 million initial draw at a floating rate of at least 11% introduces meaningful leverage and concentration risk for a company of Empress's size.
- Updated 2027 GEO guidance including Tongon will be the key test of whether the deal is accretive on a per-share basis.
- Any second acquisition from Appian or from private equity sellers would indicate whether Tongon is a repeatable model or a one-off.
Macro Thematic Analysis
The Tongon transaction reflects a broader pattern in gold mining. Majors have spent several years pruning portfolios to focus on tier-one assets, leaving mid-sized mines in the hands of regional operators and private capital. Barrick's sale of Tongon to Atlantic Group fits that pattern. New owners often need capital for exploration and expansion. Smaller streamers with credible technical teams can compete for assets that are too small to interest the largest royalty companies.
Higher metal prices are also reviving projects that had stalled. Rhodes described how the shift in price is changing the quality of opportunities reaching Empress.
"Once you got gold prices and silver prices now moving up, you get people dusting off their feasibility studies doing the work because they've got a bit of capital behind them."
This runs against a common assumption. Strong markets usually make equity easier to raise, which could reduce demand for royalty and stream finance. Rhodes argued the opposite. In his view, management teams still believe their shares are undervalued even at high metal prices, and a stream can cost far less than the dilution from a large equity raise. That makes streaming a competitive source of capital across the cycle rather than only in tight markets.
The risks are the mirror image of the opportunity. Royalty valuations remain sensitive to gold price assumptions, and a lower price deck would reduce the cash available to service acquisition debt. Competition for producing streams is also intense, which can compress returns for buyers without sourcing advantages.
TL;DR
Empress Royalty (TSXV:EMPR) has agreed, but not yet closed, a US$62 million stream on Barrick's former Tongon gold mine in Côte d'Ivoire, now owned by Atlantic Group. The stream starts at 3.58% of payable gold with a 0.5% ongoing payment per ounce, giving an unusually high margin. Seller Appian is also lending US$55 million under a US$75 million facility with no principal repayments in year one. Executive Chairman David Rhodes says exploration by the new owner is the main upside. The deal adds scale to a four-asset portfolio that generated US$17.3 million of revenue in H1 2026, but brings new leverage.
FAQ (AI-generated)
Analyst's Notes





Subscribe to Our Channel

Stay Informed