Western Exploration Lines Up Catalysts for Multiple Gold Projects in Nevada


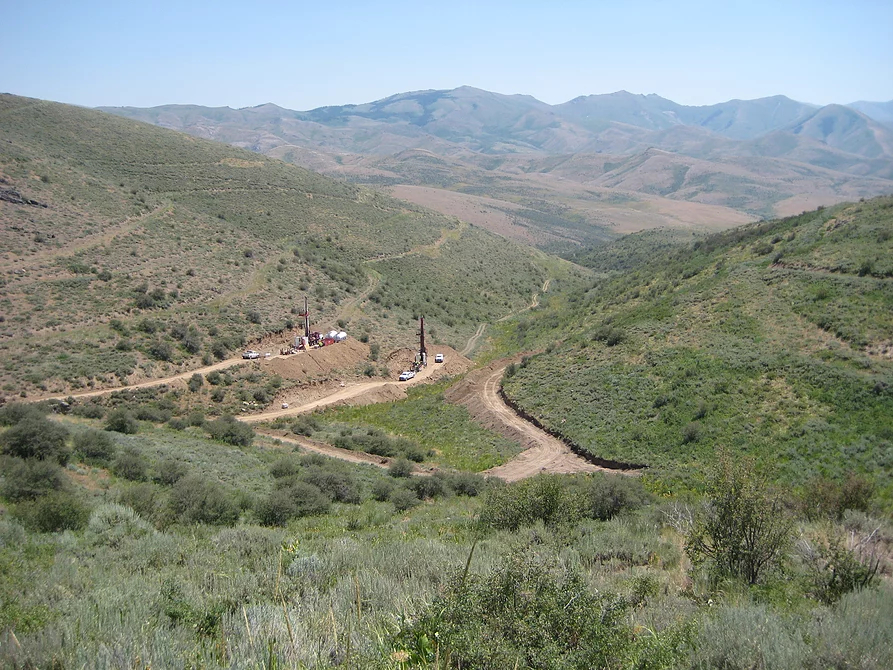
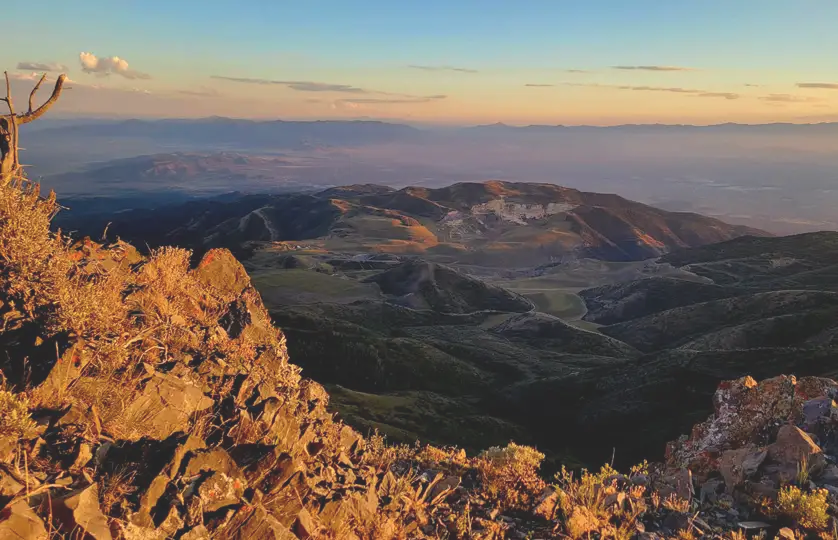
Western Exploration (TSXV:WEX) is permitting its Doby George oxide gold project in Nevada, targeting 2030 production while growing high-grade Gravel Creek.
- Doby George's 2025 PEA shows a US$211.2 million after-tax NPV and 62.2% IRR at US$3,000/oz gold on US$115.2 million of initial capital.
- The Mine Plan of Operations is with the US Forest Service, with a record of decision targeted for the end of 2027 and first production in 2030.
- Gravel Creek holds about 1 million gold-equivalent ounces, remains open, and new metallurgy points to on-site doré production.
- The management team has discovered, built and run mines together for more than two decades, including El Peñón in Chile.
- Key risks are permitting timelines and financing a US$115.2 million build from a market capitalisation of about C$50 million.
Rising metal prices have brought investors back to North American gold developers, and Nevada is still the jurisdiction many look at first. Western Exploration Inc. (TSXV:WEX, OTCQX:WEXPF) is a Nevada-focused exploration and development company with two assets in the north-east of the state, close to the Idaho border. Its 100%-owned Aura project hosts a total resource of about 1.5 million gold-equivalent ounces across the Doby George oxide gold deposit and the Gravel Creek high-grade gold-silver discovery. President and CEO Darcy Marud argued that the company should not be read as a pure exploration story. The company plan is to permit and build a modest heap leach mine at Doby George and use its cash flow to fund a larger enterprise built around Gravel Creek. The company's market capitalization is about C$50 million. The distance between that figure and Doby George's study economics sits at the heart of the investment case.
Doby George: A Simple Oxide Project With Deep Data
Homestake discovered Doby George in the 1980s. Western acquired it as a private company in the late 1990s, by which point the deposit had over 800 drill holes. An operator called Atlas had planned to put it into production in 1998, but a falling gold price and a change in business model ended that plan.
Much of the historical drilling used reverse circulation and predates modern quality assurance and quality control (QA/QC) standards and NI 43-101 reporting. Western ran confirmation drilling using both reverse circulation and diamond methods. A 2021 technical report by Mine Development Associates (MDA) in Reno reviewed the data, and any historical results that did not meet current QA/QC standards were redrilled or left out of the resource. A second round of drilling in 2022 targeted areas short of diamond core. Metallurgical work was completed by Kappes, Cassiday & Associates (KCA) and McClelland Laboratories.
The 2025 Preliminary Economic Assessment (PEA) outlines an open-pit, heap leach operation with an adsorption-desorption-recovery (ADR) plant. It produces about 58,700 ounces of gold per year over a five-year mine life at a life-of-mine grade of 1.01 g/T. At $3,000/oz gold, the PEA gives an after-tax net present value (NPV) of US$211.2 million, an internal rate of return (IRR) of 62.2% and all-in sustaining costs (AISC) of $1,197/oz. Initial capital is US$115.2 million. Marud said that at current gold prices, the NPV is close to half a billion dollars.
He put annual cash flow at more than $150 million at the three-year trailing average gold price of $3,400/oz. The PEA itself gives first-year operating cash flow of $145.6 million at that price. Marud also said the company can see a further couple of hundred thousand ounces of oxide material that could be added to the mine plan after permitting, with a target mine life of seven to ten years.
Permitting First, Pre-Feasibility Second
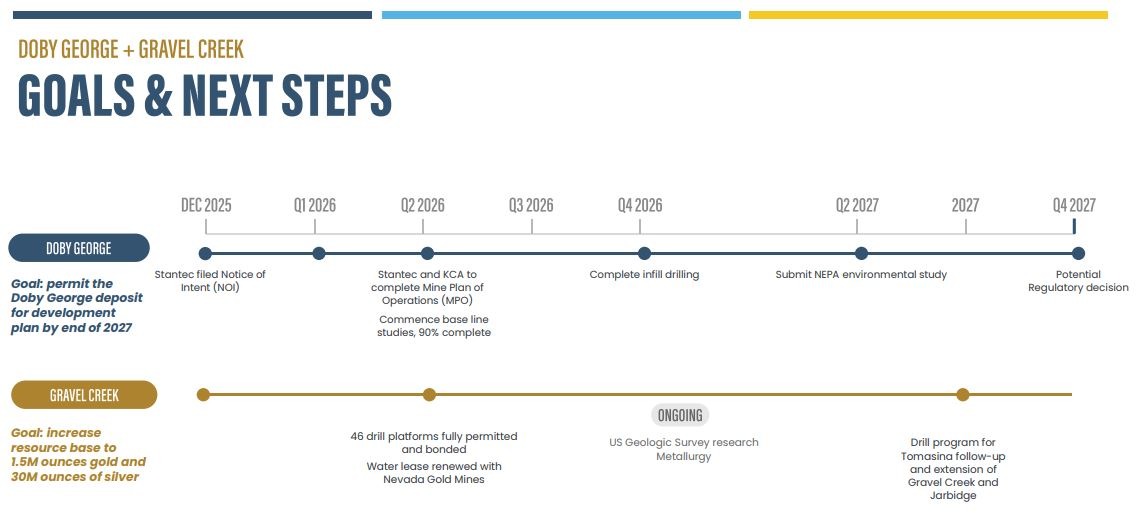
Marud described permitting as the longest-lead item for Doby George. The company therefore started the process early rather than waiting for further studies. Western has submitted its Mine Plan of Operations to the US Forest Service (USFS), which both regulates and owns the land. The plan is based on the PEA, with extra engineering from KCA. A submission does not guarantee a permit, and the review is still at an early stage.
Marud explained that the order of work is deliberate. The USFS will respond with specific concerns, and the company wants that feedback before it finalises its technical study.
A Pre-Feasibility Study (PFS) is planned for early to mid-2027. The company is targeting a USFS record of decision at the end of 2027. State permitting and a possible Environmental Impact Statement (EIS) could take a further 12 to 18 months. That points to a construction decision in 2028 or 2029 and first production in 2030. Marud said he sees no red flags in the permitting process and described it as a matter of working through the timeline.
Gravel Creek: The High-Grade Growth Engine
Gravel Creek sits about 8 km from Doby George. The company discovered it in 2013, and the Gravel Creek and Wood Gulch areas now hold about 1 million gold-equivalent ounces from roughly 100 drill holes. It is a low-sulphidation epithermal deposit aged 15 to 16 million years. That places it in the same age bracket as the historic Midas, Sleeper, Ivanhoe and DeLamar deposits of northern Nevada, with the same mineralogy, style and host rocks.
Last year's resource update increased gold ounces by more than 50% and silver ounces by 83%. Much of that growth came from the Jarbidge discovery, where veins grade up to 2 oz/t gold and carry kilograms of silver per tonne. Marud said the discovery has opened up more than a kilometre of ground to the north-east and north-west for exploration.
Metallurgy has been the main question over Gravel Creek. The market had seen it as a refractory deposit, implying high capital and operating costs or a sale of concentrate to a third party. A recent Cyanide Leach test work showed that gravity and flotation concentrate can be ultra-fine ground and cyanide-leached to produce doré on site. Results reported 73.3% gold and 74% silver recovery from that route, and further test work to lift recoveries is due by the end of 2026. Marud estimated that controlling processing in-house could be worth about a quarter of a million ounces of extra resource. A PEA on Gravel Creek is targeted for the 2028-2029 period.
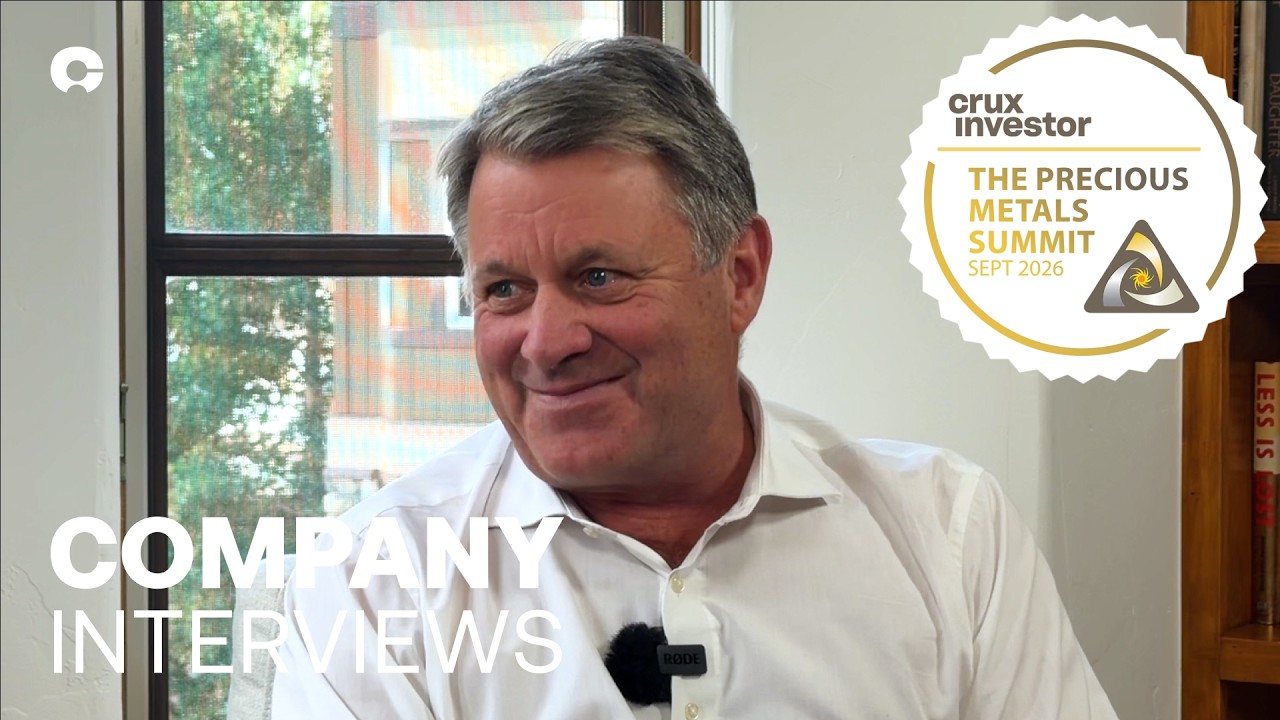
Interview with Darcy Marud, President and CEO of Western Exploration
Capital Structure & Strategy
Western is tightly held, with about 63.4 million shares outstanding and 85.6 million on a fully diluted basis according as of May 2026. Institutions own 52% and Agnico Eagle holds 10%. Marud said re-rating will depend on hitting the milestones the company has published.
When the company listed in 2022, it set a five-year target. By 2027 it aimed to have about 400,000 recoverable ounces permitted and ready for development at Doby George, and 1.5 million ounces of gold in a PEA at Gravel Creek. Marud said Doby George is close to that level and Gravel Creek has a clear path, although its resource is not yet there. He pointed to Glamis Gold's growth in the 1990s as the model:
"Start small, find an asset where you can develop a number of [mines] with a central [plant] around it and grow it into a bigger enterprise that you can ultimately grow from that."
How Doby George's cash flow would be used is still open. Marud said no decision has been made between dividends and reinvestment into resource growth. The board will choose whichever option delivers the most value to shareholders at the time.
The Investment Thesis for Western Exploration
- Doby George is a simple oxide heap leach project backed by more than 800 historical drill holes plus modern confirmation drilling and metallurgy, which lowers technical risk for a first mine.
- Initial capital of US$115.2 million is roughly matched by one year of operating cash flow at US$3,000-3,400/oz gold, which could make project financing more manageable for a small company.
- Gravel Creek adds high-grade, district-scale exploration upside on the same land package, with a potential processing route to on-site doré.
- The main risk is timing, because the USFS record of decision, state permits and a possible EIS all sit ahead of any construction decision.
- Funding is another risk, because the company's market capitalisation of about C$50 million is far below the US$115.2 million capital requirement, so dilution is likely.
- Investors should monitor Doby George infill drilling results due by the end of 2026, as they will test resource conversion ahead of the PFS.
- Investors should also watch USFS feedback on the Mine Plan of Operations and Gravel Creek metallurgical results due late in 2026, which are the next de-risking milestones.
Macro Thematic Analysis
Gold's strength over the past two years has changed the maths for small developers, with an all-time high of $5,549/oz in January 2026 and a 2026 year-to-date average of about $4,570/oz. Those levels sit well above the $3,000/oz base case used in the Doby George PEA. For projects with modest capital needs and short paybacks, higher prices have turned marginal-looking deposits into ones that can attract financing.
Investor preferences have moved during this period. Marud said that six months ago the market was rewarding companies de-risking assets towards production, while today it is rewarding drill results. Western is trying to offer both, with a development asset in permitting and a discovery still being drilled. Marud noted that the way shareholders judge value has changed over his career.
"When I got into this business, the value to the shareholders was ounces in the ground. It wasn't cash in the bank. It wasn't a dividend. They wanted to see resource growth."
Nevada adds to the appeal. The company is about three miles from a paved highway, and is close to power and water. The Elko region has one of North America's deepest mining workforces. Marud also said the current US administration wants to see projects developed. For generalist investors, a permitted, low-capital oxide mine in a tier-one US jurisdiction offers leverage to gold with less technical risk than a large sulphide project. The start-small approach Marud describes is familiar in Nevada. Liberty Gold's Black Pine is another oxide heap leach project in a similar setting, though on a larger scale. Whether Western's model works will depend less on the gold price than on permitting speed and financing terms.
TL;DR:
Western Exploration is advancing Doby George, a simple Nevada oxide heap leach project. Its 2025 PEA shows a US$211.2 million after-tax NPV and 62.2% IRR at US$3,000/oz gold on US$115.2 million of initial capital. The Mine Plan of Operations is with the US Forest Service, a PFS is planned for 2027, and the company is targeting a record of decision at the end of 2027 and first production in 2030. Eight kilometres away, the high-grade Gravel Creek discovery holds about 1 million gold-equivalent ounces and remains open. New metallurgy points to on-site doré production. Near-term catalysts are infill drilling results, USFS feedback and further Gravel Creek recovery work.
FAQ (AI-generated)
Analyst's Notes





Subscribe to Our Channel

Stay Informed