




EU Block on MMG Nickel Deal Deepens Europe’s Reliance on Indonesian Supply


Anglo American warns that an EU veto of its MMG nickel sale could close Brazilian ferronickel supply, pushing European stainless mills toward Indonesia.
- Anglo American was set to tell European Commission merger officials on 8 October 2026 that it would move its Brazilian ferronickel operations towards care and maintenance if the EU blocks the up to $500 million sale to MMG.
- The Commission is probing whether MMG, majority owned by state-owned China Minmetals, could divert ferronickel away from European stainless steel producers, and faces a 30 November deadline.
- Barro Alto and Codemin produced 18,200 tonnes of nickel in H1 2026, an annualized volume larger than the 32,000-tonne global deficit the INSG forecast for 2026.
- LME nickel stocks rose to 284,178 tonnes on 7 October from 255,282 tonnes on 2 January, which is why a closure threat has not lifted prices.
- An MMG remedy package accepted before 30 November removes the closure risk; a prohibition shifts European ferronickel sourcing towards Indonesian supply.
EU Merger Objection Puts Brazilian Ferronickel Supply on a Closure Path
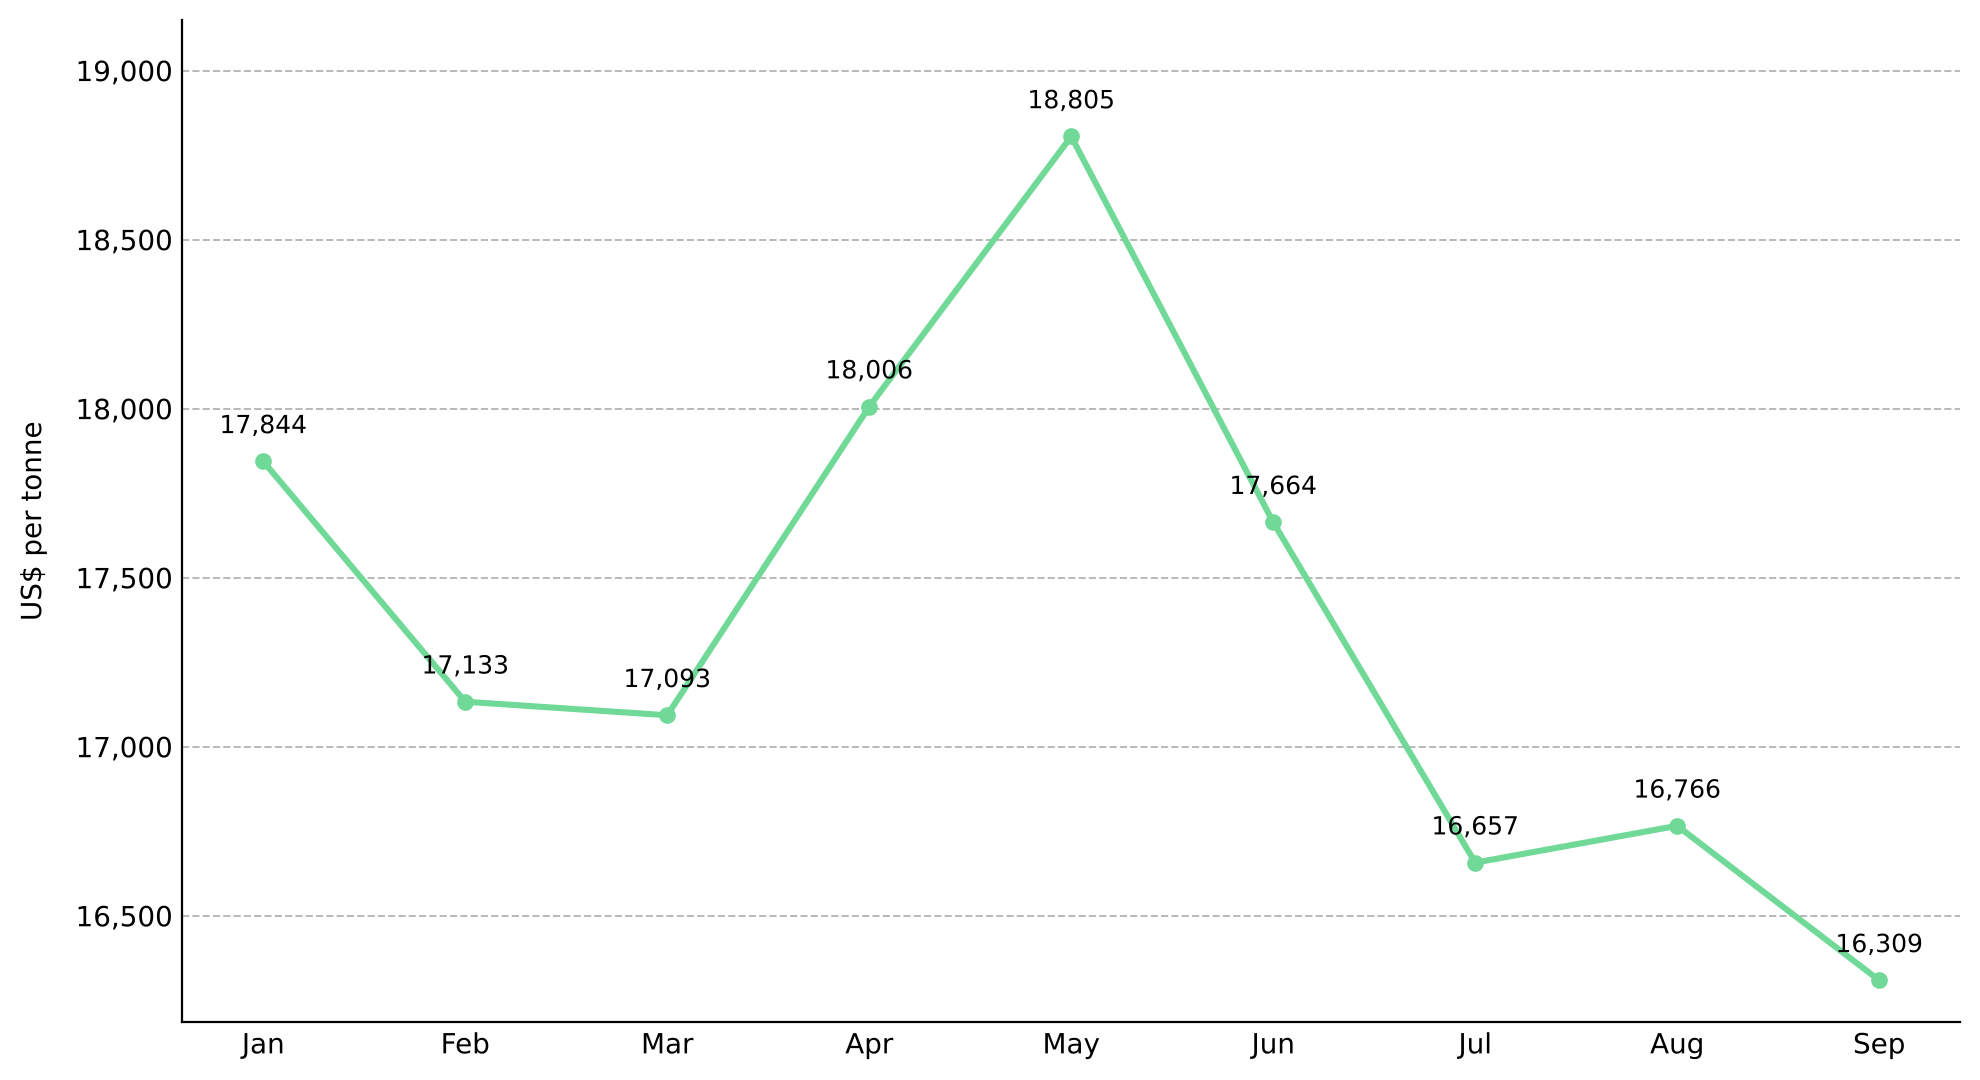
Anglo American was set to tell European Commission merger officials in Brussels on 8 October 2026 it would move its Brazilian nickel business towards closure if the EU vetoes the sale to MMG, a mining and metals company. Nickel showed no supply premium: the most-traded SHFE contract fell 1.00% to 121,830 yuan per tonne on October 8, according to SMM, and LME cash nickel settled at $15,645 per tonne on 7 October, 19.6% below its May 6 high (LME data via Westmetall).
China Diversion Concerns Narrow Ferronickel Buyers & Raise Closure Risk
Ferronickel is a nickel-iron alloy fed directly into stainless steel melt shops, so a Brazilian closure removes units from the European stainless supply chain rather than from LME-deliverable refined metal. The Commission opened an in-depth investigation in November 2025 and issued a statement of objections in September 2026, arguing MMG could redirect supply away from the bloc's stainless producers, Reuters reported.
The case comes amid broader EU concerns over dependence on China for critical minerals, Reuters reported, which puts Chinese state ownership at the center of the review. MMG Executive General Manager of Corporate Relations Troy Hey said the Commission relied on "selectively used two partial and misleading quotations from over 200,000 documents" and noted that Glencore and Trafigura had written to confirm confidence in continued supply, Reuters reported. Anglo American committed to exit nickel more than two years ago, which leaves no fallback bid if the sale fails.
High Exchange Stocks Keep Nickel Prices Flat Despite Ferronickel Closure Risk
According to preparatory notes seen by Dow Jones Newswires as reported by the WSJ, Anglo American Chief Operating Officer Ruben Fernandes was set to tell Commission officials MMG is the only credible buyer the company had found, and to set out what a prohibition would trigger:
"Given our commitment to exit our nickel business more than two years ago, we will have little option but to head towards 'care and maintenance' as the pathway to closure in the event that the Commission prohibits the sale to MMG."
If the EU clears the deal with conditions, which Reuters reported MMG may be prepared to offer in the coming weeks, the Brazilian operations keep running under new ownership. If the EU blocks it, the operations move to care and maintenance and European mills would likely turn to Indonesia, the largest producer per the INSG, for replacement supply, the opposite of the supply diversity the review aims to protect. Neither outcome is likely to move prices while LME stocks sit at 284,178 tonnes, near the top of their 2026 range.
The Commission has until 30 November to rule. The number to keep an eye on is LME nickel stocks, which the exchange publishes every day. If they drop below 255,282 tonnes, the level on 2 January, the deficit the INSG forecast for 2026 is finally showing up in warehouses, and losing the Brazilian supply would start to push prices up.
Ferronickel Supply Risk Shifts Margin Pressure to European Stainless Mills
The most exposed group is European stainless steel producers without their own nickel supply, which rely on bought-in ferronickel. A Brazilian closure forces them to re-tender feedstock while Indonesia weighs capacity utilization controls if oversupply continues, according to SMM on 8 October, adding policy risk to the replacement supply.
The distinguishing factor among European mills is feedstock flexibility: operations able to run higher stainless scrap or nickel pig iron ratios absorb a Brazilian closure at a lower cost than plants tied to ferronickel specifications. Retail holders of European stainless equities cannot see contract terms, which means the feedstock mix disclosed in annual reports is the closest available proxy, and an incomplete one.
The 30 November ruling is binary, and the Commission declined to comment, so no public signal shows which way it breaks. Position sizing in European stainless mills and nickel developers is the variable a holder controls; trading the deadline risks a loss on either outcome, since prices have not reflected a closure so far.
Supply Security Policy Lifts Non-Indonesian Nickel Value
A merger review built to protect European ferronickel supply now carries a credible risk of removing it. The seller has no alternative buyer, the asset has no stated standalone future, and exchange inventories mean the price will not reward anyone for the loss.
Value in the European stainless chain sits with whoever controls replacement units, and supply-security policy aimed at one Chinese-linked buyer deepens reliance on Indonesian supply. Low prices and a shrinking pool of acceptable buyers for non-Chinese nickel assets thin the pipeline outside Indonesia, raising the scarcity value of permitted Western ferronickel and sulfide projects once surplus inventory clears. Patient capital in non-Indonesian nickel units sits on the right side of a policy mismatch the market has not priced.
Analyst's Notes





Subscribe to Our Channel
Stay Informed


