Lower Bond Yields Support Gold Despite 30-Tonne Futures Cut


Lower bond yields provided support to gold despite reduced futures positions, while mine costs and resource quality shape projected returns.
- Lower bond yields provided some support to gold, which declined 0.1% for the week ending October 9 despite a 29.9-tonne reduction in COMEX managed-money net longs.
- Gold exchange-traded fund (ETF) inflows slowed during the week, while options traders became less bearish and Chinese investors increased their long positions, indicating mixed demand across markets.
- Higher assumed gold prices can improve projected mine returns, with a 2026 feasibility study showing after-tax net present value (NPV) rising from US$632 million to US$946 million across defined gold-price scenarios.
- Total gold supply remained broadly flat at approximately 1,269 tonnes in the second quarter of 2026 despite substantially higher gold prices, highlighting the importance of economically viable future supply.
- Rising industry costs make ore grade, metallurgical recovery, financing requirements, and mine design critical to determining whether elevated gold prices translate into viable mine economics.
Lower Bond Yields Help Limit Gold’s Weekly Decline
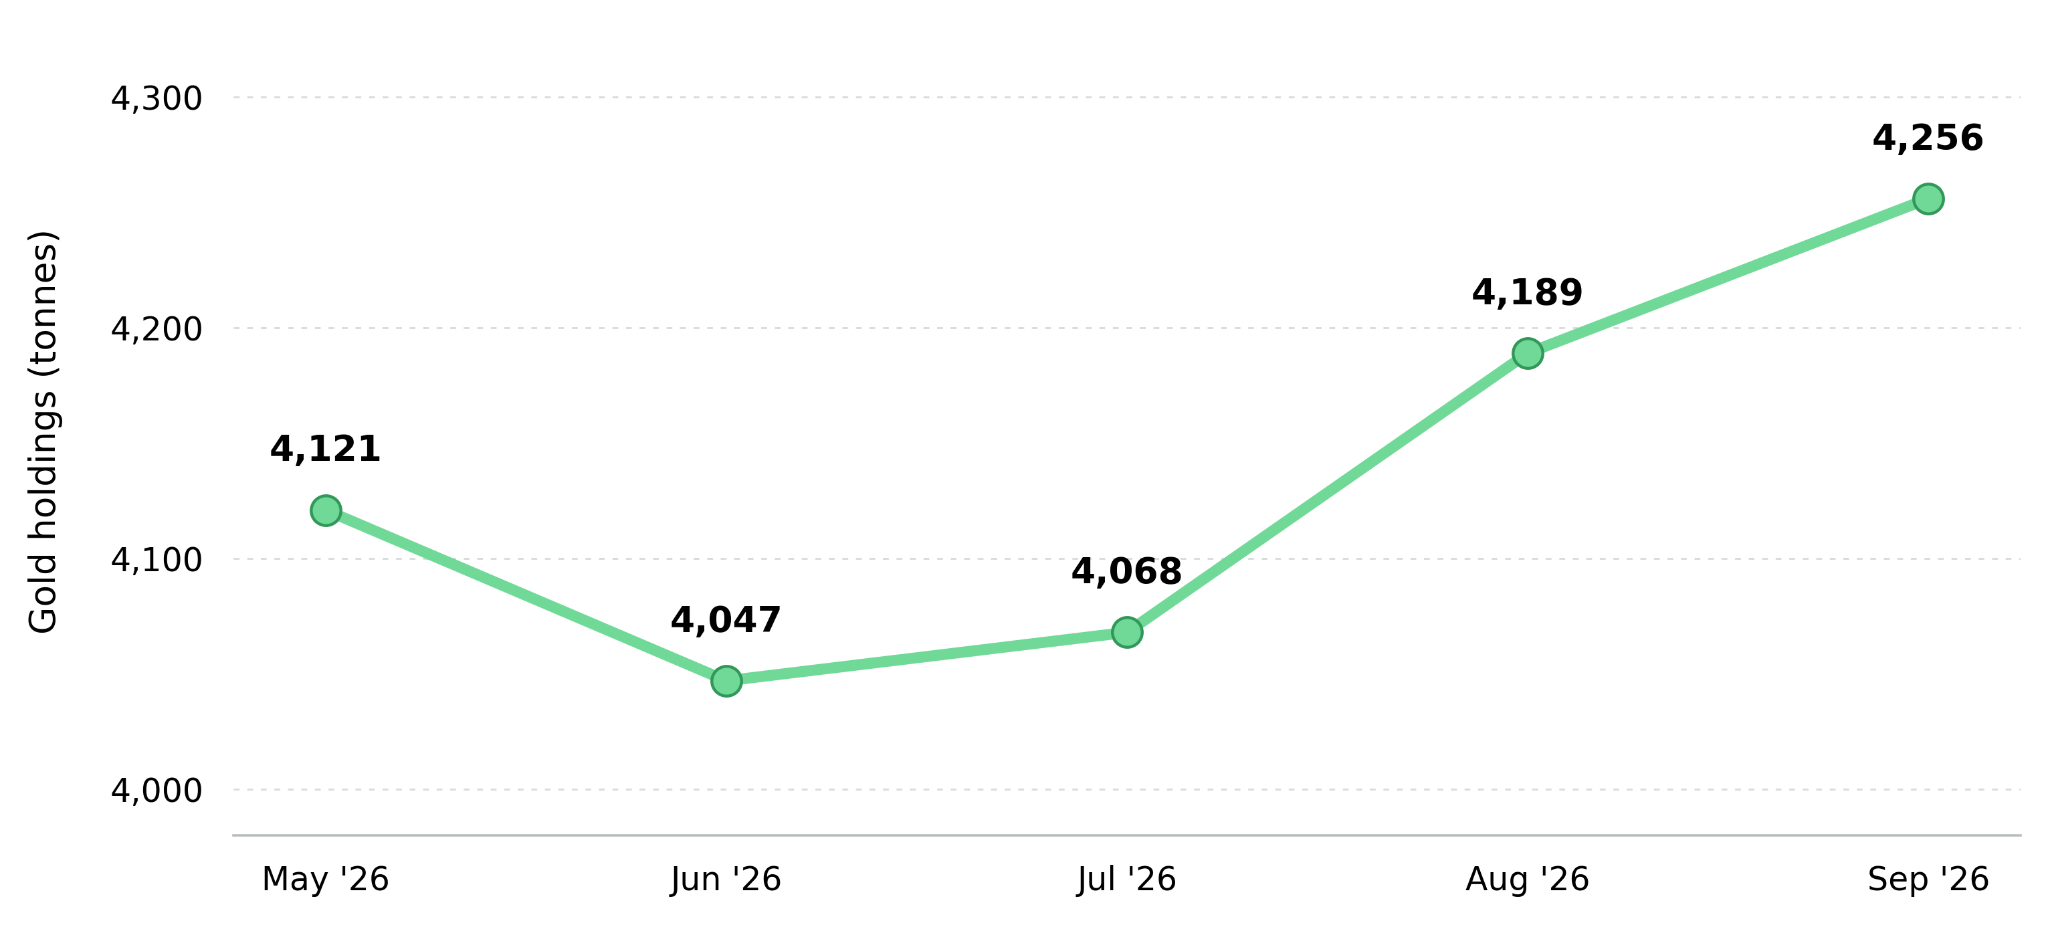
World Gold Council (WGC) reported that bond yields ended the week slightly lower, providing some support to gold despite slowing ETF inflows. The London Bullion Market Association (LBMA) Gold Price PM closed at US$4,186 per ounce on October 9, 2026, down 0.1% for the week. Meanwhile, COMEX managed-money net long positions declined 29.9 tonnes, from 387.0 tonnes on September 29 to 357.1 tonnes on October 6.
WGC reported mixed gold-market positioning during the week. Options traders became less bearish and Chinese investors increased their long positions following the Golden Week holiday, while global ETF inflows slowed and COMEX futures net longs declined. Gold prices reflect factors beyond COMEX futures positioning, while projected mine returns depend on longer-term price assumptions.
Higher Gold Price Assumptions Strengthen Projected Mine Returns
Lower bond yields provided some near-term support to gold, but projected mine returns depend on gold-price assumptions applied over longer periods. Gold averaged US$4,506.29 per ounce in the second quarter of 2026, up 37% year over year. Feasibility studies can quantify how different gold-price assumptions affect projected cash flows and returns for permitted projects advancing toward construction.
U.S. Gold Corp's fully permitted CK Gold Project in Wyoming recorded an after-tax net present value at a 5% discount rate (NPV5%) of US$632 million at US$3,250 per ounce gold in its March 2026 feasibility study, rising nearly 50% to US$946 million at US$4,000 per ounce. With an estimated 11-year mine life and US$394 million in initial capital requirements, the company is pursuing construction financing to advance the project toward production.
George Bee, President and Chief Executive Officer of U.S. Gold Corp., explains how gold prices affect projected project returns:
"We've got a very robust feasibility study published. This project makes a lot of money at a 3,250 gold price level, but at consensus pricing it pays back in about a year and a half."
Rising Mining Costs Increase the Need for Efficient Processing
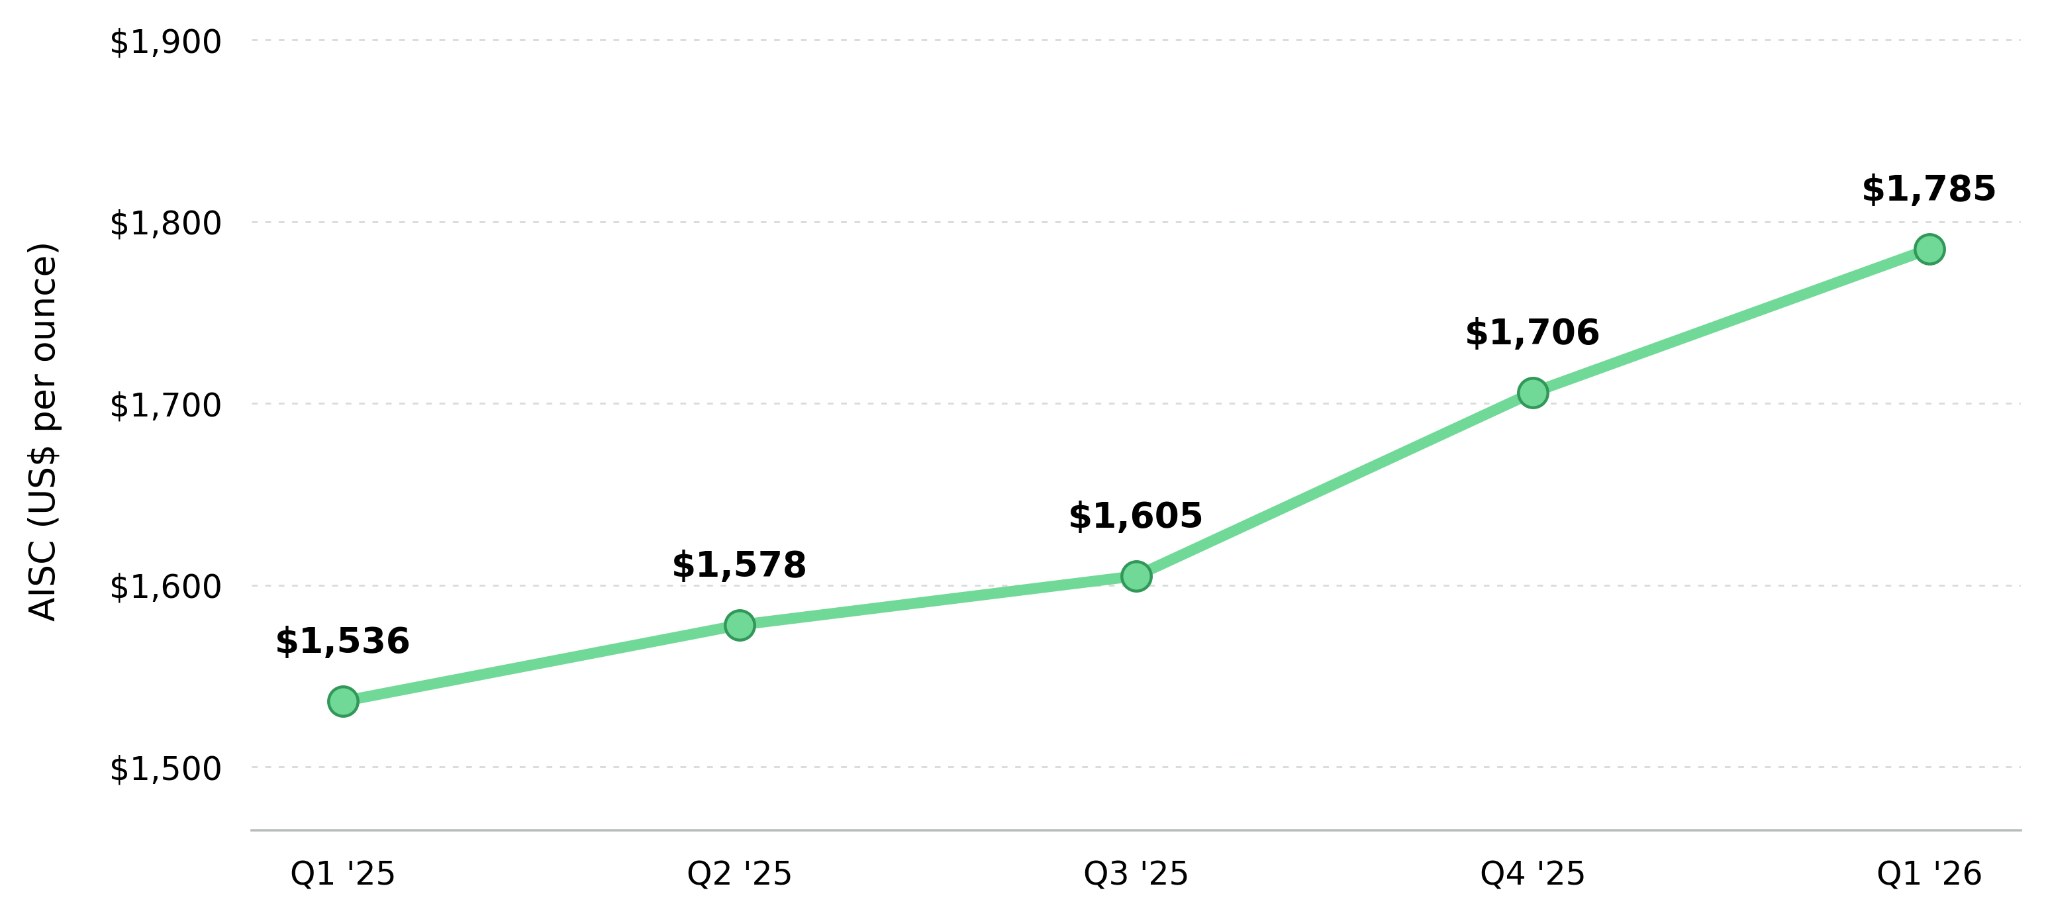
Higher gold prices have strengthened industry margins despite rising production costs. Global average all-in sustaining costs (AISC) reached US$1,785 per ounce in the first quarter of 2026, up 16% year over year, while AISC margins rose 134% to a record US$3,076 per ounce. Royalty payments also increased 85% year over year, accounting for 12% of average AISC, compared with 6% five years earlier. These rising costs highlight the potential cost advantages of heap-leach operations, which use simpler processing methods that can reduce operating expenses.
Cabral Gold has commenced gold production at its Cuiú Cuiú Mine in Brazil, completing sales of more than 2,400 ounces at an average net realized price exceeding US$4,200 per ounce. Both processing circuits now operate 24 hours a day as the company increases output toward its targeted commercial production milestone in the fourth quarter of 2026. These initial gold sales establish a revenue base while the company advances its production ramp-up and future expansion plans.
Alan Carter, President and Chief Executive Officer of Cabral Gold, explains how heap leaching supports lower production costs:
"This mine that we've built is a heap leach mine, so the all-in sustaining cost is expected to be around $1,200 an ounce, which is pretty low. We don't have to crush and grind this material to liberate the gold."
Slow Mine Supply Growth Highlights Higher-Grade Resource Potential
WGC reported that global gold mine production rose just 2% year over year to 965.6 tonnes in the second quarter of 2026, despite average gold prices increasing 37%. This modest supply response highlights the importance of developers with substantial gold resources, particularly those evaluating higher-grade mineralization to support economically viable future production.
Tudor Gold's latest drilling at its Treaty Creek Project in British Columbia extended gold mineralization approximately 480 meters downdip at the Perfectstorm Zone, expanding the project's potential resource base. Its Goldstorm Deposit contains 24.9 million ounces of indicated gold resources, with 5.8 million ounces identified under a higher US$125-per-tonne cut-off sensitivity. The ongoing preliminary economic assessment (PEA) is evaluating a higher-grade underground mining operation at Goldstorm, advancing the project's development plans toward a clearer assessment of future mine economics.
Joseph Ovsenek, President and Chief Executive Officer of Tudor Gold, explains how economic studies support future gold production:
“We currently have a preliminary economic assessment underway looking at an underground mine. The way we would approach it is to start with a higher-grade cut-off, recover our capital costs, and then lower the cut-off to bring more mineralized zones into the mine plan.”
Additional Mineralization Can Improve Future Mine Plans
Additional gold mineralization identified in areas previously classified as waste creates opportunities to reduce mining costs and improve future mine economics. Incorporating these discoveries into updated resource estimates and mine plans could support more efficient operations and stronger projected returns.
P2 Gold's latest drilling at its Gabbs Gold-Copper Project in Nevada extended the Sullivan Zone's gold mineralization, with all six drill holes confirming mineralization at depth. Two holes also identified gold-copper mineralization in an area previously classified as waste, potentially reducing mining costs and improving future mine economics. The results will help inform an updated mineral resource estimate targeted for the fourth quarter of 2026, followed by a feasibility study expected in the first quarter of 2027.
Flat Gold Supply Despite Elevated Prices Highlights Mine Economics
Total gold supply remained broadly flat year over year at approximately 1,269 tonnes in the second quarter of 2026, despite gold averaging US$4,506 per ounce and mine production rising 2% to 966 tonnes. Recycling declined 6% to 326 tonnes, while producer hedge books contracted by approximately 23 tonnes, offsetting additional mine output and limiting the overall supply response to higher gold prices.
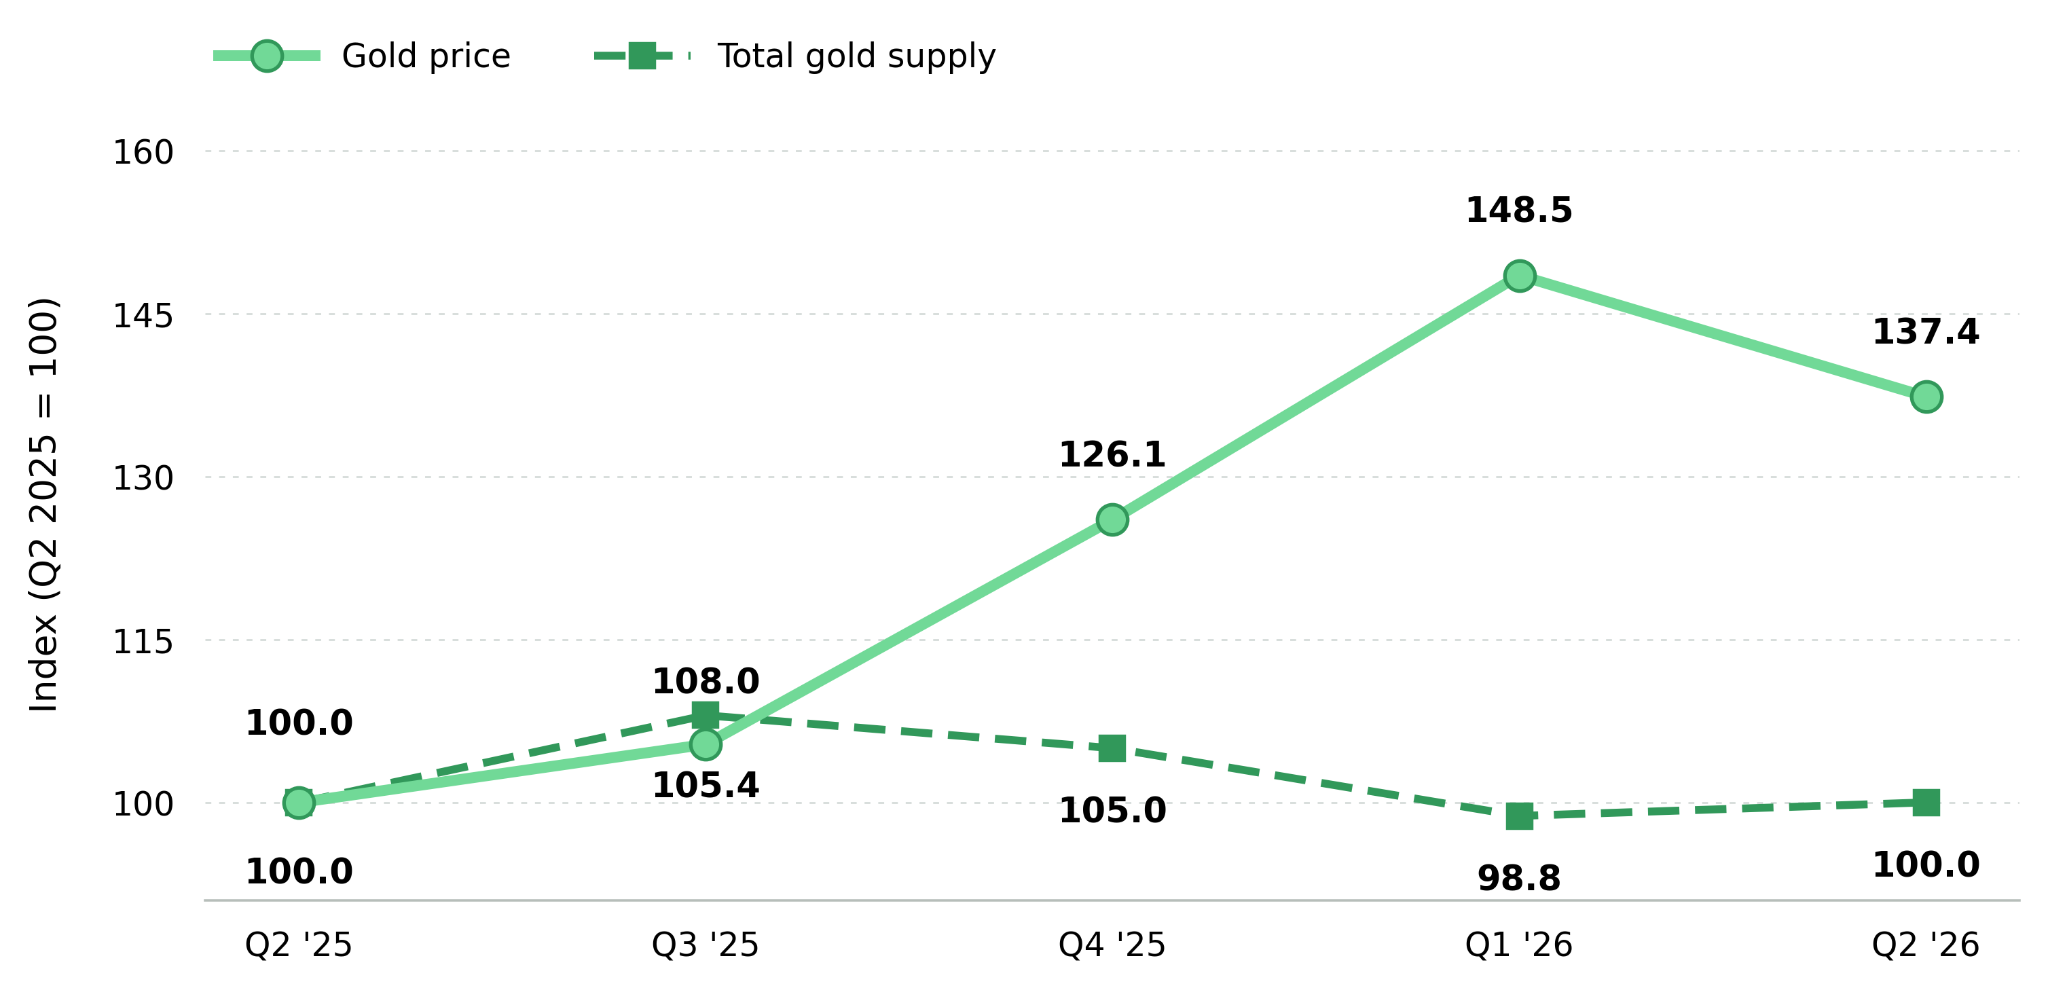
Gold-price movements influence potential mine revenues, while industry AISC of US$1,785 per ounce in the first quarter of 2026 highlights the importance of cost control. Resource quality, operating costs, and construction capital determine how favorable gold-price assumptions translate into projected mine returns and economically viable future production.
The Investment Thesis for Gold
- Lower bond yields can support gold prices in the near term, while long-term gold-price assumptions and project costs remain central to assessing future mine returns.
- Higher assumed gold prices can increase projected net present value and internal rate of return, strengthening the economic case for mine development.
- Industry AISC rose 16% year over year to US$1,785 per ounce in the first quarter of 2026, increasing the importance of cost control in protecting potential mine margins.
- Higher-grade gold resources and reduced waste removal can improve projected mine economics, increasing the importance of resource quality and mine design.
- Permitting progress, construction financing, and production milestones help assess whether gold projects can translate favorable prices into commercially viable production.
- Limited growth in total gold supply despite elevated prices highlights the importance of economically viable projects capable of contributing future production.
Lower bond yields provided some near-term support to gold despite reduced futures positioning, while longer-term mine returns depend on sustained gold-price assumptions and project economics. With total gold supply responding slowly to higher prices, resource quality, processing efficiency, and access to capital remain central to future production. Projects advancing through technical studies, financing, and production milestones offer opportunities to convert favorable gold prices into economically supported cash flows.
TL;DR
Lower bond yields provided some support to gold during the week ending October 9, limiting its decline to 0.1% despite a 29.9-tonne reduction in COMEX managed-money net longs. While weekly bond yields and market positioning influence short-term prices, projected mine returns depend on longer-term gold-price assumptions, operating costs, and capital requirements. Industry AISC rose 16% year over year in the first quarter of 2026, while total gold supply remained broadly flat despite elevated prices. These conditions highlight opportunities for gold projects advancing efficient processing methods, higher-grade resources, and economically viable future production.
FAQs (AI-Generated)
Analyst's Notes





Subscribe to Our Channel

Stay Informed