




Santacruz Silver: Bolivar Back on Track, Targeting Profitable Growth in 2027


Santacruz Silver’s Arturo Préstamo Elizondo targets 20% growth in profitable ounces for 2027 as Bolivar recovers and Zimapan investment pays off.
- Bolivar’s dewatering ran on time and on budget, and third-quarter silver output rose 19% to 408,087 oz, with two high-grade blocks targeted for the first quarter of 2027.
- Santacruz invested a little more than $15 million at Zimapan, targeting payback within 1.5 years and an 8% to 10% production increase, and silver recovery already rose from 72% to 76%.
- A policy of replacing at least 1.3 times mined tonnage gives the company prepared areas to bring into production if cost inflation squeezes margins.
- A dedicated 500 tpd mill for San Lucas is targeted to restore third-party volumes while freeing existing plants for the company’s own higher-margin ore.
- With around $130 million in treasury, Santacruz is reviewing accretive acquisitions and targeting at least 20% growth in profitable ounces in 2027.
Silver producers head into 2027 with lower prices than they saw earlier this year. Silver price fell from $84.39 per ounce (oz) in the first quarter of 2026 to $62.73/oz in the third quarter. Over the same period, the average zinc price rose from $3,243 per tonne (t) to $3,830/t. For a miner that drew 53.2% of first-half 2026 revenue from silver and 40.3% from zinc, the issue for next year is how much margin its mines can defend if operating costs keep climbing.
Santacruz Silver Mining Ltd. (TSX:SCZ) runs four producing mines across Bolivia and Mexico, plus the San Lucas ore-sourcing business. It also holds the Soracaya development asset in Bolivia. Executive Chairman and CEO Arturo Préstamo Elizondo said the company has spent 2026 preparing its operations to run efficiently in later years whatever metal prices do. He described himself as bullish on both silver and zinc. He also said he sees some cost inflation across the industry, with possibly more to come.
The company is targeting growth of at least 20% in 2027, measured in profitable ounces.
Bolivar Returns to Plan After the Flood
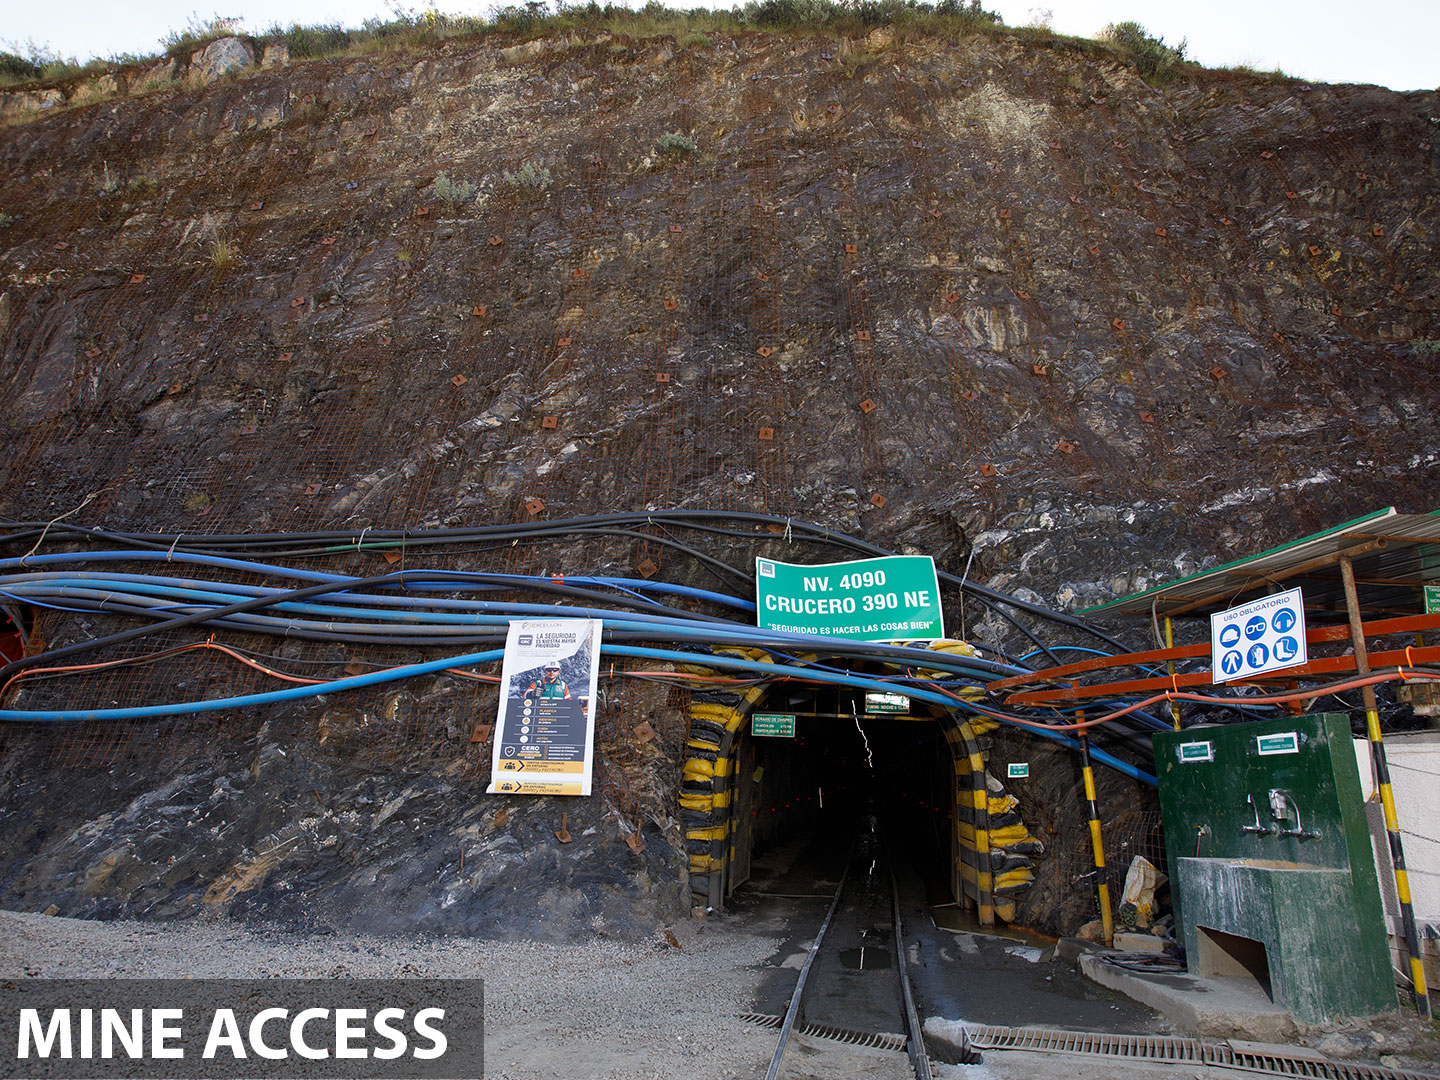
Bolivar, in Oruro, Bolivia, was hit by a water inflow in May 2025 that cut production sharply. Préstamo Elizondo said dewatering has run on time and on budget under the team led by Chief Operating Officer Eduardo Torrecillas. He said the mine is back on track in the fourth quarter. The company’s third-quarter 2026 production release targets full recovery of the flood-affected areas during the fourth quarter.
Third-quarter output already shows the recovery. Bolivar produced 408,087 oz of silver, up 19% from the second quarter and 209% from the third quarter of 2025. Silver head grade rose to 186 grams per tonne (g/t) from 165 g/t in the prior quarter. Throughput increased 6% as work moved into higher-grade areas affected by the flooding.
Préstamo Elizondo said the company has identified two high-grade silver blocks at Bolivar. They are targeted to enter production in the middle to late part of the first quarter of 2027. On that basis, he is targeting a mine that comes back stronger than it was before the flood.
Zimapan Investment Starts to Pay Off
Zimapan, in Hidalgo, Mexico, is a high-volume mine with the group’s largest mill, rated at 3,200 tonnes per day (tpd). Préstamo Elizondo said Santacruz invested a little more than $15 million there over the past 15 months, after encouraging results at level 960. He is targeting payback on that spending within no more than 1.5 years.
The programme works on grade, throughput and recovery at the same time. Préstamo Elizondo cited:
- higher silver and zinc head grades
- roughly 6,000 t of additional monthly mill throughput on a base of 74,000 t per month
- better mill recoveries
Together, he said, these are targeted to lift Zimapan production by around 8% to 10%. The third-quarter release shows early results on recoveries. Silver recovery at Zimapan improved from 72% to 76% quarter over quarter after enhancements at the processing facility. Silver output rose 3% on unchanged throughput.
The timing was deliberate. Préstamo Elizondo said the company chose to invest while Zimapan was generating strong cash flow, so that the mine would be ready for a period when margins narrow. With the main investment phase behind it, he said capital spending is now more controlled. He said the mine now has higher throughput, better head grades and better mill recoveries than before.
Interview with Arturo Préstamo Elizondo, Executive Chairman & CEO of Santacruz Silver
Inventory Policy Built for Margin Pressure
Préstamo Elizondo said Santacruz will soon file resource estimates across all of its mines, including a first-time report for Zimapan. He anticipates resources increasing, especially at Zimapan. He put Zimapan’s current mine life at more than 8 years and growing as drilling continues.
Each operation runs under an internal policy: the geology department must add at least 1.3 times the tonnage the mining department depletes. The company has met that target year over year, he said, and aims to hold at least 5 years of mine life ahead at each mine. When costs need to come down, it can slow exploration and other capital spending that does not compromise the mines. It does not cut infill drilling, which he described as part of day-to-day operations.
Executive Chairman and CEO of Santacruz, Arturo Préstamo Elizondo, explained how the mines are prepared for cost inflation:
“In our case, we’re always preparing our mines and having some areas that are ready to come into production at any given time. And the main idea is that if we see inflation or pressure coming into or squeezing margins, we always have areas that we can put into production that are already prepared.”
San Lucas Gets a Mill of Its Own
San Lucas buys ore from regional third-party miners and processes it through the company’s Bolivian plants. It pays a price set by metal content, so its margin does not depend on grade. In the third quarter, San Lucas milled 92,921 t, down 19% from the second quarter, and its silver output fell 24% to 314,451 oz. Préstamo Elizondo attributed the decline to the company’s own mines using more milling capacity, which pushed San Lucas ore out of the regular schedule. The production release also cites lower head grades in purchased ore.
Santacruz completed the acquisition of a 500 tpd mill in Bolivia, announced on September 18, 2026. The mill will process San Lucas ore exclusively. The company presentation lists a commissioning target in the fourth quarter of 2026 and commercial production by year-end. Préstamo Elizondo said the new mill will let San Lucas return to its normal production and grow by another 10% next year. It also frees capacity at the existing plants for the company’s own higher-margin ore.
Balance Sheet Discipline & the Acquisition Pipeline
First-half 2026 results show the earnings base behind the plan. Revenue reached $241 million, up 68% year on year, and adjusted EBITDA rose 64% to $89 million. The average realised silver price was $76.33/oz against an all-in sustaining cost (AISC) of $25.34/oz. The realised silver margin was $51.00/oz. Cash and highly liquid marketable securities stood at $73 million on June 30, 2026. Préstamo Elizondo said the company ended the third quarter with around $130 million in its treasury and has no debt, no streams or royalties attached to its assets.
He said Santacruz is reviewing acquisitions and has identified a few opportunities. He described them as companies with good projects that lack the balance sheet to advance them. Any deal would follow a conservative approach and must be accretive, as the company’s last 2 acquisitions were. Those were Zimapan in 2021 and the Bolivian assets bought from Glencore in 2022.
Préstamo Elizondo said Santacruz does not screen targets by geology. Underground narrow-vein mines need smaller equipment, crews skilled in repeated mining cycles, and development 3 times further ahead than in wider orebodies. He said the company takes a tailored approach at each mine. It treats the people running an asset as being as important as the asset itself.
The Investment Thesis for Santacruz Silver
- Bolivar’s dewatering has run on time and on budget, and two high-grade silver blocks are targeted to enter production in the first quarter of 2027.
- Zimapan received a little more than $15 million of investment over 15 months, with a targeted payback within 1.5 years and a targeted production increase of around 8% to 10%.
- A geology policy requiring at least 1.3 times depletion to be replaced gives the company prepared areas it can bring into production if cost inflation squeezes margins.
- A dedicated 500-tonne-per-day mill for San Lucas is targeted to restore third-party processing volumes while freeing existing plants for higher-margin company ore.
- Management reported a treasury of around $130 million at the end of the third quarter of 2026, with no debt, streams or royalties, to fund growth and potential acquisitions.
- The upcoming resource estimates, the first-quarter 2027 Bolivar ramp-up, Soracaya’s move into production and any acquisition announcement are the milestones to monitor against the target of at least 20% growth in profitable ounces.
Macro Thematic Analysis
The 2026 price path shows why mine-level efficiency counts for mid-tier silver and zinc producers. Silver averaged $84.39/oz on the LME in the first quarter and $62.73/oz in the third quarter. That fall pushes margin protection back to cost, grade and throughput. Santacruz still realised $76.33/oz in the first half against an AISC of $25.34/oz, but the trend through the year shows how quickly realised prices can move.
Zinc moved the other way, rising from $3,243/t in the first quarter to $3,830/t in the third. For a polymetallic producer, that offset softens the effect of a weaker silver price on revenue. It also lifts the value of zinc-weighted mines such as Porco, where zinc made up 66.4% of first-half revenue.
Cost inflation is the other variable. The CEO sees some inflation in the industry and possibly more to come. The company’s response is to invest during strong cash-flow periods and keep prepared ore areas in reserve. Préstamo Elizondo set out the governing principle:
“Even though we’re experiencing very good times metal price wise, we need to be very disciplined where we allocate the money and always have a payback on any investment that we’re doing.”
For a mid-tier producer with cash on hand, softer silver prices for less-capitalised peers also widen the pool of acquisition targets, which is the opportunity Préstamo Elizondo described.
TL;DR
Santacruz Silver is preparing its mines for narrower margins after silver averaged $62.73/oz in the third quarter of 2026, down from $84.39/oz in the first. Bolivar’s dewatering ran on time and on budget, third-quarter silver output rose 19%, and two high-grade blocks are targeted for early 2027. A little more than $15 million invested at Zimapan is targeted to pay back within 1.5 years and lift production 8% to 10%. A dedicated 500 tpd mill frees capacity for San Lucas. With around $130 million in treasury, management is targeting at least 20% growth in profitable ounces in 2027.
FAQs (AI-Generated)
Analyst's Notes





Subscribe to Our Channel


Stay Informed


