Integra Resources' Past-Producer Playbook: 7 Steps From Florida Canyon Cash Flow to a DeLamar Build


Florida Canyon cash flow, US$119.5 million in cash, and a financing advisor back the DeLamar build, with a permit decision targeted for 2027's second half.
A Mine-Building Sequence, Run a Second Time
Integra Resources Corp. (TSXV: ITR | NYSE American: ITRG) is repeating a sequence its leadership has already completed once: buy a past producer, rebuild the plan, put operators who have done it before in the seats, and let cash flow fund the next stage. The first run ended in 2017 with the sale of Integra Gold to Eldorado Gold for C$590 million. The second covers Florida Canyon in Nevada, DeLamar in Idaho, and Nevada North. Seven steps show where the sequence stands and what comes next.
1. The Model Starts With Past Producers Shut Down by Gold Prices
Management traces the model to Integra Gold, which acquired a past-producing project in Quebec that had closed because of the gold price, made a discovery, bought a mill out of bankruptcy, and sold the company to Eldorado Gold in 2017. Keeping the team together, the search moved to a similar asset: DeLamar, a former producer last operated by Kinross that had no resource when Integra acquired it. Resource delineation, economics, and permitting followed, and DeLamar now holds 1.9 million gold equivalent ounces in the proven and probable category. The second step in that sequence, the drilling and engineering that turn a closed mine into a defined resource, is the one both DeLamar and Florida Canyon have been through.
2. Florida Canyon's Rebuilt Mine Plan Adds 3 Years & 74% More Reserves
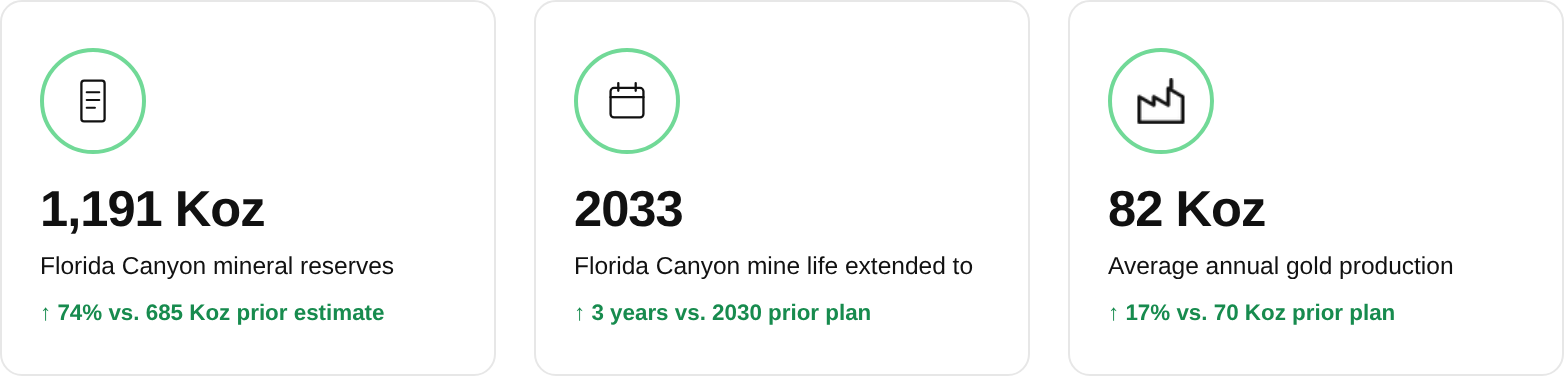
Integra acquired Florida Canyon in 2024 for US$68 million, with mine life running to 2030. The 2026 technical report lifted mineral reserves 74% to 1,191,000 ounces from 685,000 ounces, moved the end of mine life to 2033, and raised average annual gold production 17% to 82,000 ounces from 70,000 ounces. After-tax net present value at a 5% discount rate (NPV5%) is US$601 million in the base case, which steps from US$4,344 per ounce of gold in 2026 to US$3,600 per ounce from 2030 to 2035, and US$723 million at an assumed gold price of US$4,200 per ounce from mid-2026 to 2035. Integra reports that the mine passed its 3 millionth ounce of production in April. The base case projects about US$0.8 billion of after-tax free cash flow over the life of the mine, averaging about US$90 million a year.
3. Central Pit Access Is the Next Step at Florida Canyon
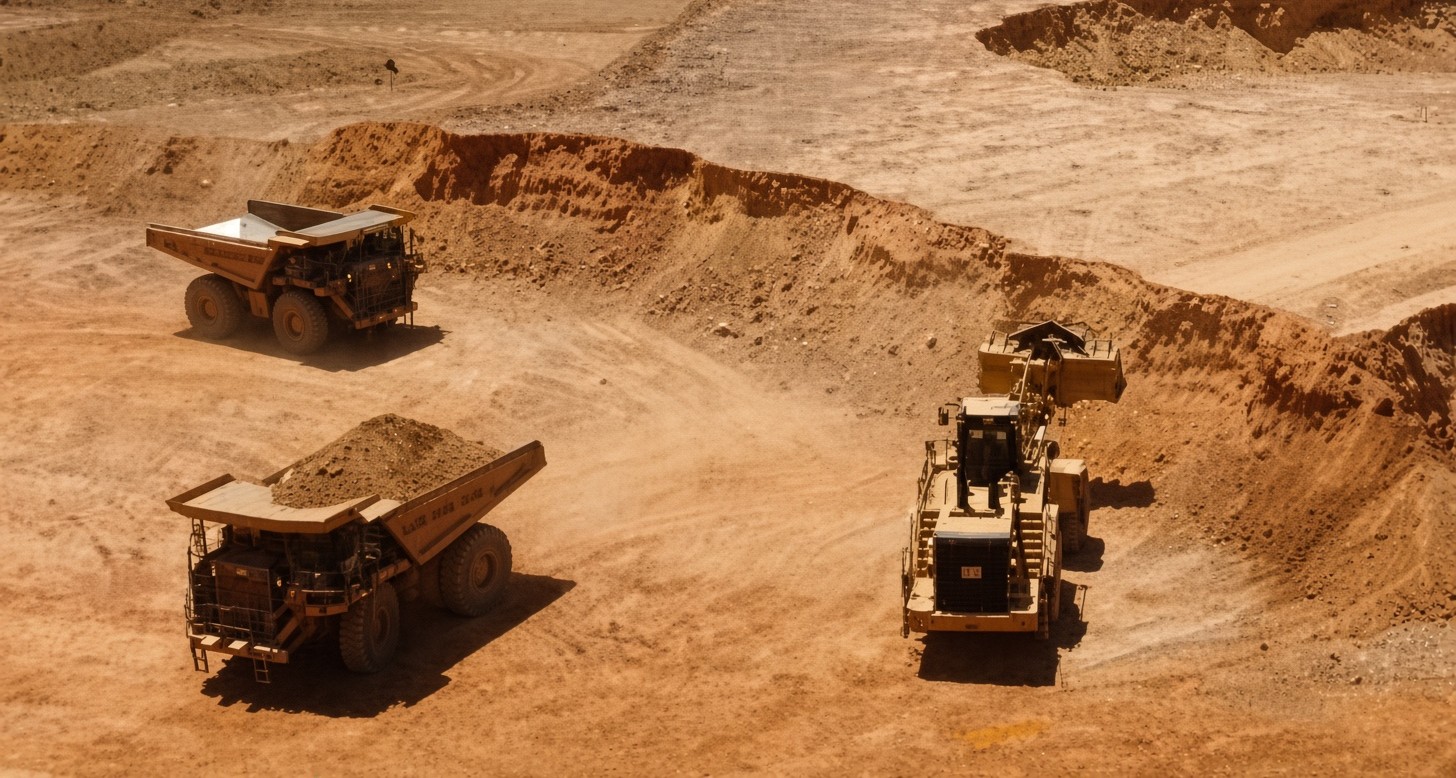
Florida Canyon's 2026 all-in sustaining costs (AISC) are guided at US$3,300 to US$3,500 per ounce sold, against a life-of-mine average of about US$2,331 per ounce. The 2026 level reflects more tonnes mined, stacked and processed to support production, higher royalties and excise taxes tied to stronger gold prices, and higher diesel and explosives costs. The company says its investment in Central Pit stripping, the heap leach pad expansion and the mobile fleet, which includes new mining equipment integrated over the previous two quarters, is also part of the 2026 cost level and sets up a longer mine life. Stripping at the Central Pit is scheduled for completion next year and opens access to higher-grade ore that Integra is targeting to lift production.
The 42,500-meter 2026 drilling program, with 31,364 meters completed, is targeting near-mine zones between the Radio Tower and Central pits and the northern extension of the Madre shear zone. The aim is to grow mineral resources and extend mine life in future studies.
4. Third Quarter Free Cash Flow of US$11.1 Million Backs the Investment Phase
Florida Canyon produced 17,652 ounces of gold in the third quarter, up 8% from the second quarter and 40% from the first quarter, and sold 16,760 ounces at an average realized price of US$4,272 per ounce. Revenue was US$72.4 million, mine operating earnings were US$23.3 million, and net earnings were US$12.9 million, or US$0.06 per share. Operating cash flow was US$21.8 million, and free cash flow was US$11.1 million for the quarter and US$23.5 million for the nine months. Cash costs averaged US$2,419 per ounce sold, within revised guidance, and mine-site AISC averaged US$3,059 per ounce sold, below revised guidance. Mining reached a record 97,428 tonnes per day.
Integra revised 2026 gold production guidance to 59,000 to 62,000 ounces from 70,000 to 75,000 ounces because leaching rates have not kept pace with the higher mining rates. Mining rates will be reduced for the rest of the year to maintain blending and long-term heap leach pad performance, which is intended to stabilize leach rates ahead of the move into higher-grade Central Pit ore in 2027.
5. The Management Bench Has Done Each Step Before
President and Chief Executive Officer George Salamis served as Executive Chair of Integra Gold when Eldorado Gold acquired it in 2017, and Chief Financial Officer Andrée St-Germain served as its Chief Financial Officer. Chief Operating Officer Clifford Lafleur and Vice President, Finance Sean Deissner both came from SilverCrest Metals, where each played a key role in the growth that led to Coeur Mining's US$1.7 billion acquisition. Vice President, Permitting Dale Kerner was instrumental at Perpetua Resources in securing the Stibnite Project's Final Record of Decision, the same federal approval DeLamar now needs. Vice President, Project Development Scott Guay held senior roles at Kinross overseeing global mining projects and the delivery of capital projects. Permitting and project delivery carry the most execution risk, and both are led by people with a proven track record.
6. DeLamar's Funding Plan Draws on Debt & Cash Flow
The 2025 feasibility study projects after-tax NPV5% of US$774 million in the base case and US$1.9 billion at recent metal prices of US$4,500 per ounce gold and US$65 per ounce silver, on initial capital of US$389 million. The after-tax internal rate of return is 46% in the base case and 97% at recent prices. The 10-year mine life averages about 106,000 gold equivalent ounces a year at a co-product mine-site AISC of US$1,480 per ounce of gold equivalent.
Integra plans to fund the build with about one-third cash flow and two-thirds debt, and GenCap Mining Advisory has been appointed to help evaluate and structure the financing alternatives. Cash and cash equivalents were US$119.5 million at September 30, 2026, up from US$63.1 million at December 31, 2025, supported by a US$57.5 million bought deal public offering completed in the first quarter of 2026 and free cash flow from Florida Canyon. The US$50 million spent at DeLamar across 2026 and 2027 comes off the US$389 million of initial capital.
7. Permit & Decision Gates Cluster in the Second Half of 2027
DeLamar entered the National Environmental Policy Act review process on May 29, 2026, when the Bureau of Land Management published the Notice of Intent, and the 30-day public scoping period concluded in June 2026. The permitting timeline posted to the FAST-41 project dashboard on January 13, 2026, shows a 15-month review schedule from start to finish. The Environmental Impact Statement and Record of Decision are targeted for the second half of 2027, with state permits advancing in parallel, and a Final Investment Decision is targeted for the same half.
At Nevada North, the Wildcat Exploration Plan of Operations is fully approved, and drilling that began in August 2026 is collecting hydrogeological, geotechnical, and metallurgical data for the Mine Plan of Operations. An updated technical report is targeted for 2027.
Key Takeaways for Investors
- Integra Gold took a past producer to a 2017 sale for C$590 million, and the same leadership now runs three assets in the Great Basin of the United States.
- Florida Canyon generated third-quarter free cash flow of US$11.1 million, and cash stood at US$119.5 million on September 30, 2026, against a mine plan that projects about US$90 million a year of average after-tax free cash flow in the base case.
- Third-quarter mine-site all-in sustaining costs of US$3,059 per ounce sold came in below revised guidance, and 2026 production guidance is 59,000 to 62,000 ounces ahead of access to higher-grade Central Pit ore in 2027.
- DeLamar needs US$389 million of initial capital, planned at about one-third cash flow and two-thirds debt, with a financing advisor appointed.
- The Record of Decision and the Final Investment Decision are both targeted for the second half of 2027.
Three milestones move the sequence from plan to execution: higher-grade Central Pit ore at Florida Canyon in 2027, the Record of Decision at DeLamar, and the debt financing that GenCap Mining Advisory has been appointed to structure. Together they advance the model the leadership ran once before, in which cash flow from a producing mine funds the next stage.
Analyst's Notes





Subscribe to Our Channel


Stay Informed