




Kodiak Copper Works Towards Closing the Valuation Gap with Fully Funded Shallow Drilling


Kodiak Copper (TSXV:KDK) drills shallow MPD zones ahead of a Q1 2027 resource update while valued at C$84 million against peers above C$1.5 billion.
- Kodiak's maiden MPD resource totals about 439 million tonnes, made up of 82.9 million tonnes indicated at 0.39% CuEq and 356.3 million tonnes inferred at 0.32% CuEq.
- The company is drilling 16,500 metres of shallow targets in 2026, with an updated resource estimate planned for the first quarter of 2027.
- The Kay Copper spin-out in Arizona has yet to close. Kodiak expects to hold 26.4% of the new company at a pro forma valuation of about C$18 million.
- Kodiak is fully financed for the 2026 programme and management expects to carry a cash cushion into the new year.
- Near-term catalysts include a steady flow of drill results, the Kay Copper close and the Q1 2027 resource update.
Copper is central to electrification and data-centre growth, and explorers in stable mining districts are attracting attention. Investors in porphyry projects focus on three things: scale, grade and a credible route to economics. Kodiak Copper Corp. (TSXV:KDK) is working to show all three at its MPD copper-gold project in southern British Columbia.
President and CEO Claudia Tornquist and Founder and Chairman Chris Taylor discussed the company's plan to grow its maiden resource of about 439 million tonnes. Kodiak is drilling 16,500 metres this year ahead of an updated estimate in the first quarter of 2027. Its market capitalisation is C$84 million, while more advanced porphyry peers are valued above C$1.5 billion.
The Valuation Question
The market's view, as put to management in the interview, is that MPD is large and likely to grow but low grade. Tornquist countered that the market received the December 2025 maiden resource well, because the project is already sizeable and its grades align with mines in the region and with other North American porphyry projects.
Kodiak cites reserve grades at neighbouring mines of 0.25% copper at Copper Mountain and 0.28% copper at Highland Valley. MPD's resource grades are 0.28% copper in the indicated category and 0.24% copper in the inferred category.
Tornquist named NorthIsle Copper and Gold, Faraday Copper and Osisko Metals as the more advanced peers Kodiak wants to emulate. Each was valued above C$1.5 billion as of 31 August 2026. She described NorthIsle's path as the model. It began with a modest valuation similar to Kodiak's and faced doubters over grade and permitting. Continued results and then a preliminary economic assessment (PEA) produced a further step up in valuation. Tornquist set out where Kodiak sits in that sequence.
"Our challenge and opportunity is to demonstrate to the market that MPD, our project, has what it takes to become what those guys already have. We have to and will grow our resource and then demonstrate and give confidence to the market that what we have has economic potential and can move forward successfully."
Resource Scale and Grade
The maiden resource covers seven deposits: Gate, Ketchan, Dillard, Man, West, Adit and South. Indicated resources total 82.9 million tonnes at 0.39% copper equivalent (CuEq). Inferred resources total 356.3 million tonnes at 0.32% CuEq. The estimate uses a 0.20% CuEq cut-off grade (CuEq combines copper, gold and silver). The calculation uses prices of US$4.20 per pound for copper, US$2,600 per ounce for gold and US$30 per ounce for silver.
Indicated resources contain 519 million pounds of copper and 0.39 million ounces of gold. Inferred resources contain 1,889 million pounds of copper and 1.28 million ounces of gold. Inferred material makes up about 81% of total tonnes. It carries a lower level of geological confidence than indicated material.
Interview with Claudia Tornquist, President & CEO, and Christopher Taylor, Chairman, of Kodiak Copper Corp.
Shallow Drilling and the Starter Pit
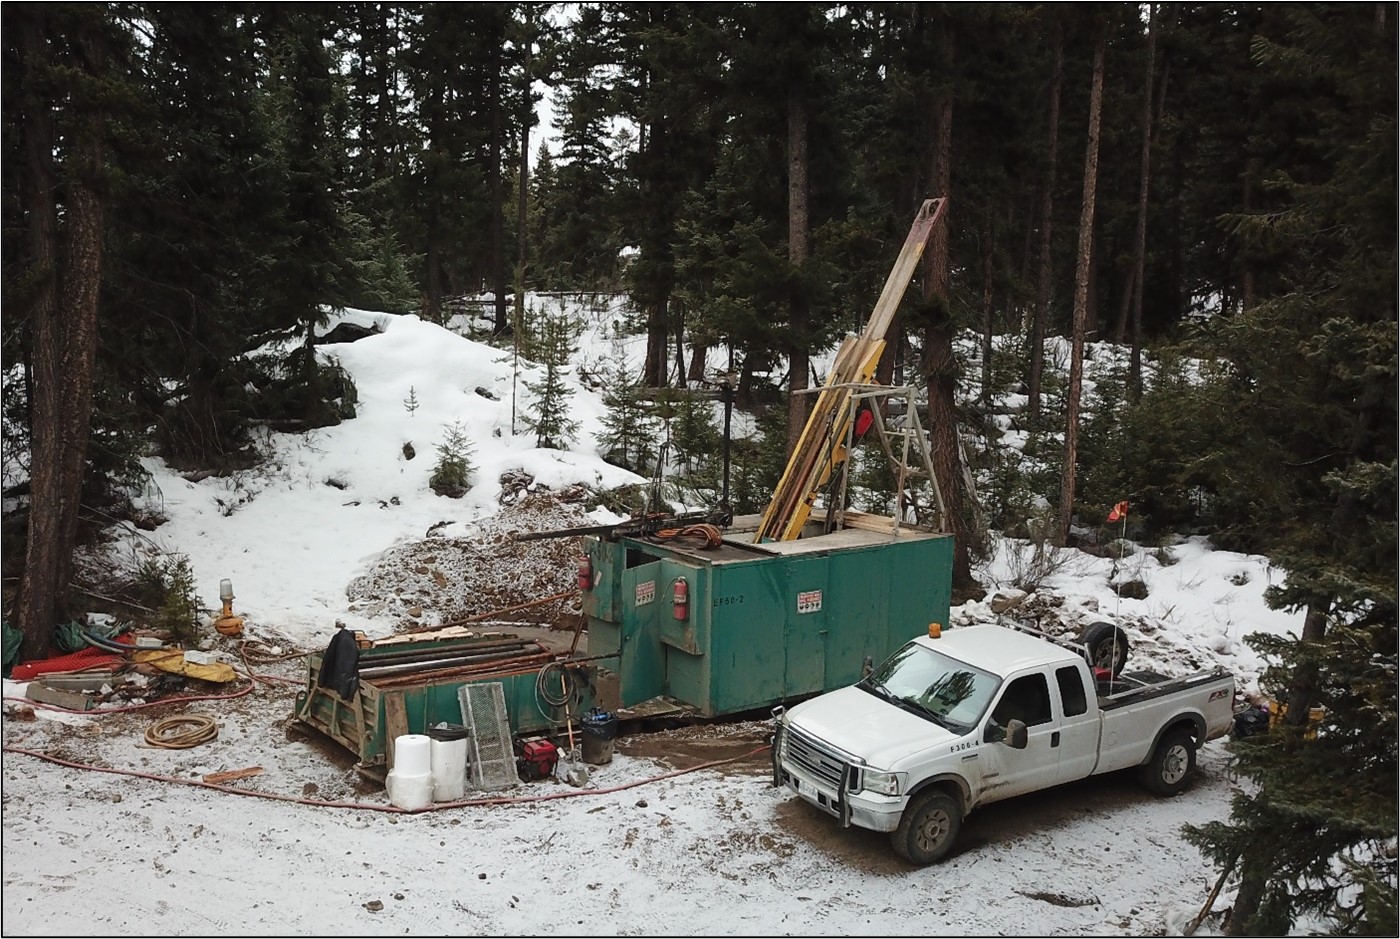
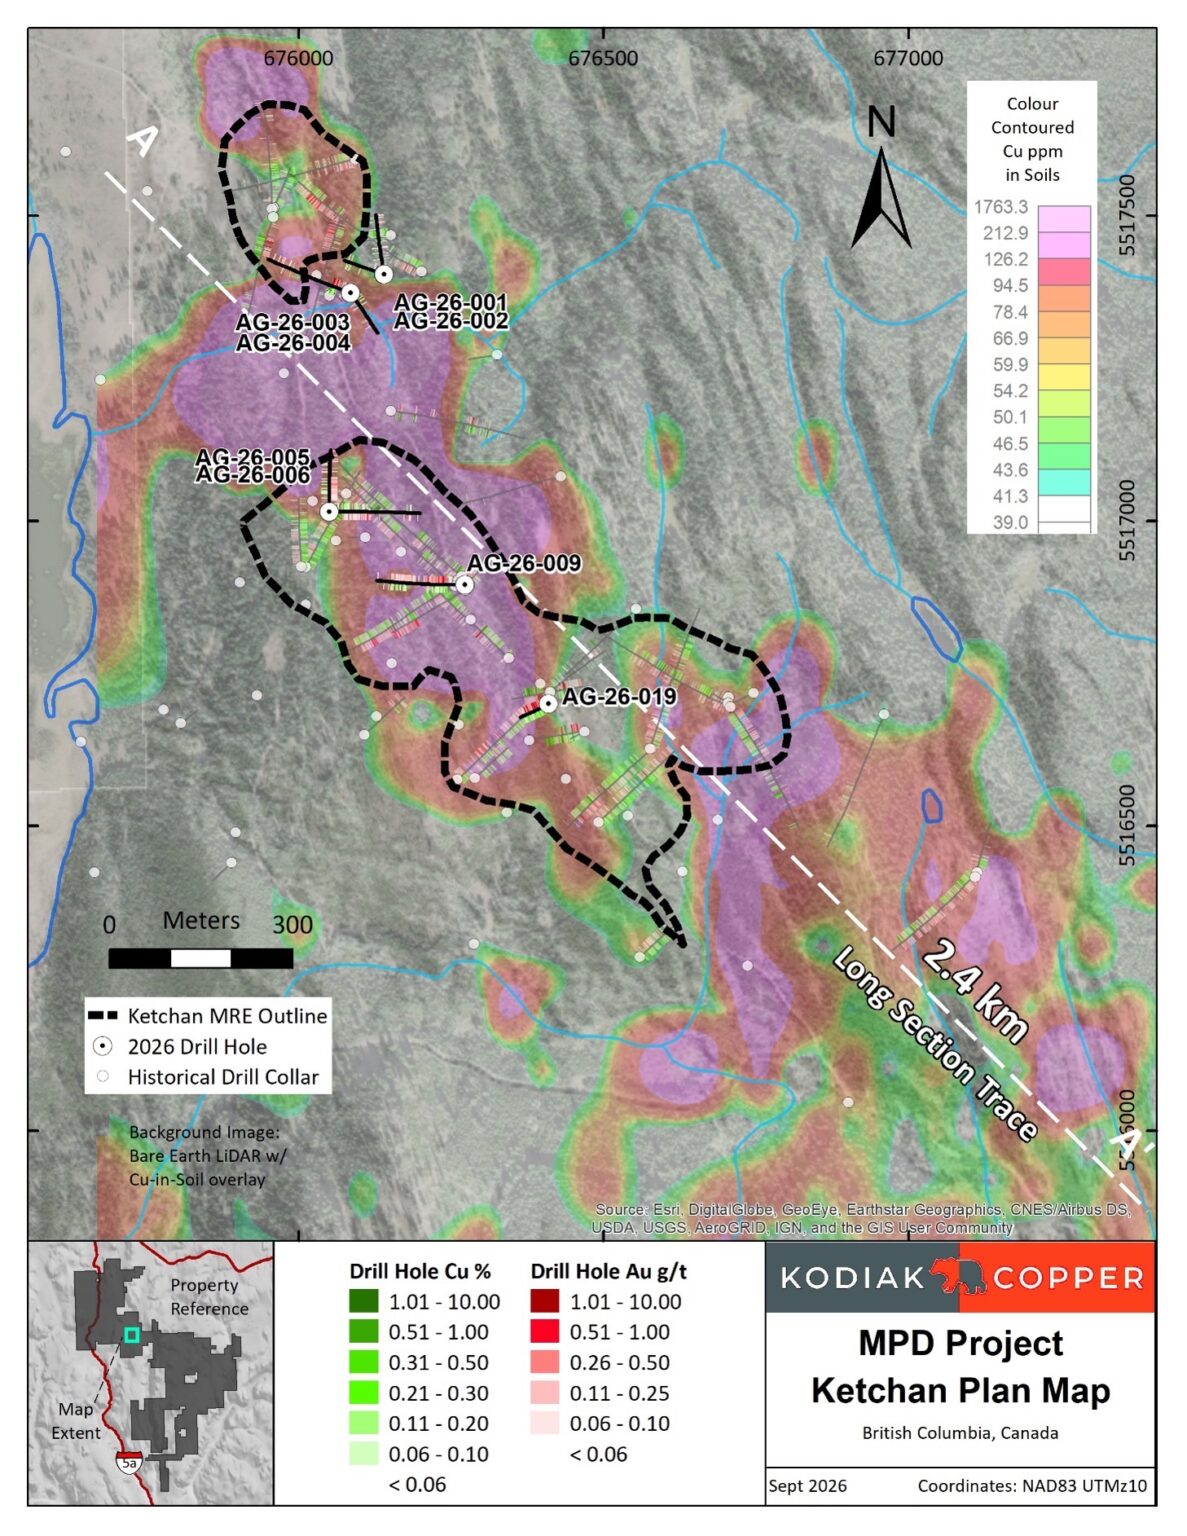
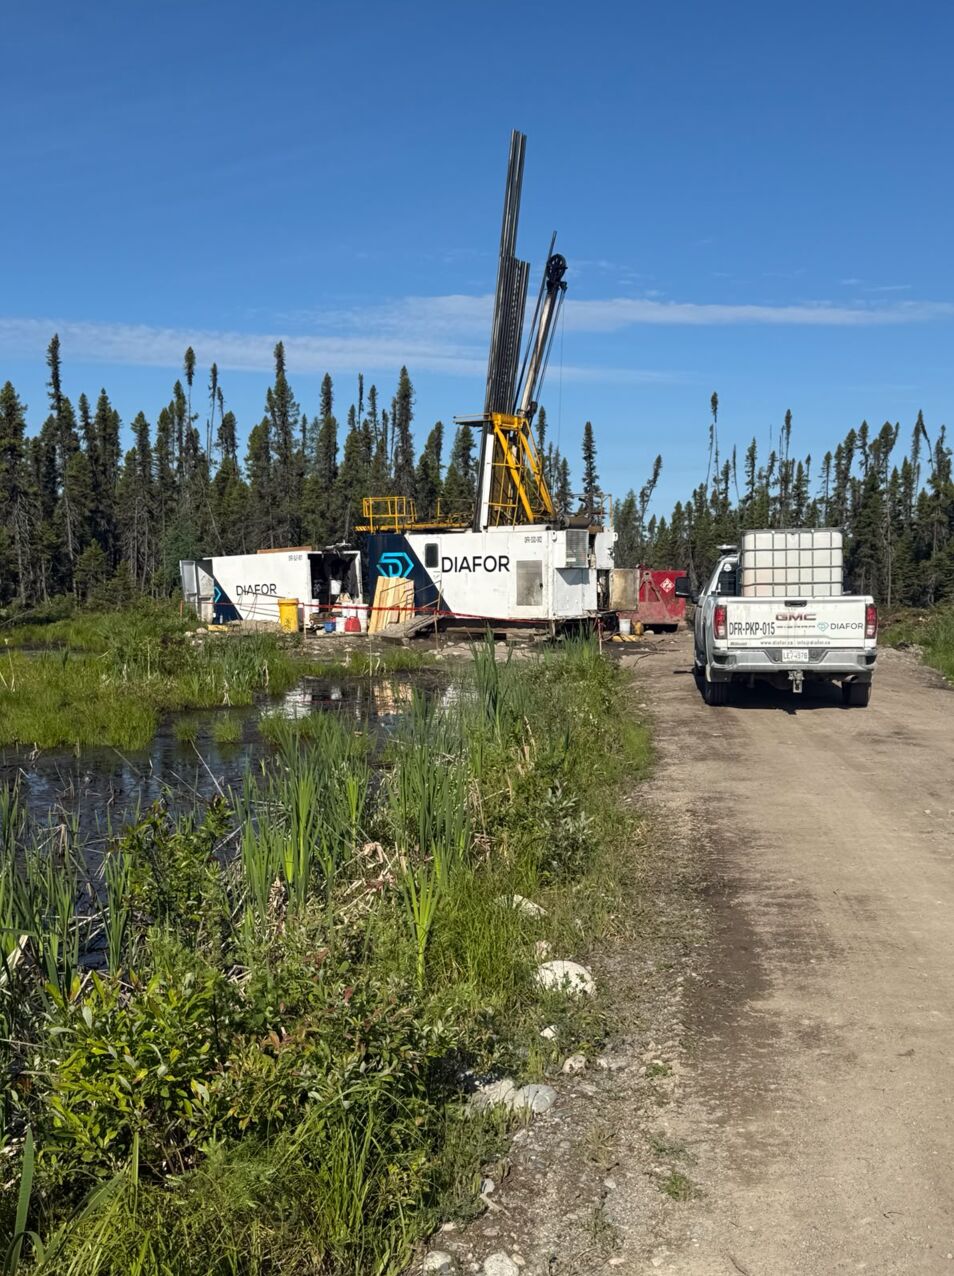
Kodiak plans 16,500 metres of drilling in 2026. More than 7,000 metres have been drilled at Ketchan, which is receiving the most metres. Tornquist said this is partly because Kodiak had not drilled the deposit before and the expansion targets were obvious.
The programme has produced what Tornquist called the highest-grade hole in the history of drilling at Ketchan. Kodiak reported that hole AG-26-019 returned 283.5 metres at 0.70% CuEq from 37.5 metres downhole, including 108 metres at 1.02% CuEq. Taylor said the hole tested a zone where management expected good grades, and the geological thesis proved correct. Every zone contains higher-grade areas, and understanding the geological controls lets the company target them.
All of this year's drilling is shallow, as the aim is to add near-surface mineralisation to the resource. Beyond the seven deposits, Kodiak has identified about 36 further targets across the 357-square-kilometre property, and management has also identified a new anomaly beside the South zone. Taylor suggested it could be a downdropped, fault-offset portion of that zone.
Tornquist said a mine's early economics depend on a starter pit. That needs near-surface, higher-grade mineralisation in enough volume to repay initial capital. She said the West and Adit deposits in the south of the property appear to have those characteristics. This year's programme aims to add more near-surface material. Management did not commit to a date for an economic study, and Taylor said discussing a mine plan is premature while drilling keeps expanding the zones.
Kay Copper Spin-Out Still to Close
Kodiak is combining its dormant Mohave porphyry copper project in Arizona with Teck Resources' Copper Hill project, also in Arizona. The new company is Kay Copper. Taylor said Mohave had sat in the portfolio for years because MPD discoveries took priority. He said the US move towards strategic and critical minerals made this the right time to act.
Adam Schatzker will be CEO. Kodiak expects to hold 26.4% of Kay Copper, which has initial funding of just over $5 million. Management put the pro forma valuation at about C$18 million (C$17.6 million in the company's presentation) and called it very conservative. Management said good exploration and drilling results could produce a significant re-rating, which could make the Kay Copper shares on Kodiak's balance sheet very valuable.
The plan is to work through a large data package from Teck first. Field work follows, then drilling. The transaction has not yet closed. Kodiak's September presentation lists completion in the third quarter of 2026, while the interview pointed to October.
Funding and Catalysts
Kodiak held C$18 million in cash as of 31 August 2026. Tornquist said the company is fully financed for this year's programme and expects to enter the new year with a cash cushion.
Tornquist listed the catalysts as a steady flow of drill results, completion of Kay Copper and the resource update. Eight holes have been disclosed so far, and she expects the update to show significant growth on the maiden estimate.
The Investment Thesis for Kodiak Copper
- Management sees room to close the valuation gap. Kodiak is valued at C$84 million, while NorthIsle, Faraday and Osisko Metals are each above C$1.5 billion.
- The main catalyst is a resource update planned for the first quarter of 2027. It will draw on this year's 16,500-metre programme, and management expects it to show significant growth.
- Drilling is focused on shallow mineralisation. All seven deposits remain open, and Ketchan has returned its best hole to date.
- A starter pit is the route to early economics. Management points to near-surface, higher-grade zones at West and Adit as the foundation for that case.
- Kay Copper offers separate optionality. Kodiak expects to hold 26.4% of a company with a pro forma valuation of about C$18 million, and the deal has yet to close.
- The company is funded through the 2026 programme, with C$18 million in cash at 31 August 2026.
- Considerations for investors: about 81% of the resource tonnage is inferred, no economic study has been scheduled and the Kay Copper deal has yet to close.
Macro Thematic Analysis: Scarce Discoveries Favour Established Districts
Kodiak's presentation cites the International Energy Agency as saying artificial intelligence and data-centre demand could add 5 million tonnes of copper demand by 2030. It also shows a May 2026 forecast from S&P Global. That forecast has the market in surplus through 2031 and in deficit from 2032. The projected shortfall reaches roughly 2 million tonnes by 2035.
Supply is the harder side of the equation. S&P Capital IQ data in the presentation shows 8.8 million tonnes of copper discovered from 2020 to 2025. That came from six discoveries above 0.5 million tonnes. The 1990s produced 705.3 million tonnes from 116 discoveries. Scarcity of that kind is the backdrop for Kodiak's focus on an established district.
According to the presentation, MPD has paved highway access, a network of logging roads, low-cost grid power and a local workforce in the nearby towns of Merritt and Princeton. Taylor, who has worked at the Mount Polley and Red Chris mines in the province, drew on that operating experience:
"I've seen the way that these deposits evolve. I've seen what the total long-term potential value is. And I can see something very parallel emerging with MPD right now. And so I would say that we will have a very good indication of where the project is going in the relatively near future."
That view underpins Kodiak's approach. The company is prioritising resource growth in the shallow zones rather than relying on a single high-grade find.
TL;DR
Kodiak Copper (TSXV:KDK) is drilling 16,500 metres at its MPD copper-gold project in British Columbia to grow a 439-million-tonne maiden resource. An updated estimate is planned for the first quarter of 2027. The company is valued at C$84 million, while more advanced porphyry peers exceed C$1.5 billion. Management says shallow, higher-grade zones at West and Adit could support a starter pit. The Kay Copper spin-out in Arizona is progressing but has yet to close. About 81% of the resource is inferred, and no economic study has been scheduled.
FAQs (AI Generated)
Analyst's Notes





Subscribe to Our Channel
Stay Informed


