Silver Crown Posts Record Quarterly Profit, Signs US$10M Colombian Silver Royalty


Silver Crown Royalties signs a US$10M El Bagre silver royalty after a record third-quarter profit, targeting 122,250 ounces of silver in 2027.
- Silver Crown reported third quarter royalty revenue of C$1.61 million, up 541% year on year, and net income of over C$379,000 as its second consecutive profitable quarter.
- The company signed a US$10 million agreement for a royalty on 90% of payable silver from Soma Gold’s producing El Bagre complex in Colombia, with 305,500 ounces of minimum deliveries before a 7.5% net smelter return royalty applies.
- Management targets attributable deliveries of 122,000+ ounces in 2027 and 159,000+ ounces in 2028, compared with 22,281 ounces in 2025.
- The shares trade at about 53 times trailing twelve-month sales, above the 25 to 35 times range for royalty peers under $1 billion in market capitalization.
- Near-term catalysts are the El Bagre first-tranche closing targeted by November 30, 2026 and the Madre Sierra restart targeted for 2027.
Silver Crown Royalties Inc. (CBOE:SCRI | OTCQX:SLCRF) reported its second consecutive profitable quarter and 2 days later signed a definitive agreement for a silver royalty on Soma Gold’s producing El Bagre complex in Colombia. The company reported attributable silver deliveries of 22,281 ounces in 2025 and targets of 122,250 ounces in 2027 and 159,250 ounces in 2028, with El Bagre’s contracted minimums of 30,000 ounces in 2027 and 60,000 ounces in 2028 included.
The deal follows a sharp correction in the silver price. Peter Bures, Chairman & CEO of Silver Crown Royalties said gold mine operators have become more willing to sell byproduct silver they had held back while prices were rising. The company creates silver royalties on byproduct ounces inside gold and copper mines and aims to build a dividend-paying company tied to silver.
El Bagre Adds a Third Producing Jurisdiction
Under the agreement dated October 31, 2026, Silver Crown will pay US$10 million in cash to Soma Gold Corp. for a royalty on 90% of payable silver from the El Bagre Gold Mining Complex in Antioquia, including the Cordero underground mine. Silver Crown receives the greater of 90% of payable silver and scheduled minimums of 5,500 ounces in 2026, 30,000 ounces in 2027 and 60,000 ounces a year from 2028 until 305,500 ounces are delivered, paid quarterly at the London Bullion Market Association silver price less 3%. The royalty then converts to a 7.5% net smelter return (NSR) royalty on silver for the life of the operation.
The company states the transaction is immediately accretive per share on attributable silver ounces and cash flow, and it is targeting increases in attributable silver ounce revenue in 2027 and 2028. El Bagre adds Colombia as a third producing jurisdiction alongside Peru and Brazil, and lifts the portfolio to 9 silver royalties across 7 projects on completion.
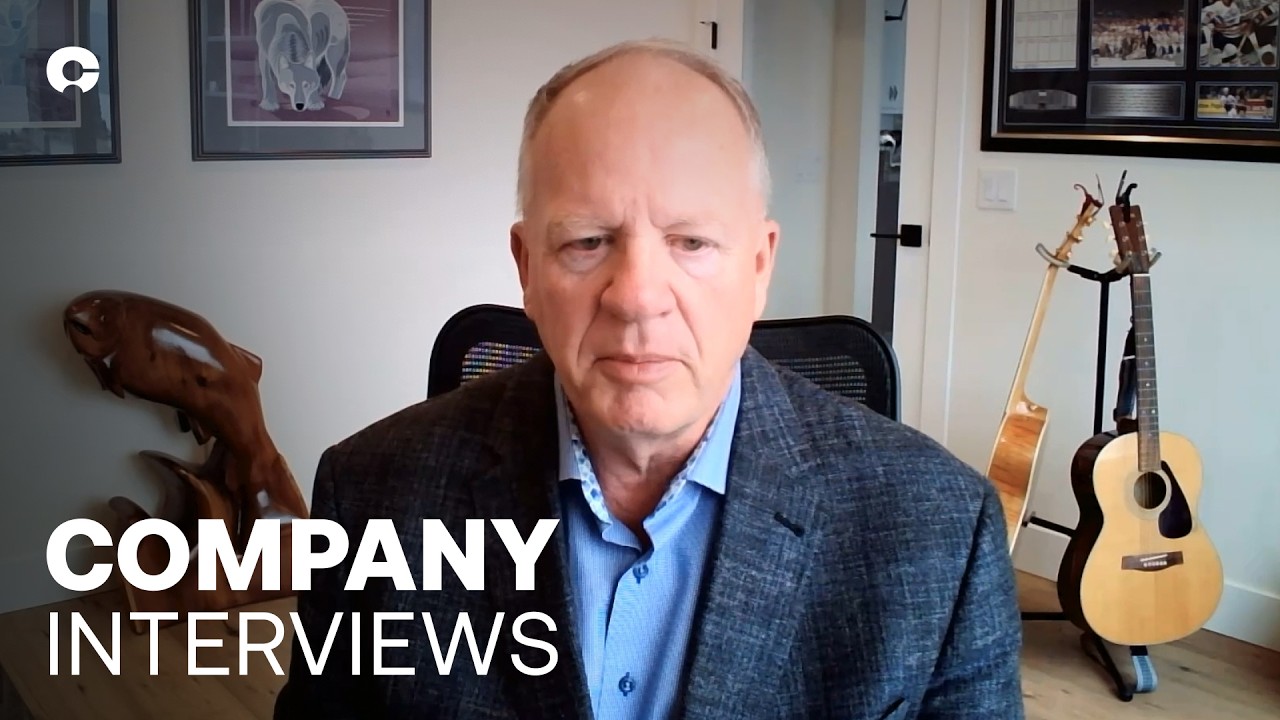
Chairman and Chief Executive Officer Peter Bures, explained why El Bagre fits the company’s current capital allocation:
“Right now the focus is on operating assets, and that’s where Soma Gold really fits the mold for us in terms of being immediately accretive to revenues and to cash flows. So being cash flow positive at this point, every new ounce that we add in terms of revenues flows straight to the bottom line.”
Bures described the economics as roughly US$10 million for just over 300,000 ounces delivered over 4 to 6 years, with the pace set by how quickly Soma ramps up production at the El Bagre mill.
US$10 Million in Two Tranches & First-Ranking Security
A first tranche of US$3 million, less a US$75,000 work fee already paid, is due at closing, targeted on or before November 30, 2026. The royalty is then granted at 30% of its full terms, and Soma’s obligations are guaranteed by its Colombian operating subsidiary, Operadora Minera S.A.S. The second tranche of US$7 million follows once Soma’s existing gold financier discharges its security over the El Bagre assets and first-ranking security is registered in Silver Crown’s favor. The royalty then rises to 100% of its terms.
Soma has agreed to use best efforts to complete that discharge by December 2026. If it does not, Silver Crown can require Soma to repurchase the royalty for US$3 million plus interest and the prior quarter’s royalty. Closing remains subject to Colombian security documents, legal opinions and Cboe Canada acceptance.
Bures said that collateral during the minimum-payment period is a condition of deploying capital at the front end. Earlier deals now serve as templates. The Pilar Gold royalty in Brazil covered silver absent from the operator’s reported estimates, and because not all of Soma’s silver is reported, Silver Crown applied the same structure at El Bagre.
Interview with Peter Bures, Chairman & CEO of Silver Crown Royalties
Third Quarter Results Mark a Second Profitable Quarter
Third quarter royalty revenue reached C$1.61 million, up 541% from last year. Revenue fell 14% from the second quarter’s C$1.87 million on a lower average silver price, while attributable deliveries held at 18,063 ounces, up 288% year on year. Net income was C$379,110, or C$0.07 per basic share, after C$138,000 in the second quarter.
At quarter end, Silver Crown held C$7.72 million in cash and term deposits, working capital of C$15.49 million and no debt, after C$13.84 million in warrant exercises over 9 months. Bures said cash flow was positive in both the second and third quarters, and that El Bagre, PPX and Titiminas should leave the company with healthy positive cash flow in 2027.
Silver Crown currently receives payments from 2 royalties. PPX Mining’s Igor 4 project in northeastern Peru has produced for about 7 years and is adding an on-site concentrator, with the royalty covering 15% of silver or 14,062.5 ounces per quarter until 225,000 ounces are delivered. Pilar Gold’s PGDM complex in Brazil restarted production a few weeks before the interview. Bures put the current annualized run rate at about 75,000 ounces.
Contracted Growth to 2028 & the Restart Pipeline
Deliveries rose from 4,341 ounces in 2023 to 22,281 ounces in 2025. With El Bagre, management targets 65,487 ounces in 2026, 122,250 ounces in 2027 and 159,250 ounces in 2028, against 92,250 ounces and 99,250 ounces for 2027 and 2028 without it. Bures cited about 130,000 ounces next year, including a contribution from Titiminas Silver, and 160,000 ounces the year after.
Silver Crown holds 3 separate 1% NSR royalties on Titiminas’ past-producing Madre Sierra deposit in Jauja, central Peru, the third completed effective September 15, 2026 for US$2 million in cash, US$1 million in units and up to US$1 million in further units tied to sustained production. Titiminas is targeting a 2027 restart and 2.5 million to 3.5 million silver-equivalent ounces a year by 2029. Bures said 3% of that range is about 100,000 ounces and that 25,000 to 30,000 ounces is plausible at the small-scale permit stage. He intends to renegotiate the polymetallic royalty into a silver-only royalty once the mine is producing.
Management’s figures exclude 2 restart assets. A new operator acquired Elk Gold in British Columbia through receivership in 2025 and has agreed to pay outstanding royalties by June 30, 2027, but Bures assigns Elk zero probability in his forecasts. Elk carries 6,000 ounces a year of minimums, less than 10% of the current run rate. EDM Resources’ Scotia mine in Nova Scotia may come online in 2028 and is also excluded.
Valuation & Access to Capital
Silver Crown trades at about 53 times trailing twelve-month sales and 38 times annualized third quarter sales on a C$243 million market capitalization, while peers under $1 billion trade at 25 to 35 times trailing sales. Bures, who described the company as a nano-cap on a global scale, argued that the multiple lags contracted growth.
The company reported a 478% share price gain over the 12 months to October 2026. Bures said the company was valued at C$20 million to C$25 million a year ago, and at its current size smaller institutions can write checks of US$3 million to US$5 million. Silver Crown raised C$3 million with Strategic Advisor Michael Gentile in January 2026 and a further C$4 million from strategic investors.
Third quarter revenue fell 14% on the silver price alone. The second El Bagre tranche depends on a third-party financier releasing its security. The BacTech Environmental royalty has been fully impaired pending financing and plant start-up, and Elk deliveries have run below minimums since mining stopped in 2025.
The Investment Thesis for Silver Crown Royalties
- Silver Crown has reported net income in 2 consecutive quarters and holds C$7.72 million in cash and term deposits with no debt.
- The El Bagre royalty adds a producing mine with contracted minimum deliveries of 305,500 ounces over approximately 5.5 years, followed by a 7.5% net smelter return royalty for the life of the operation.
- Management targets deliveries of 122,250 ounces in 2027 and 159,250 ounces in 2028, up from 22,281 ounces in 2025.
- The shares trade at about 53 times trailing twelve-month sales, above the 25 to 35 times range for peers under $1 billion in market capitalization.
- Monitor closing of the first El Bagre tranche by November 30, 2026 and the security discharge targeted by December 31, 2026.
- Monitor the Madre Sierra restart that Titiminas Silver is targeting for 2027.
Silver Crown offers growing contracted silver exposure through operating mines, with El Bagre closing conditions and the Madre Sierra restart as the next 2 tests of its forecast.
Macro Thematic Analysis
Silver’s retreat has changed the negotiating position between royalty buyers and gold producers. During the rally, operators had little reason to sell byproduct silver worth roughly 0.5% to 1% of their revenue, according to Bures, because they were waiting for a higher price. Bures described how the correction shifted that calculation:
“Now that silver has come down from $120/oz to $50/oz, they’re not exactly thinking that it’s going back to $200/oz anytime soon. So they’re a lot more amenable to parting with that silver component because it is inconsequential in the grand scheme of things to them.”
A lower spot price cuts Silver Crown’s current revenue but improves entry terms on new deals. The company prices acquisitions on a trailing 12-month silver price, and Bures said it targets a 25% internal rate of return (IRR) across the portfolio and declines transactions that fall short.
Bures said some smaller producers have seen their share prices halve from January highs. Royalties with minimum deliveries protect holders from operating shortfalls at the asset level, although they still depend on the operator’s credit.
Silver’s industrial role adds a second demand driver, with more than half of annual demand coming from uses such as electronics and solar panels. Bures warned that the cycle can turn, noting that silver could halve again or the Nasdaq could keep falling, and either would tighten capital for every company in the space. His argument is that Silver Crown’s cost of capital is currently lower than that of smaller producers, which lets it keep buying while counterparties are willing to sell.
TL;DR
Silver Crown Royalties posted its second straight profitable quarter, with third quarter revenue of C$1.61 million and net income of C$379,110, then signed a US$10 million agreement for a royalty on 90% of payable silver from Soma Gold’s producing El Bagre complex in Colombia. The deal carries minimum deliveries of 305,500 ounces over about 5.5 years before converting to a 7.5% net smelter return royalty. Management targets 122,250 ounces in 2027 and 159,250 ounces in 2028, up from 22,281 ounces in 2025. Closing of the first US$3 million tranche is targeted by November 30, 2026. The shares trade at about 53 times trailing sales against 25 to 35 times for smaller peers.
FAQs (AI-Generated)
Analyst's Notes





Subscribe to Our Channel

Stay Informed