




Stonegate Sets C$1.04 Fitzroy Target on Buen Retiro, Ahead of a Resource


Stonegate set a C$1.04 target on Fitzroy Minerals before any resource or study exists. How it values Buen Retiro and what has to be proven next.
At a Glance
Stonegate Capital Partners initiated coverage of Fitzroy Minerals in a report dated October 5, 2026, without a rating. Its case is Buen Retiro, a past-producing copper property in Chile that management is targeting for heap-leach production in 2028. Stonegate averages a net asset value build (C$1.11 per share) and an enterprise value per contained tonne check (C$0.96), arriving at a C$1.04 price target, against the current C$0.45 share price in the report. The target is ahead of a compliant resource and any economic study, and the tonnage behind it is Stonegate's own conceptual estimate.
What Stonegate Thinks Fitzroy Is
Stonegate describes Fitzroy Minerals Inc. (TSXV: FTZ | OTCQX: FTZFF) as a copper-focused exploration and development company in Chile, with its capital concentrated on 2 of 5 projects. Buen Retiro, 40 minutes south of Copiapó in a district anchored by Candelaria, is the flagship and the principal driver of the investment case. Caballos, in the Valparaiso region, is the higher-variance discovery option, and Stonegate calls it additive upside rather than necessary to the base case.
The Buen Retiro Plan Stonegate Is Underwriting
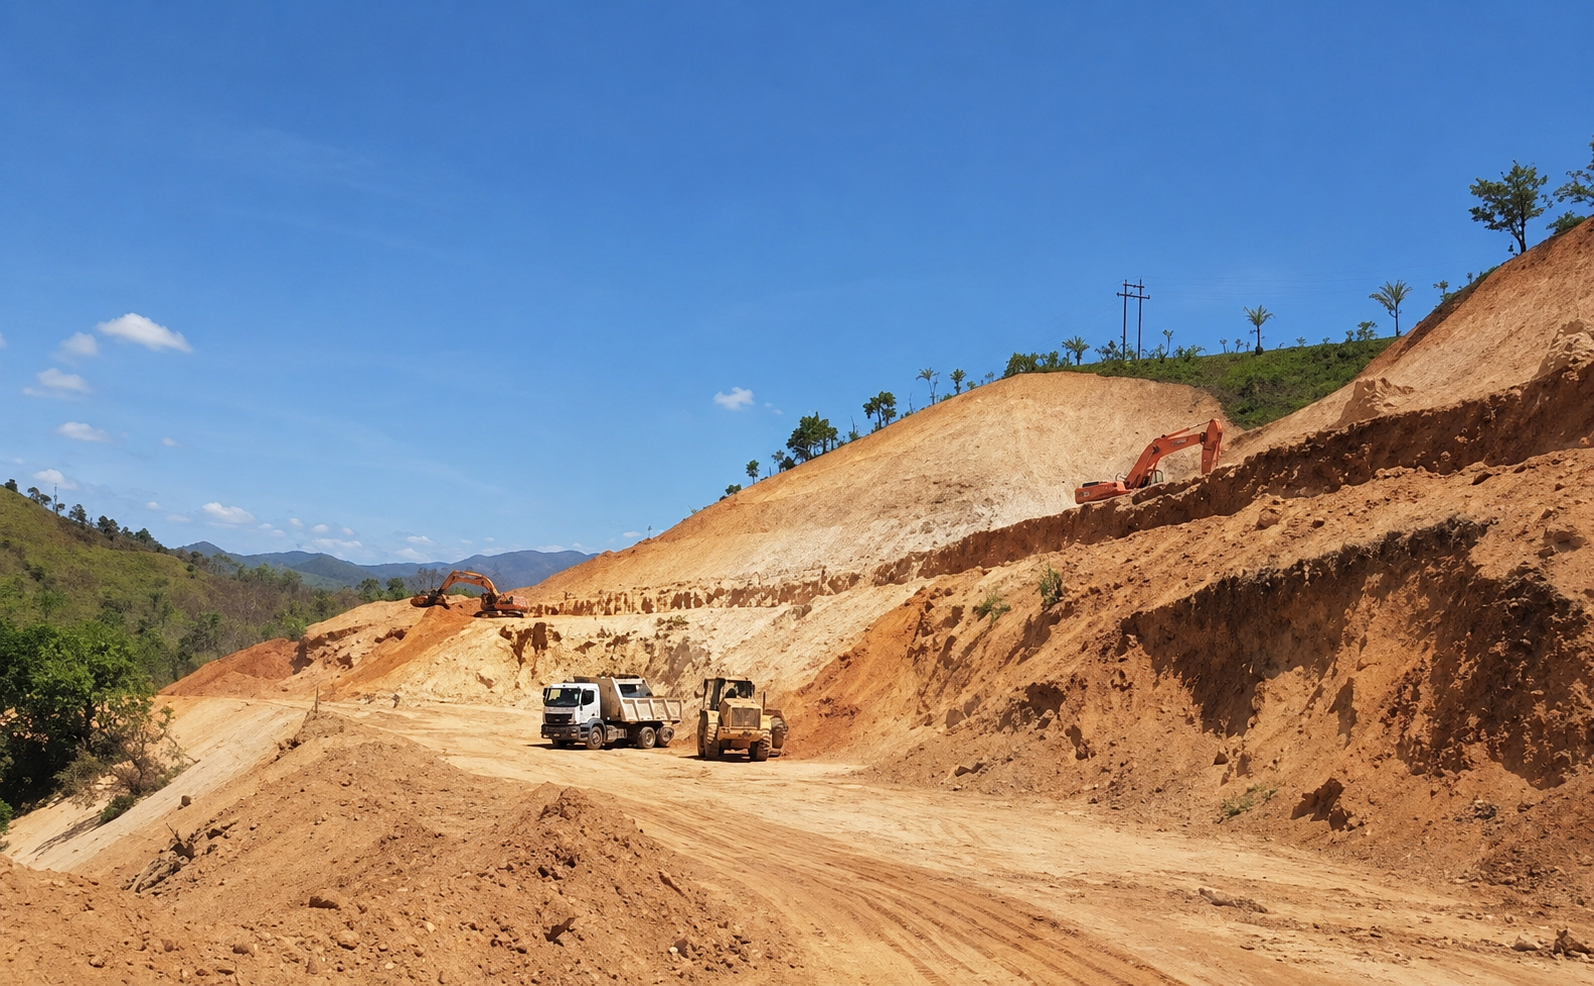
The concept is heap leach with solvent extraction-electrowinning (SX-EW), which Fitzroy's September presentation ties to a 2028 production target. The copper occurs in oxide minerals that a leach solution can dissolve out of crushed rock, though test work confirming this on Buen Retiro material is still underway. Management's conceptual targets, ahead of formal economic studies, are 20,000 to 30,000 tonnes of copper a year, an initial capital of roughly $120 million to $150 million, and all-in costs below $2.00 per pound, with a production decision around mid-2027.
Pucobre, a Chilean producer, mined the original pit profitably from 2005 to 2009, owns half of the underlying option, and signed a letter of intent (LOI) in April 2026 to jointly develop the project. It holds the right to buy 30% of the project at 90% of Fitzroy's cumulative eligible investment, and has confirmed in writing that it intends to exercise this right, with management targeting a reimbursement of approximately C$20 million in mid-2027, subject to final eligible spend. Stonegate treats this as third-party validation from the former operator.
How Stonegate Builds the C$1.04 Target
Neither Buen Retiro nor Caballos has an NI 43-101-compliant resource, so Stonegate assumes a tonnage of 170 million tonnes at 0.60% copper at Buen Retiro and 225 million tonnes at 0.30% copper at Caballos. Applying 70% ownership at Buen Retiro after the contemplated Pucobre clawback, and 100% ownership at Caballos, gives roughly 1.389 million tonnes of attributable contained copper. Stonegate calls this a valuation sensitivity, not a resource estimate, and Caballos is part of the count.
The net asset value (NAV) method applies US$500 per contained tonne, close to the US$506 peer median. A 0.35x enterprise value (EV) to NAV multiple, a discount that reflects the pre-resource, pre-study stage, gives C$1.11 per share. The cross-check applies US$150 per attributable tonne against a peer median of approximately US$440 per tonne in that check, and gives C$0.96. Equal weighting produces the C$1.04 target, which the report labels a 2027 estimate, within a valuation range of C$0.76 to C$1.32.
At C$0.45, Stonegate puts Fitzroy's EV at about US$85.0 million, or roughly US$61 per attributable tonne against a peer median near US$463 in its comparative valuation. That is an approximately 88% discount. The report does not reconcile the two peer medians.
What Is Still Ahead of the Number
Contained metal is not recoverable metal, and the analysis does not directly account for recovery, costs, taxes, or timing. The target is highly sensitive to the maiden Buen Retiro resource and the next phase of Caballos drilling, and the report assigns no separate value to Caballos molybdenum and gold, the Pucobre reimbursement, or deeper Buen Retiro sulfide potential.
Stonegate says management's 20,000 to 30,000 tonnes a year appears materially larger than the capacity described in the Pucobre LOI, so the final plan may need expanded or additional SX-EW capacity. The September presentation shows 50% availability offered at Planta Biocobre, while Fitzroy's management's discussion and analysis for the third quarter, which the report cites, says the LOI offered a minimum of 80% of the roughly 800 tonnes per month nominal capacity. The report says the gap needs clarification, as economic studies set the processing configuration.
Fitzroy held C$23.9 million in cash as of June 30, 2026, with no debt, which Stonegate says covers about 1 year of activity. Stonegate names dilution as the main watch item, with warrants and options adding roughly a fifth to the fully diluted share count.
Catalyst to the 2028 Production Target
Fitzroy's October 5, 2026 release, which is not part of the report, targets a maiden mineral resource estimate and a preliminary economic assessment in the fourth quarter of 2026. The assessment will incorporate Inferred Resources across the wider project area, so the first economic study includes a lower-confidence category.
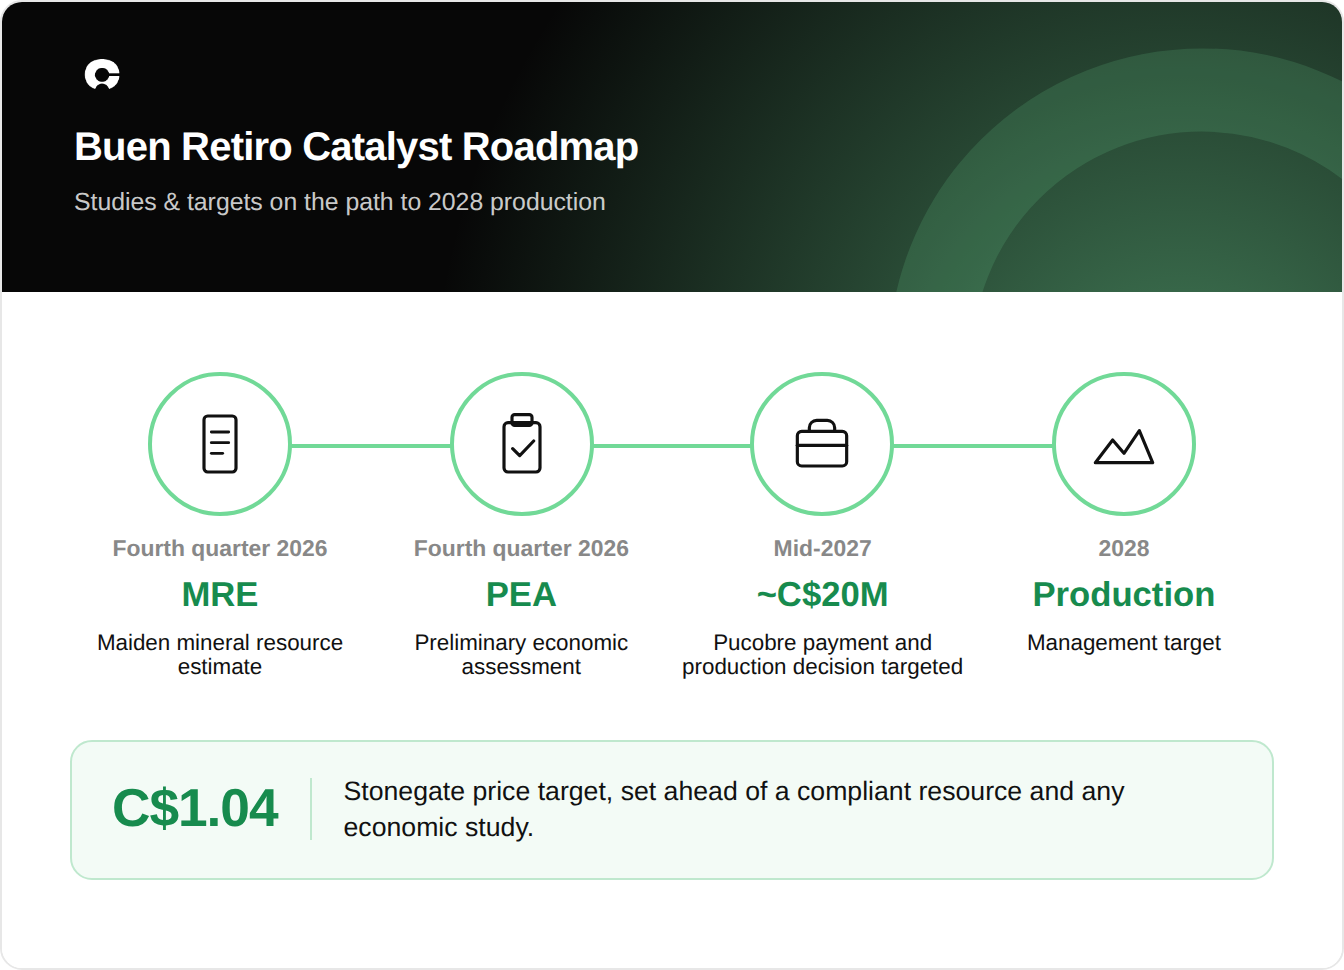
The fourth-quarter documents are the first compliant test of Stonegate's 170 million tonnes at 0.60% copper, and the first formal answer on processing configuration and capital. The production decision and the Pucobre payment are targeted for around mid-2027.
Analyst's Notes





Subscribe to Our Channel
Stay Informed


