Vox Royalty Moves to Bolster Precious Metals Portfolio with $13M Sorby Hills Silver Deal


Vox Royalty (NASDAQ:VOXR) agrees a $13M Sorby Hills silver royalty, completes three Australian deals and guides 2026 receipts to $32M-$37M
- Vox Royalty has raised 2026 receipts guidance to $32 million to $37 million, roughly double 2025, after a record $16.0 million first quarter.
- The company completed three Australian royalties (White Dam, Kalman and Sylvania) for A$8.4 million, each with a distinct production, development or exploration catalyst.
- Vox has agreed a $13 million deal for a 0.75% NSR over the construction-stage Sorby Hills silver-lead project, which still needs FIRB approval and is expected to complete in Q4 2026.
- Management expects a reserve upgrade to extend Sorby Hills' mine life well beyond the 8.5-year base plan at no extra cost to Vox.
Vox Royalty (NASDAQ: VOXR | TSX: VOXR) is growing its receipts at a pace few mid-tier royalty companies can match, and it is doing so without issuing equity. In an interview with Crux Investor, President and Chief Investment Officer Spencer Cole explained how three recent developments fit together: a month of Australian deal-making, a doubling of annual receipts and a set of revalued gold offtake contracts. Vox is positioning itself as a buyer with cash, a sourcing edge and the discipline to walk away from expensive deals. It also argues that the market has yet to price most of what it owns.
Receipts Doubling on Gold Volatility & Offtake Volumes
Vox reported record first-quarter 2026 receipts of $16.0 million. Cole told Crux that the first half came in at just over $20 million, with roughly $6 million in the second quarter. He described the first quarter as an expected outlier driven by gold price volatility. It came close to matching the $16.6 million Vox generated across the whole of 2025.
The company has raised its 2026 guidance to $32 million to $37 million in royalty and net precious metal receipts, up from an original range of $28 million to $32 million. "Receipts" is a non-GAAP measure that combines royalty revenue with net income from Vox's gold offtake agreements. Cole said the offtake and streaming side of the business involves roughly 200,000 ounces of gold deliveries and accounts for about two-thirds of receipts this year. The core royalty portfolio makes up the remaining third. At its May 2026 Investor Day, Vox also published a 2030 outlook of approximately $66 million in annual receipts, which would represent a further doubling from the 2026 midpoint.
Three Australian Royalties, Three Different Catalysts
On September 14, Vox completed the acquisition of three Australian royalties for aggregate cash consideration of A$8.4 million (approximately $6 million), funded from cash on hand. Cole described them as classic Vox transactions in gold and copper, each chosen for a distinct catalyst.
White Dam in South Australia is a producing gold heap leach operation run by Broken Hill Gold, over which Vox holds a 2.0% net smelter return (NSR) royalty. Cole said the heap leach should deliver a solid return on its own. In his view, the bigger draw is a new copper-gold discovery that falls within the royalty area at no additional cost.
Kalman in Queensland carries a 2.0% royalty on production from the Kalman royalty tenement. Cole said Vox had looked at the asset years earlier, when it was comparatively quiet. Consolidation around Mount Isa has since changed that. Within weeks of Vox securing the royalty, operator Hammer Metals (ASX:HMX) received competing takeover proposals. It is now subject to a proposed scheme with Austral Resources (ASX:AR1), which operates the Rocklands plant nearby. Cole said Vox believes this could accelerate Kalman from advanced exploration into development. The scheme is not yet complete.
Sylvania in Western Australia's Pilbara covers approximately 1,700 square kilometres of exploration tenure. The ground is operated by a subsidiary of Capricorn Metals (ASX:CMM) and lies next to its expanding Karlawinda Gold Mine. The royalty is 1.0% NSR on precious minerals and 1.5% NSR on all other minerals. It also covers the Spearhole iron deposit, which has a historical inferred estimate of 1,400Mt at 23.5% Fe, and the Prairie Downs zinc-lead-silver deposit. Cole was clear that Vox does not expect Spearhole to be developed soon. He framed it as long-dated optionality attached to a gold exploration royalty.
Sorby Hills: A Construction-Stage Silver Deal Awaiting Completion
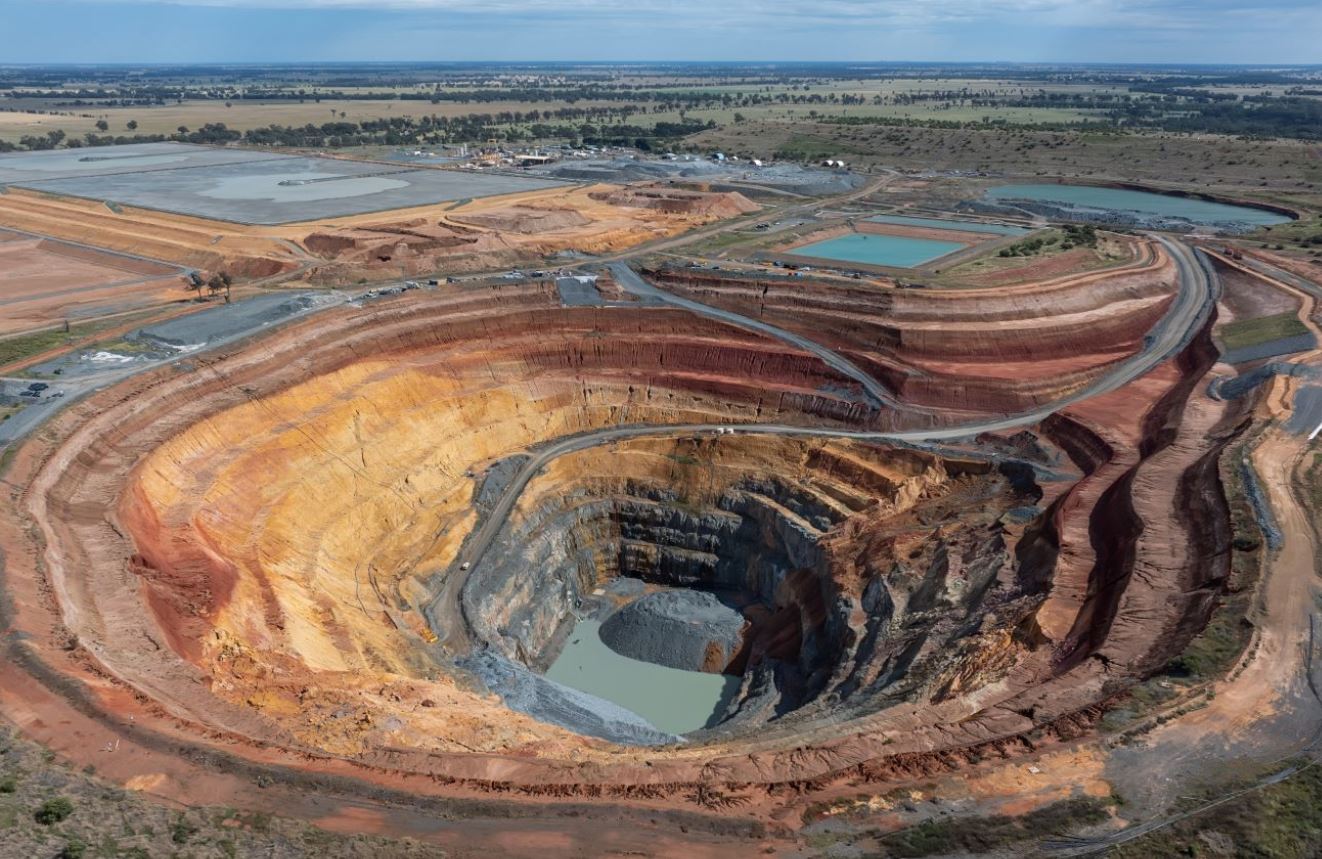
The most significant transaction is also the newest. On September 28, Vox announced a binding agreement to acquire an effective 0.75% NSR royalty for $13 million in cash. The royalty covers Boab Metals' (ASX:BML) Sorby Hills silver-lead project in Western Australia. The transaction has not yet closed. It remains subject to customary conditions precedent and Foreign Investment Review Board (FIRB) approval, with completion expected in the fourth quarter of 2026.
Sorby Hills is fully permitted, funded and under construction. Boab Metals made its final investment decision in December 2025 and is targeting first concentrate production in the second half of 2027. The June 2024 Front-End Engineering and Design (FEED) Study outlines average annual production of approximately 2.2 million ounces of silver and 68,000 tonnes of lead over an initial 8.5-year mine life. On Vox's base case, Cole put the royalty's contribution at about $2 million in annual revenue at current prices.
The investment case rests on mine life rather than the base plan. The FEED Study mining inventory represents only about 39% of the total resource. Boab has also just completed its Phase IX resource-to-reserve conversion drilling programme. Cole expects a reserve update from the operator in the coming weeks and months.
"We ultimately think the [mine] life on this asset could stretch to sort of 10 closer to 20 ... years when all is said and done."
By the time production begins, he expects reserve life to sit closer to 12 to 15 years. The royalty covers the tenements hosting the deposits being drilled, so any such extension would flow to Vox at no additional cost.
Interview with Spencer Cole, President & CIO, Vox Royalty
Offtake Revaluations & the Red Hill Dispute
The gold offtake contracts Vox acquired in September 2025 must be revalued with auditors every quarter. Cole said higher gold prices have widened realised margins, and operational milestones have added to asset values.
At Bonikro in Côte d'Ivoire, Allied Gold has extended the mine life to 2036. Vox's presentation describes this as a roughly 400% increase in expected life-of-mine production. At Los Filos in Mexico, Equinox Gold has secured land-access agreements with all three host communities and plans a phased restart. Cole noted that Vox acquired the Los Filos offtake for a minimal price when the restart was uncertain. He described the resulting revaluations as positive news that creates short-term noise in the income statement.
The Red Hill royalty in Western Australia remains the subject of litigation. Northern Star Resources (ASX:NST) is disputing the prior holder's assignment of the 4% gross revenue royalty to Vox. Vox is defending the action as second defendant in the Western Australian Supreme Court. Cole was measured on the topic. He said the process could take 12 to 24 months and that Vox remains confident in its position.
Balance Sheet Capacity & Capital Discipline
Vox held $31.1 million in cash at June 30, 2026, with no debt and an undrawn $75 million credit facility. Cole said this allows the company to stretch to transactions of $40 million to $60 million without new equity. He was equally clear that size is not the objective.
"We're in a position where we can, stretch to do 40 to $60 million deals and fund them entirely without any additional equity ... [but] we're not kingdom builders. We're focused on return on capital."
If larger deals cannot deliver comparable returns, Vox will keep running what Cole called its base engine of $5 million to $20 million transactions in Australia. He identified rights of first refusal as the main competitive threat in that market, because they allow Australian operators to buy back royalties.
The Valuation Gap
Cole said Vox trades at around 10 times revenue, a multiple he struggles to reconcile with its growth trajectory. He offered no date for a re-rating and pointed instead to continued delivery against guidance. He was candid that investor relations has not been the company's strongest suit. Vox's shareholder base leans towards US value investors and generalists. The company now intends to spend more time with specialist mining investors who may look beyond its top 15 assets.
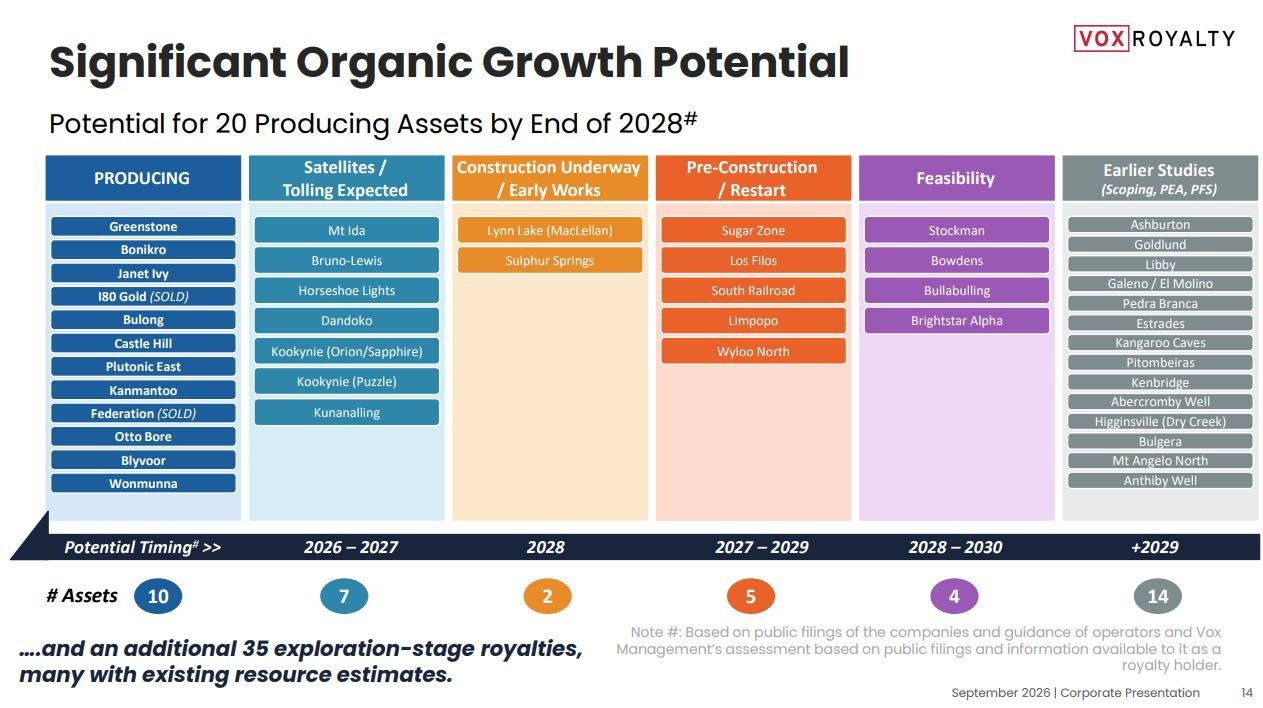
The company has 10 producing assets, 27 development-stage assets and 42 exploration-stage assets. It also sets out a potential path to 20 producing assets by the end of 2028.
Investment Thesis for Vox Royalty
- Receipts guidance of $32 million to $37 million for 2026 implies roughly 100% growth on 2025, driven largely by acquired offtakes and royalties.
- The balance sheet of $31.1 million in cash, no debt and an undrawn $75 million facility supports acquisitions of up to $60 million without dilution.
- Sorby Hills offers near-term silver exposure from a fully funded project, but the $13 million transaction remains subject to FIRB approval and other conditions precedent.
- Investors should monitor Boab Metals' reserve update and fourth-quarter Phase IX assays, which will test management's view of a 12 to 15-year mine life.
- Kalman's value depends on the proposed Austral Resources scheme completing and on Rocklands processing plans for Hammer Metals' assets.
- The Red Hill litigation is a live risk, with a possible 12 to 24-month timeline in the Western Australian Supreme Court.
- Quarterly offtake revaluations will continue to create income statement volatility, so receipts are a cleaner measure of underlying performance.
Macro Thematic Analysis
The royalty and streaming sector has benefited from two forces at once. Higher and more volatile gold prices have widened margins on offtake and stream contracts. Tight capital markets for developers have also increased demand for non-dilutive funding. In that environment, the difference between royalty companies often comes down to sourcing and pricing discipline rather than access to capital.
Vox operates at the smaller, more fragmented end of the market. Much of its activity involves buying existing third-party royalties that sit outside conventional deal channels, many of them in Australia. That niche is less crowded than large stream financings, which helps protect returns. It also means scale depends on volume and repeatable execution.
Silver adds a further angle. Sorby Hills brings a silver-dominant revenue stream into a portfolio that was about 89% gold by first-half 2026 receipts. It broadens commodity exposure while keeping the precious metals weighting that royalty investors typically prefer.
The broader question is how the market values optionality. Large royalty companies are often valued on the whole portfolio, including assets years from production. Smaller names tend to be valued on producing assets only. Cole framed this as the central issue for Vox.
"I think that the biggest valuation disconnect is that our development assets are generally valued at zero or book value, which is close to zero."
If development assets such as Sorby Hills, Los Filos and Kalman progress as operators plan, the market will have more concrete evidence against which to test that argument.
TL;DR:
Vox Royalty is guiding to $32 million to $37 million in 2026 receipts, roughly double 2025, after a record $16.0 million first quarter. It completed three Australian royalties (White Dam, Kalman and Sylvania) for A$8.4 million. It has also agreed a $13 million deal for a 0.75% NSR over Boab Metals' Sorby Hills silver-lead project, which still needs FIRB approval and is expected to complete in Q4 2026. President Spencer Cole expects Sorby Hills' mine life to extend well beyond the 8.5-year base plan. With $31.1 million in cash, no debt and an undrawn $75 million facility, Vox can fund deals of up to $60 million without equity. Management argues its development assets are valued near zero.
FAQs (AI-Generated)
Analyst's Notes





Subscribe to Our Channel
Stay Informed