U.S. Gold Corp. Establishes CK Gold Financing While Keeping M&A Door Open


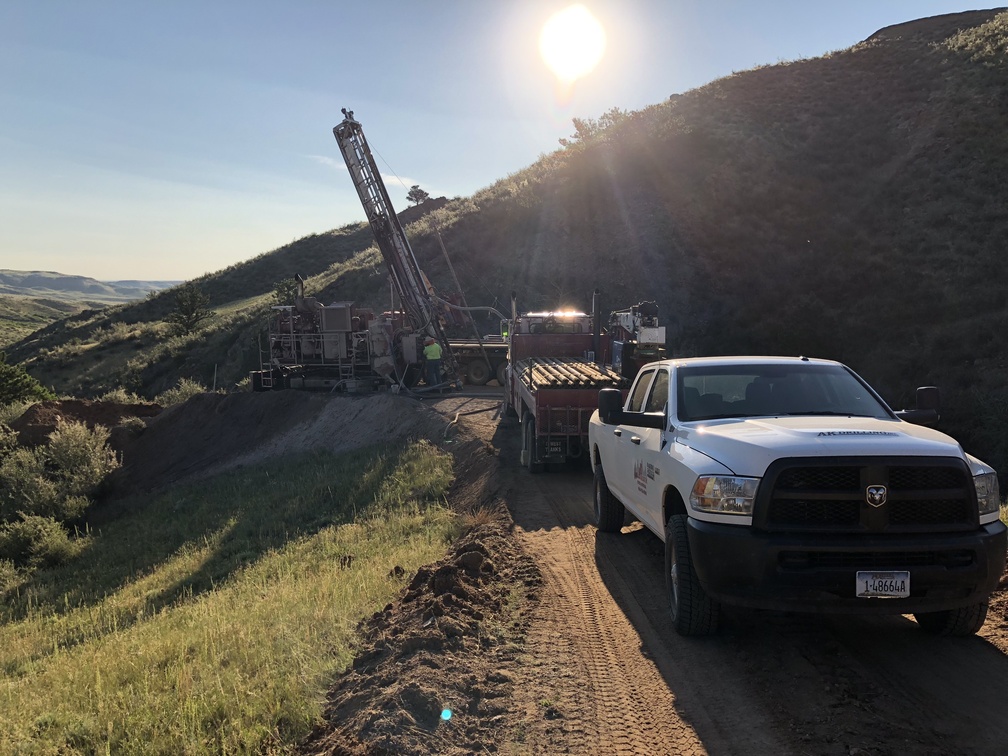
U.S. Gold Corp. (NASDAQ:USAU) advances its fully permitted CK Gold copper-gold project in Wyoming towards financing, with a $632M NPV and 27% IRR.
- U.S. Gold Corp.'s CK Gold Project in Wyoming is fully permitted and is now advancing towards construction financing.
- The March 2026 feasibility study shows a $632 million after-tax NPV and a 27% IRR on $394 million of initial capital at $3,250 per ounce gold.
- The appointment of an EPCM partner and a financing adviser are the next near-term catalysts for the company.
- Management prefers to use CK Gold's silver credit rather than stream gold or copper as part of the financing package.
- A dual-track strategy keeps the company open to acquisition by mid-tiers seeking near-term production in a stable jurisdiction.
Fully permitted gold projects in stable jurisdictions have become scarce. Mid-tier producers and emerging juniors face the same arithmetic every quarter. Production depletes reserves, and replacing them through grassroots discovery can take a decade or longer. That scarcity sits at the centre of the investment case for U.S. Gold Corp. (NASDAQ:USAU), owner of the CK Gold Project in southeast Wyoming.
Speaking at the Denver Gold Forum, President and CEO George Bee described a dual-track strategy. The company is advancing CK Gold towards construction while recognising that its profile makes it a natural acquisition target. Near-term steps include expanding the team, appointing an engineering, procurement and construction management (EPCM) partner and naming a financing adviser. Each step is intended to narrow the valuation discount that typically applies to pre-construction developers.
The commodity backdrop is supportive on both metals. Bee pointed to tight smelter supply of copper concentrate and demand from electrification and data centres, with copper trading at around $6.50 per pound. CK Gold's March 2026 feasibility study was built on a $3,250 per ounce gold price, which leaves room for upside if current pricing holds.
A Permitted Copper-Gold Development in Wyoming
CK Gold is designed as a 20,000 ton per day open pit operation producing a copper-gold concentrate with a silver credit. The proven and probable reserve contains 1.015 million ounces of gold, 260 million pounds of copper and 3 million ounces of silver, equal to 1.598 million gold equivalent ounces. The feasibility study outlines an 11-year mine life averaging 85,000 gold equivalent ounces per year.
Production is weighted towards the early years because the best grades sit near the top of the deposit. Bee said the operation would produce over 100,000 ounces a year in its first three years. The study's appendix shows an average of 102,000 gold equivalent ounces per year from year two to year eight.
The permitting record is what separates CK Gold from most peers. The Wyoming Department of Environmental Quality approved the mine operating permit in April 2024. Water discharge and air quality approvals followed later that year, and a water supply agreement with the Cheyenne Board of Public Utilities was completed in November 2025. The project sits on State of Wyoming land with no direct federal involvement. Initial access road works began in January 2026.
Location is central to the company's view of execution risk. The site lies roughly 20 minutes west of Cheyenne and about 3 miles north of Interstate 80, with road, rail, power, water and a local workforce already in place. Bee argued that this proximity simplifies the build considerably.
"Development is always an issue but relatively speaking because of our location this is a fairly simple project to develop. As we go through those processes, the discount to the valuation we see starts reducing."
Feasibility Economics & Price Leverage
CK Gold's project feasibility study in March 2026, using base case prices of $3,250 per ounce gold, $4.50 per pound copper and $40 per ounce silver, the study shows an after-tax net present value (NPV5%) of $632 million and an after-tax internal rate of return (IRR) of 27%. Payback is 2.5 years on initial capital of $394 million, including contingency. Sustaining capital is estimated at $35 million.
The project is highly geared to metal prices. At $4,500 per ounce gold, the after-tax NPV rises to $1.155 billion with a 42% IRR and a 1.6-year payback. At $5,000 per ounce, the after-tax NPV reaches $1.363 billion. Bee said the project pays back in about a year and a half at consensus pricing, which is consistent with the study's sensitivity range.
Copper and silver credits bring all-in sustaining costs (AISC) down to $1,094 per ounce of gold on a by-product basis. On a co-product basis, the study reports AISC of $1,814 per gold equivalent ounce.
Interview with George Bee, President & CEO of U.S. Gold Corp.
Building the Financing Stack
U.S. Gold has run lean to reach this point. The company has approximately 16.5 million shares outstanding and reported $30.7 million in cash as of 30 April 2026, following a $31.2 million private placement in December 2025. Bee said management, insiders and supportive shareholders have been prioritised by conserving capital and operating with a small team.
That approach now shifts. The company plans to add people with project construction experience, announce an EPCM partner and appoint a financing adviser to assess the term sheets it has already received. Bee described those term sheets as offering attractive options without heavily diluting equity.
He expects the eventual package to combine equity and debt. The company's assets are currently unencumbered, and management is selective about which metal streams it would sell.
"We're not too keen on putting a stream on the gold and copper, but we've got a silver component which we could use as part of the financing."
With an initial capital requirement of $394 million against a market capitalisation of $266.4 million, the structure of that financing will largely determine per-share value for existing holders.
Dual Track: Developer or Acquisition Target
Bee joined U.S. Gold six years ago as the company pivoted from pure exploration in Nevada to developing CK Gold. His career includes senior roles at Barrick Gold, Rio Tinto and Anglo American. He was candid that the company is running two processes at once.
Over the summer, U.S. Gold hosted site visits and parties in its data room. Bee said he cannot afford to wait on those conversations and must keep advancing the project. His reasoning is that each de-risking milestone, from financing to construction, lifts value whichever track ultimately prevails.
On scale, Bee acknowledged that CK Gold will not move the needle for the largest producers. He sees it as a meaningful addition for emerging producers and mid-tiers operating at up to around half a million ounces per year. For those buyers, a permitted project with a 24-month build in a stable jurisdiction avoids years of permitting risk.
The company also holds the Keystone Project on Nevada's Cortez Trend and the Challis Gold Project in Idaho. Bee said Nevada does not currently accrue much value in the market capitalisation, despite Keystone's potential. Executive Chairman Luke Norman plans to explore a spin-out of Keystone.
Resource Upside & Aggregate Optionality
The feasibility study captures only part of the deposit. Bee said additional resources sit below the planned pit, and the company is now looking more broadly at exploration around it. The latest estimate includes 590,000 gold equivalent ounces of measured and indicated resources and 677,000 gold equivalent ounces of inferred resources outside the reserve. A drill programme is anticipated in the second half of 2027.
Bee also highlighted potential improvements in gold recovery and a less conventional revenue stream. Waste rock from CK Gold has tested as suitable for construction aggregate and rail ballast. The market studies suggest around 1 million tons per year of offtake demand and a non-binding letter of intent for ballast delivery to a major railway. This revenue is not fully captured in the feasibility study.
Investment Thesis for U.S. Gold
- CK Gold is fully permitted on State of Wyoming land, which removes the main source of delay facing most North American development projects.
- The March 2026 feasibility study shows an after-tax NPV of $632 million and a 27% IRR at $3,250 per ounce gold, with significant leverage to higher prices.
- By-product AISC of $1,094 per ounce reflects meaningful copper and silver credits in the concentrate.
- A tight share structure of about 16.5 million shares means financing terms will have an outsized effect on per-share value.
- Investors should monitor the appointment of an EPCM partner and financing adviser as the next de-risking milestones.
- Watch the structure of the financing package, particularly the size of any silver stream relative to debt and equity.
- Resources outside the reserve pit, a planned 2027 drill programme and aggregate sales offer upside that is not reflected in base case economics.
Macro Thematic Analysis
The gold sector's pipeline problem has become more acute. Producers have enjoyed strong margins, yet grassroots exploration spending has fallen as a share of budgets. That leaves a thin list of advanced projects that could replace depleting reserves within a reasonable timeframe. Permitting has become the binding constraint in many jurisdictions, often taking longer than construction itself.
This dynamic shifts value towards projects that are already permitted. A developer with approvals in hand offers a buyer a shorter path to cash flow and fewer regulatory unknowns. Bee framed CK Gold's appeal to acquirers in precisely those terms.
"It's a meaningful addition and the thing is that you don't have to wait to put it into the portfolio. We can build in 24 months and bingo, you've got a solid production base in a stable jurisdiction."
Copper adds a second layer to the thesis. Concentrate markets have tightened as smelters compete for feed, while electrification and data centre construction continue to lift demand. A clean gold-copper concentrate with few deleterious elements is well placed to find buyers in that environment. For CK Gold, copper also functions as a natural hedge against gold price volatility.
Jurisdiction completes the picture. Wyoming generates significant revenue from coal, oil, gas and trona, and gold-copper production would diversify the state's mineral tax base. Royalties from the state mineral lease are earmarked for education. That alignment between project and state interests is uncommon and supports a stable operating environment.
TL;DR
U.S. Gold Corp. is moving its fully permitted CK Gold Project in Wyoming towards construction financing. CEO George Bee plans to appoint an EPCM partner and a financing adviser to assess existing term sheets, with a preference for using the silver credit rather than streaming gold or copper. The March 2026 feasibility study shows a $632 million after-tax NPV, 27% IRR and $394 million initial capital at $3,250 gold, rising sharply at higher prices. The 11-year mine averages 85,000 gold equivalent ounces per year and exceeds 100,000 ounces in early years. With about 16.5 million shares, $30.7 million in cash and a dual track that keeps M&A open, financing terms are the key watch-item.
FAQ (AI-generated)
Analyst's Notes





Subscribe to Our Channel
Stay Informed