




Selkirk Copper's Filed Minto PEA Sets the Bar for Its 2027 Feasibility Study


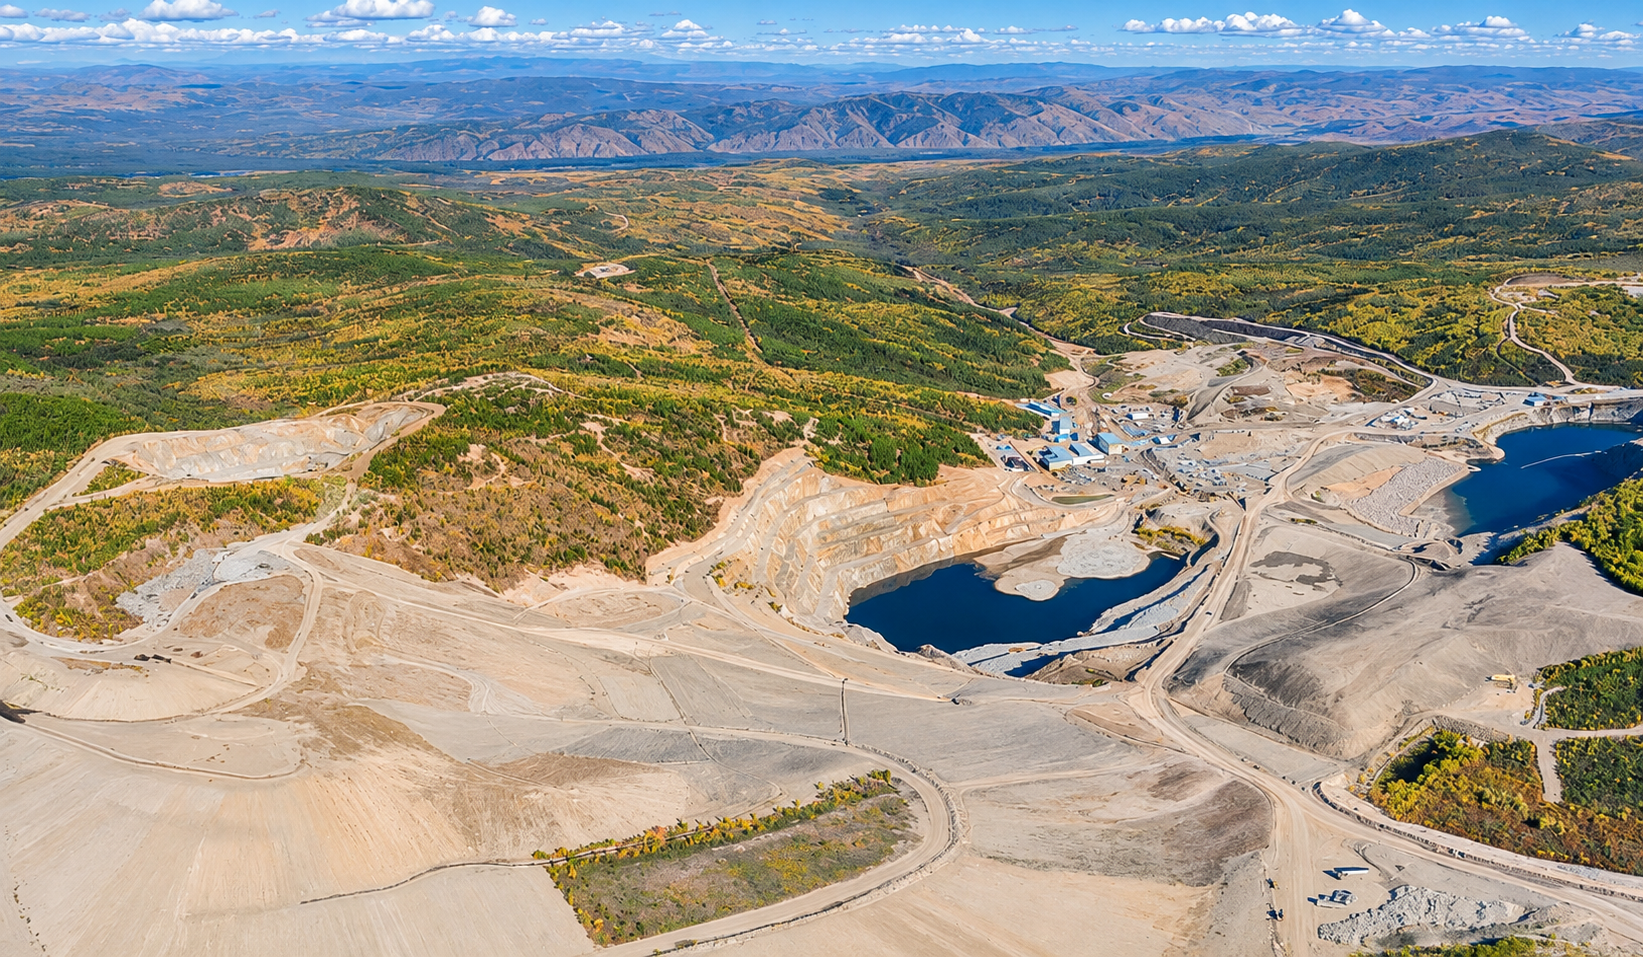
Selkirk Copper's filed Minto PEA establishes a C$186 million, 13-year restart baseline ahead of its mid-2027 Feasibility Study and investment decision.
- Selkirk Copper filed the NI 43-101 technical report for its Minto preliminary economic assessment (PEA) on November 5, 2026, with no material differences from the results released on September 22, 2026.
- The filed PEA outlines a 13-year underground and open-pit restart through the existing 4,100 tonne per day mill, with C$186 million in initial capital and an after-tax net present value (NPV7%) of C$494 million at planning prices.
- The PEA mine plan uses 18.4 million tonnes, about 80% Indicated, from a resource now holding 47.8 million tonnes in the Measured and Indicated categories, and excludes all Phase 2 drilling.
- Selkirk is targeting 10% to 20% higher throughput, a 3% to 4% increase in copper recovery, and about 30,000 tonnes per year of copper-equivalent output in its Feasibility Study (FS), while holding restart capital near C$200 million.
- An updated resource estimate in the first quarter of 2027 feeds an FS and final investment decision (FID) targeted for mid-2027, ahead of first production targeted for mid-2028.
What Has Happened
Selkirk Copper Mines Inc. (TSXV: SCMI | OTCQX: SKRKF) filed the independent NI 43-101 technical report supporting the preliminary economic assessment (PEA) for its 100%-owned Minto Project in Yukon on SEDAR+ on November 5, 2026. The filing puts the full assumptions, cost build-up and mine plan behind the September 22, 2026 headline results on the public record, and the company states the report, effective September 21, 2026, contains no material differences from them. Hatch Ltd. led the report, with input from 5 other consulting groups including SRK Consulting (Canada) Inc.
The filed figures form the baseline for Selkirk's published Feasibility Study (FS) targets. The company is aiming to lift throughput and copper recovery while keeping restart capital near C$200 million, and both the first quarter 2027 resource update and the mid-2027 FS will be measured against the November 5, 2026 report.
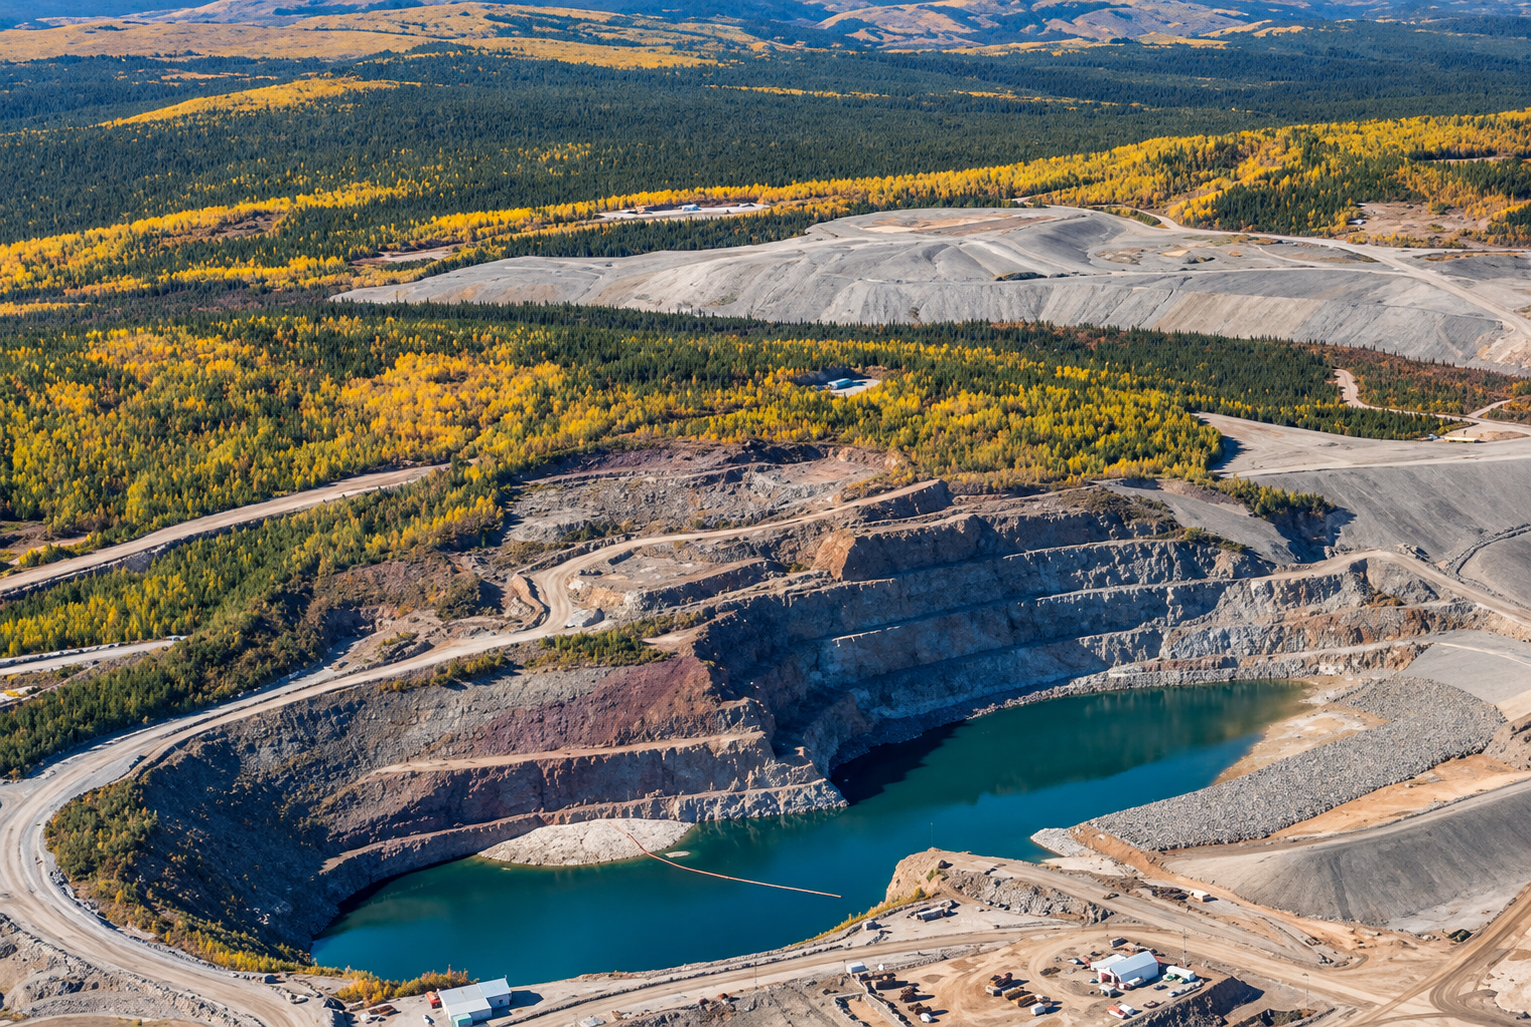
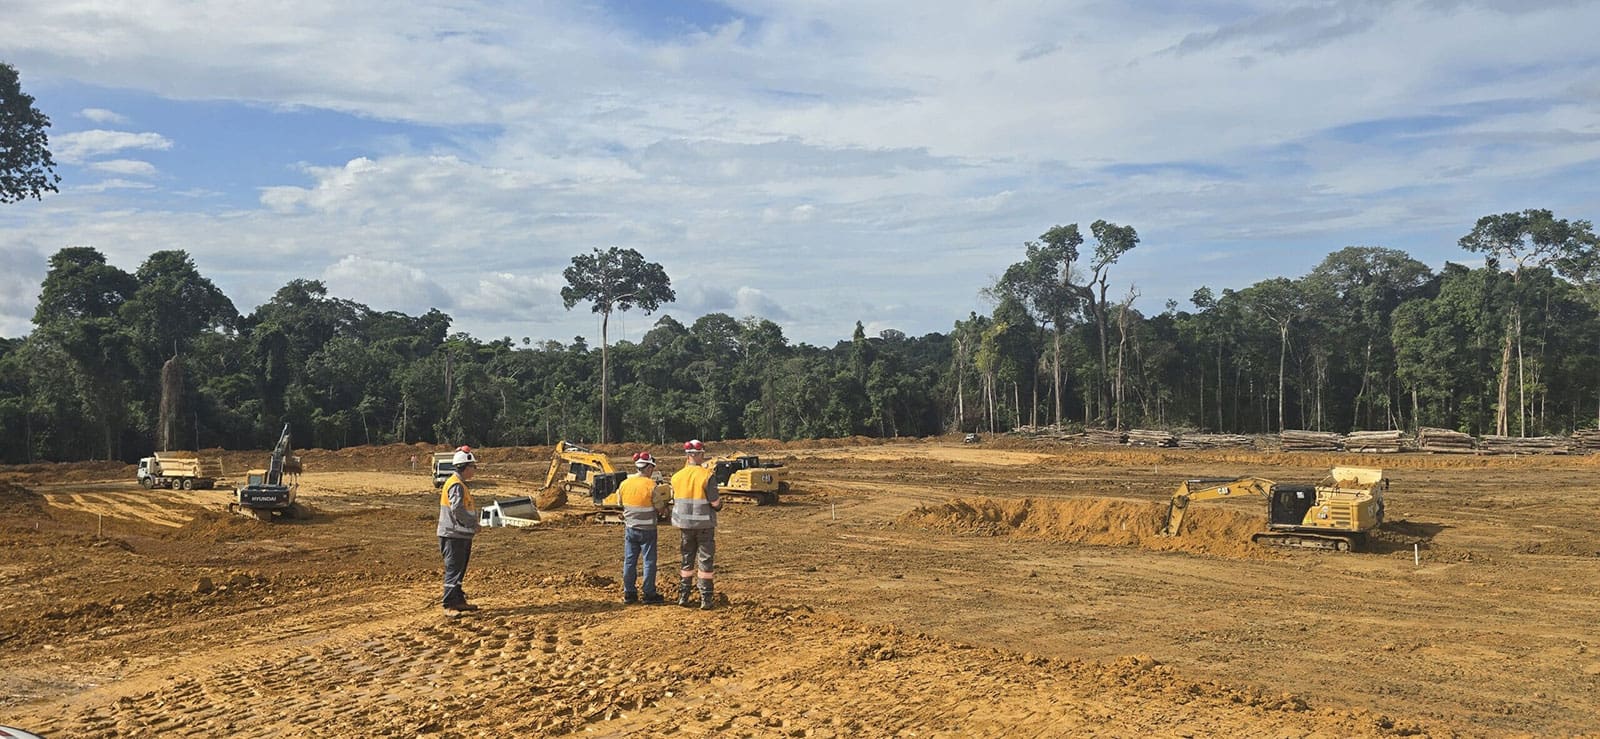
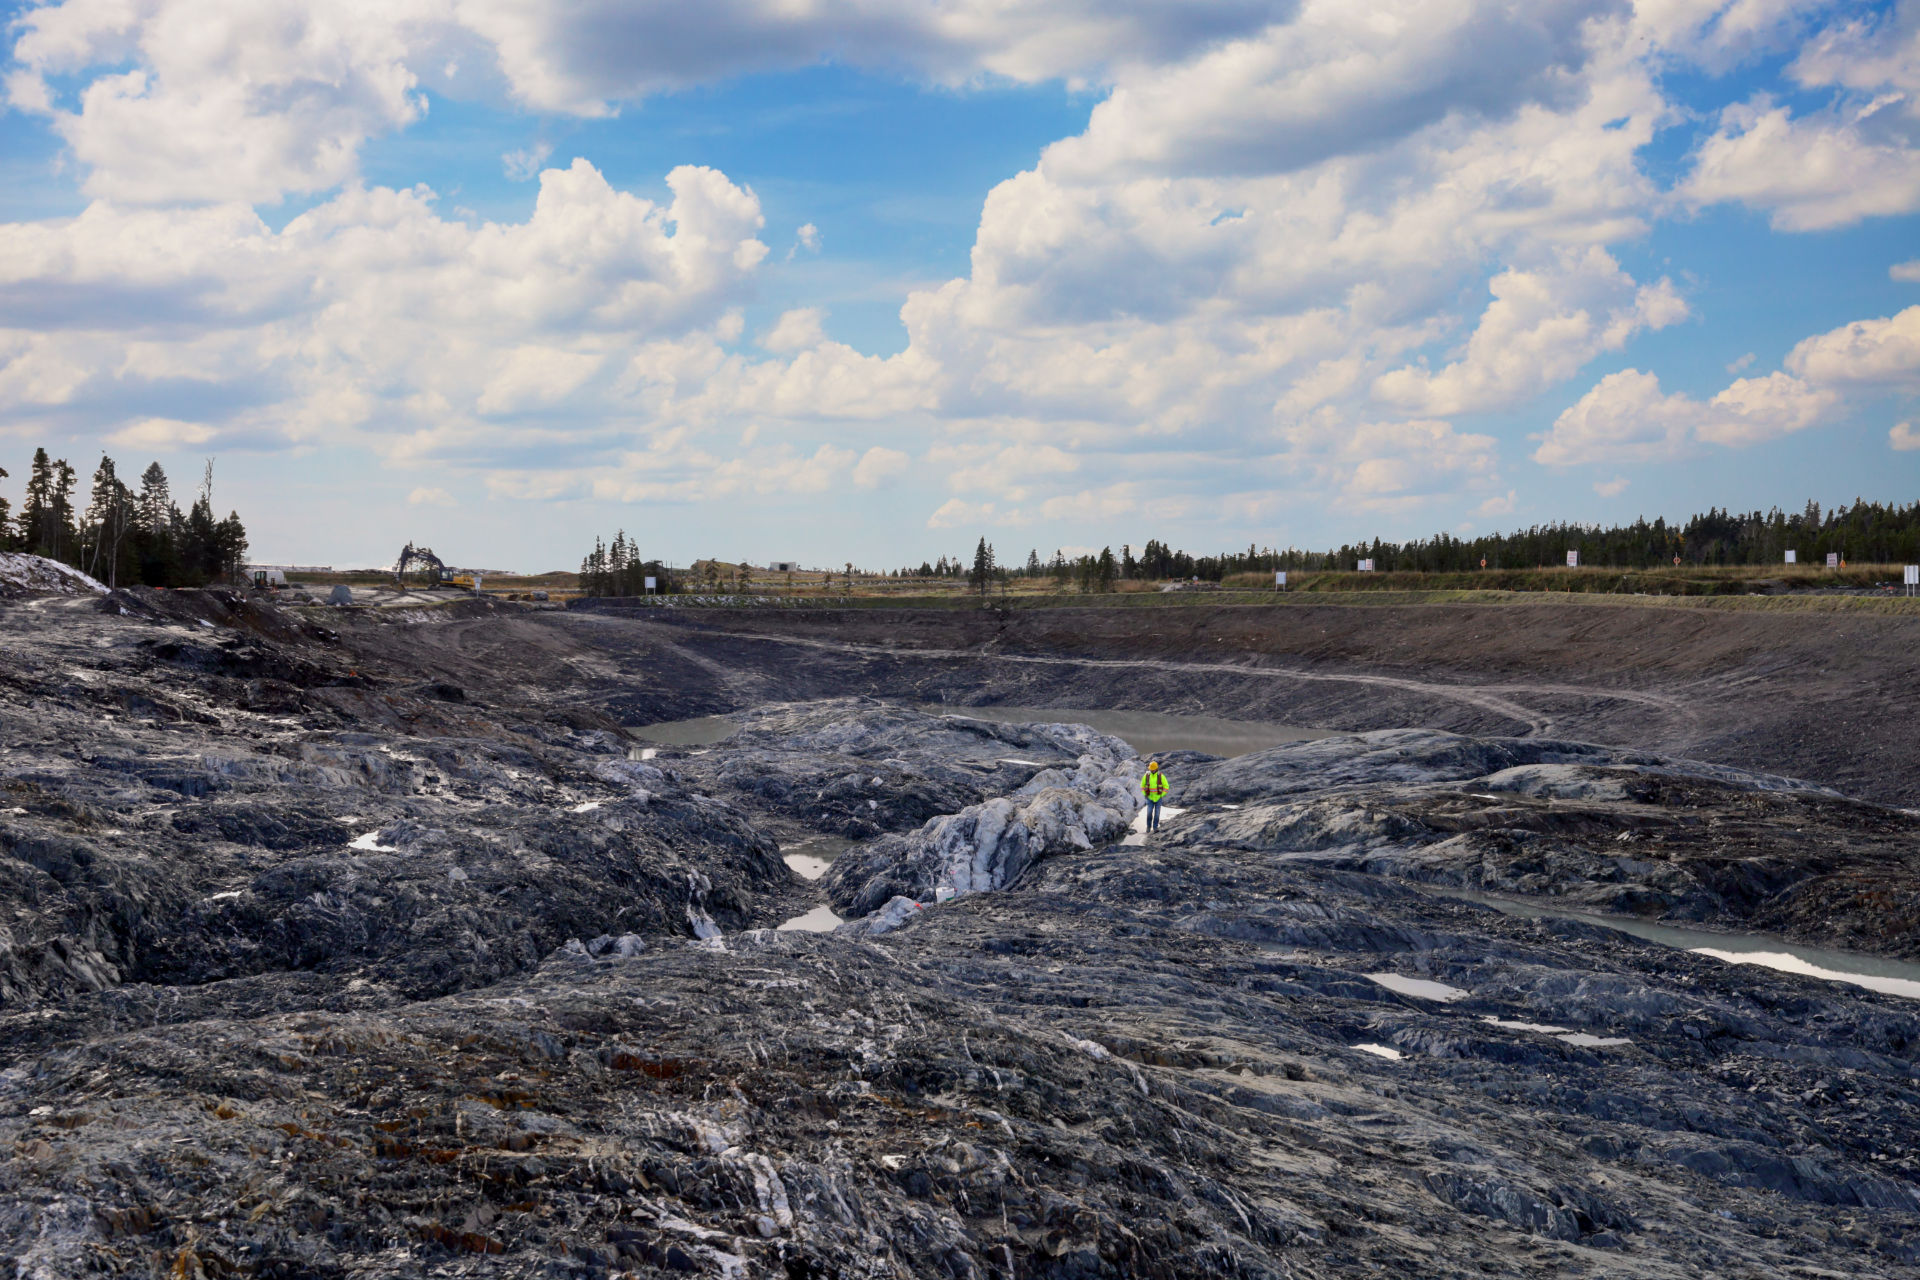
Minto is a former producing copper-gold-silver mine. The Selkirk First Nation acquired it through a bankruptcy process and vended it into Selkirk Copper through a reverse takeover in November 2025. Prior operators invested over C$330 million in above-ground infrastructure, according to the company, including a 4,100 tonne per day processing plant, open pit and underground workings, a 400-person camp, water treatment facilities and an 8.5 megawatt connection to the Yukon grid.
What the Filed PEA Commits To
The PEA outlines a 13-year mine life, with underground mining first and open pit mining second, feeding the existing mill at 1.5 million tonnes per year, or 4,100 tonnes per day. Initial capital is C$185.9 million, made up chiefly of C$77.6 million for mining, C$54.3 million of indirect costs and C$22.6 million of contingency, against pre-study guidance of C$200 million to C$225 million. Initial capital covers the restart only. The PEA adds C$338 million of sustaining capital over the life of mine and C$71 million of closure costs.
The base case uses planning prices of US$5.00 per pound of copper, US$3,600 per ounce of gold and US$50 per ounce of silver. On that basis, the PEA returns an after-tax net present value (NPV7%) of C$494 million, an after-tax internal rate of return (IRR) of 48% and a 1.9-year payback, with average annual revenue of C$291 million, earnings before interest, taxes, depreciation, and amortization (EBITDA) of C$141 million and after-tax free cash flow (FCF) of C$83 million. A spot-price sensitivity at US$6.50 per pound of copper, US$4,300 per ounce of gold and US$65 per ounce of silver lifts the NPV7% to C$1.0 billion and annual free cash flow to C$146 million, and measures exposure to metal prices, not the base case.
Life-of-mine (LOM) payable production totals 377 million pounds of copper, 225,000 ounces of gold and 1.4 million ounces of silver, averaging 40 million pounds of copper equivalent a year at a C1 cash cost of US$1.53 per pound of copper net of by-product credits. In the peak year, copper-equivalent production in concentrate reaches 27,200 tonnes. The flowsheet recovers 89% of copper, 85% of gold and 77% of silver into a concentrate grading approximately 38% copper, 16 grams per tonne gold and 133 grams per tonne silver, to be trucked seasonally to the Port of Skagway, Alaska.
The PEA Mine Plan & the Resource Behind It
The 18.4-million-tonne PEA mine plan is about 80% Indicated and 20% Inferred, a split that applies to the mine plan alone. The wider Mineral Resource Estimate (MRE), effective June 10, 2026, reports Measured and Indicated (M&I) resources of 47.8 million tonnes at 0.89% copper, 0.34 grams per tonne gold and 3.2 grams per tonne silver, containing 940 million pounds of copper and 530,000 ounces of gold, plus 16.9 million tonnes of Inferred resources at 0.76% copper. Contained M&I copper rose 182% and gold 184% against the 2025 estimate after the 52,288-meter Phase 1 program, and the PEA mine plan excludes the 50,000-meter Phase 2 program entirely.
Phase 2 has 2 separate jobs. Infill drilling is designed to convert material already in the mine plan from Indicated to Measured, the confidence level the FS requires, while expansion drilling targets extensions of the known zones.
President and Chief Executive Officer of Selkirk Copper, Colin Joudrie, described the range of outcomes for the 18.4-million-tonne base:
"It'll either stay the same, and it'll be better quality, or it will grow. But remember, we're taking it from indicated quality to measured."
Phase 2 reached 54,711 meters in 223 holes by October 14, 2026. Recent results include an intercept at Minto North of 5.4 meters of 9.27% copper, 7.43 grams per tonne gold and 54.9 grams per tonne silver (15.11% copper equivalent), in the 99th percentile of more than 4,300 historical Minto intercepts, and an intercept of 44.7 meters of 2.12% copper, 1.16 grams per tonne gold and 10.7 grams per tonne silver (3.0% copper equivalent) reported on October 15, 2026.
Feasibility Study Targets Against the PEA Baseline
Selkirk has published FS objectives that map onto the filed PEA figures. The company is targeting an increase in mining and milling rates from 4,100 tonnes per day to between 4,500 and 4,900 tonnes per day, a 10% to 20% gain, based on updated mine plans and mill optimization work. Metallurgical testwork is targeting an increase in copper recovery of 3% to 4%, with gold and silver recoveries also targeted to improve in line with historical recoveries.
Those 2 levers feed an output target of about 30,000 tonnes per year of copper equivalent contained in concentrate. The company's own scorecard sets this against the PEA's 27,200-tonne peak year, and the 2 measures differ: the FS figure is an annual target, while the PEA's LOM average is 40 million pounds of copper equivalent a year. On costs, the company is targeting C1 cash costs of US$1.50 to US$1.60 per pound of copper against the PEA's US$1.53, and restart capital of approximately C$200 million against C$186 million, with the estimate adjusted to meet the throughput objectives. The 13-year mine life is to be maintained with greater resource conversion, and the sustaining capital and closure estimates are to be held with increased confidence.
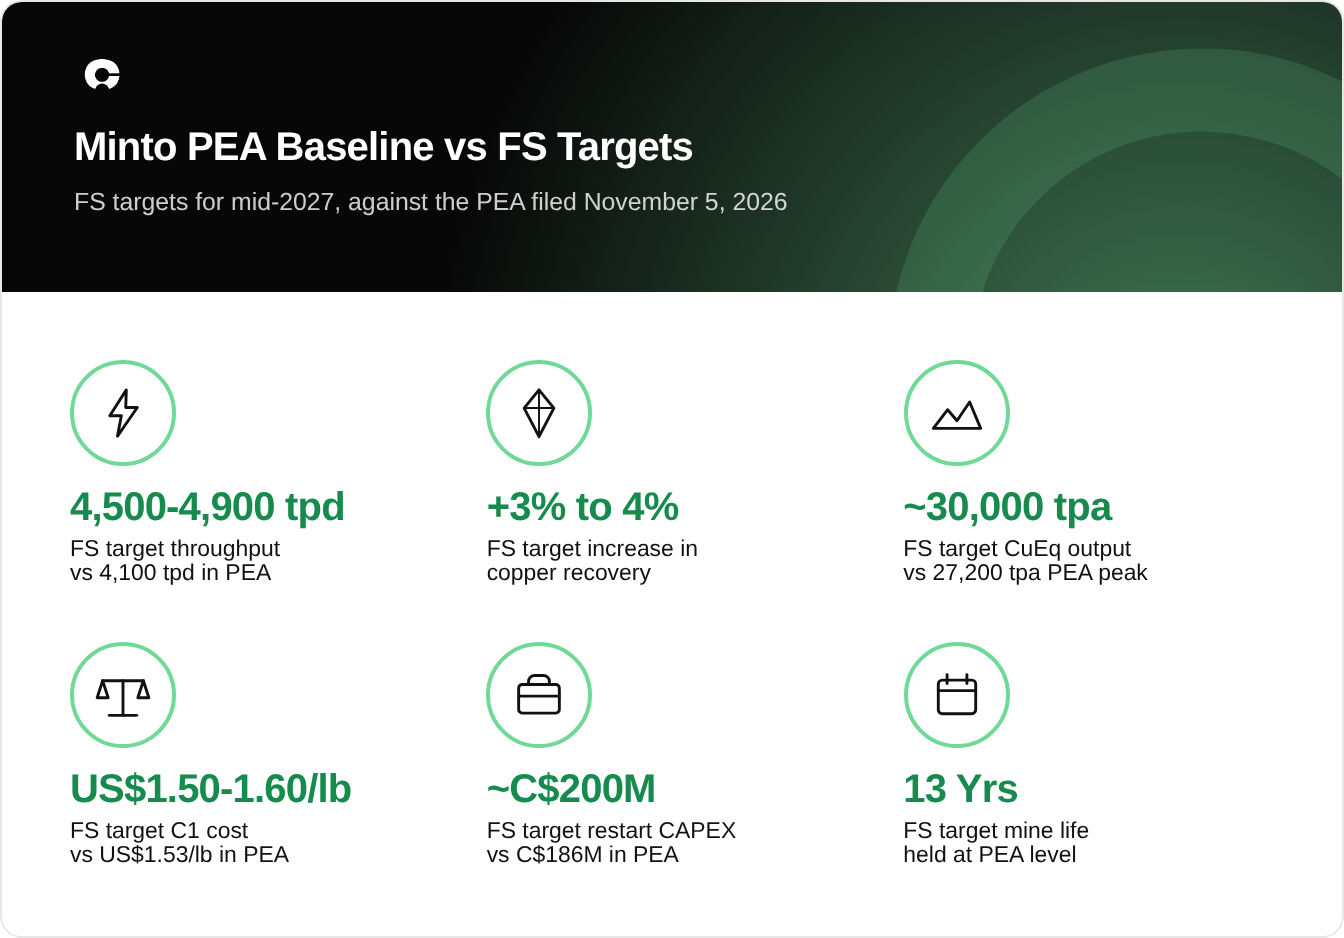
The FS therefore has a measurable test: more tonnes through the same plant at a higher recovery, with operating costs held near PEA levels and restart capital near C$200 million. Each target is stated against a filed number, so the FS result can be compared line by line with the November 5, 2026 report.
Execution Work Running Alongside the Study
Before the mid-2027 final investment decision (FID), Selkirk has site work to complete that sits outside the PEA capital estimate. The company estimates C$20 million to C$25 million of pre-capital costs before a restart decision, covering dewatering, physical rehabilitation and re-servicing of the underground workings, ongoing water treatment, refurbishment of 2 backup diesel generators and regular site care and maintenance. Deposits for fixed and mobile equipment are included in the PEA capital estimate but may be paid before the FID.
Underground access sets the sequence. The company estimates the underground dewatering program at about 5 months once started, after which rehabilitation of the underground can begin, and water management becomes the company's full-time responsibility in March 2027. Selkirk has presented a fully costed dewatering program to government, and Joudrie acknowledged that the timing of approval could affect the schedule:
"It could, in a really worst-case scenario; it could. Our gating item is authorization from the government to start the dewatering."
Cash of C$36.9 million at July 30, 2026 funds completion of Phase 2, the resource update and FS work. The FS also includes an execution plan built with Early Contractor Involvement, in which construction contractors contribute to the bid documents on safety systems, rotations, labor and installation hours.
Joudrie outlined what the study is designed to deliver at the decision point:
"Actually, it will be not just FID, it will be FID with an execution plan in hand."
Broader Context & What to Watch Next
Selkirk's basic market capitalization was approximately C$212 million at C$1.27 per share on October 2, 2026, against the PEA's base-case NPV7% of C$494 million. Project NPV7% is not equity value. The PEA is preliminary, includes Inferred resources and does not demonstrate economic viability, and the restart still carries financing, permitting and execution risk. Cash of C$36.9 million compared with C$186 million of initial capital, and the company points to the offtake and stream removed in bankruptcy as potential sources of non-dilutive capital and improved cash flow.
The upcoming milestones work as a sequence of tests. The updated MRE will show how much of the resource behind the 18.4-million-tonne plan moves into the Measured category and how much Phase 2 adds. Dewatering and underground rehabilitation will show whether site readiness keeps pace with the study.
The FS will then show whether higher throughput and recovery can be delivered with restart capital near C$200 million and C1 costs of US$1.50 to US$1.60 per pound, and the FID will draw on that result alongside a financing plan.
FAQs (AI-Generated)
Analyst's Notes





Subscribe to Our Channel

Stay Informed


