




Institutions Back Atlas Salt's Raises Ahead of a C$589M Financing Test


Institutions took about 50% and 71% of two Atlas Salt raises, while the C$589 million build relies on financing with letters of interest above C$300 million.
- Institutions and strategics took about 50% of Atlas Salt's October 2025 raise and about 71% of its June 2026 raise, by the company's approximate splits.
- The Bedford Park Opportunities Fund bought shares in February 2026 despite generally not buying pre-revenue companies, and a later Newfoundland site visit and meetings with management and board members reinforced its confidence.
- The June 2026 deal priced at C$1.20, up 50% from C$0.80 about 8 months earlier, and the stock last traded at C$1.26 on October 23, 2026.
- Known institutions and strategics hold only about 12% of basic shares, by the company's estimate.
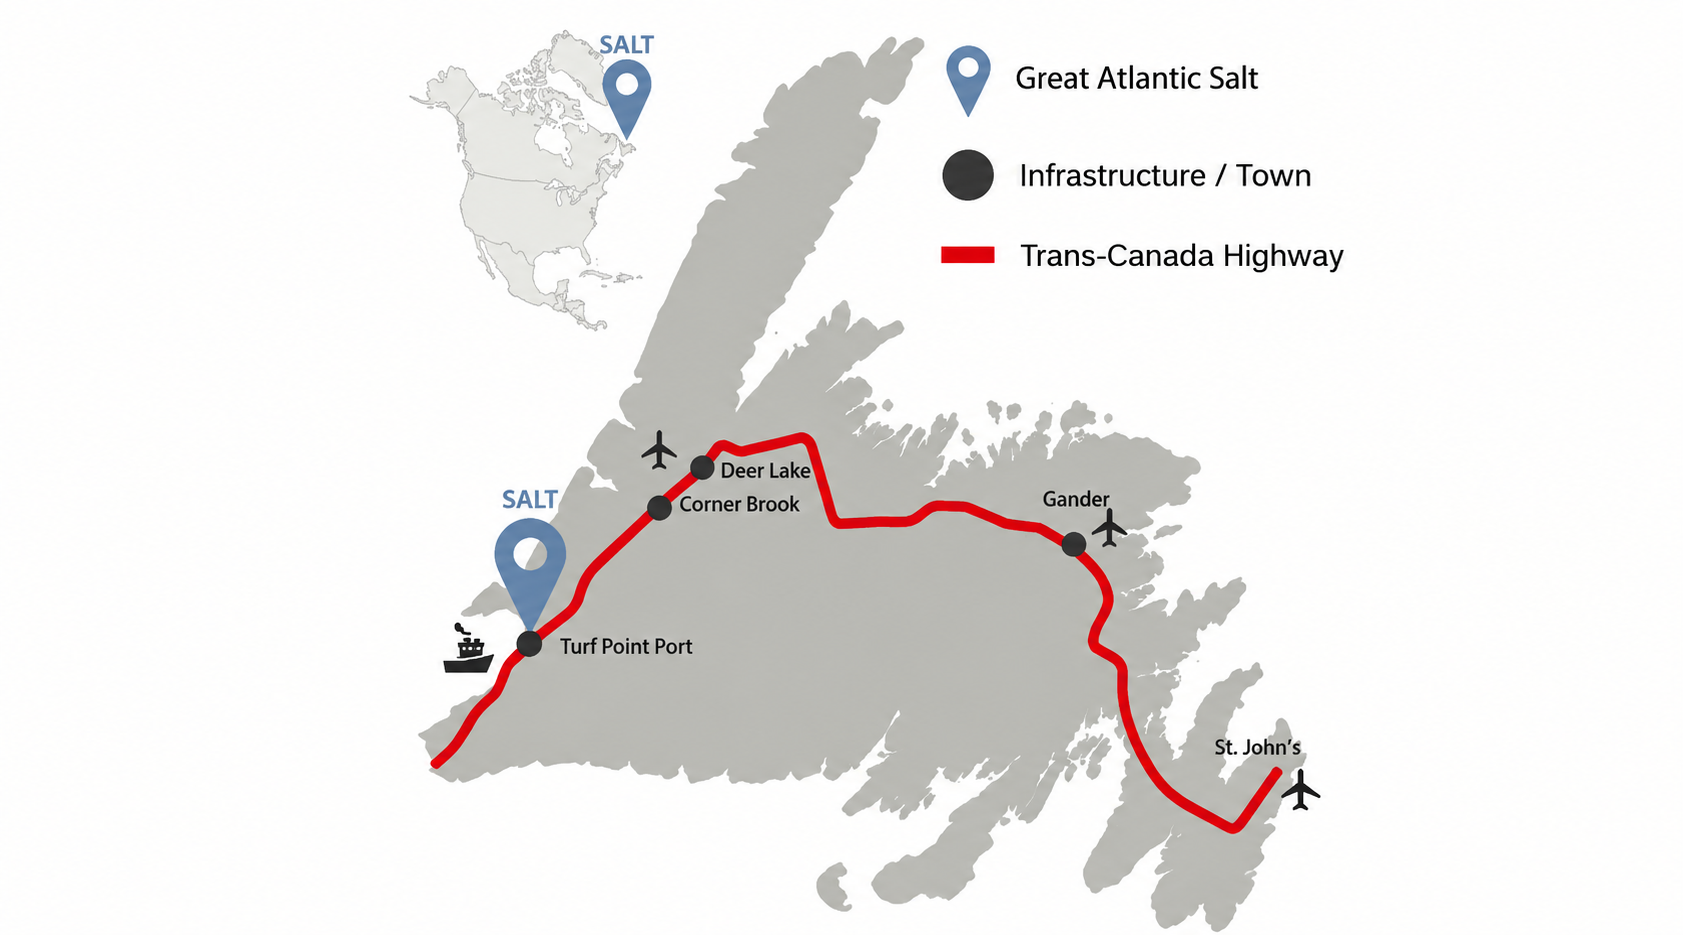
- The C$589 million build still depends on financing, with letters of interest above C$300 million secured and the financing package listed as a milestone priority.
Atlas Salt (TSXV: SALT | OTCQX: SALQF | FSE: 9D00) has completed 3 financings since October 2025, and the company says institutions and strategics took about 50% of the October 2025 offering and about 71% of the June 2026 bought deal. For a developer with no revenue, that is useful validation of the equity. The build needs C$589 million, which the company is seeking from various sources.
What the Raise Data Shows
Atlas Salt estimates how each of its recent financings split by investor type. The October 2025 offering, a C$8.7 million raise at C$0.80, was oversubscribed by C$0.7 million, with about 50% going to institutions and strategics. The June 2026 bought deal, C$15.2 million at C$1.20 and upsized from C$10 million, placed about 71% with that group. The remaining 29% went to other and retail buyers. The June price is 50% above the October 2025 price of C$0.80, a gain in about 8 months, and the stock last traded at C$1.26 on October 23, 2026.
The May 2026 flow-through, C$1.25 million at C$1.30 and shown as 100% institutions and strategics, funded exploration at Black Bay, a non-core nepheline syenite property in southern Labrador, and preserved capital for the salt project. Bench-scale testwork cut iron oxide to 0.01 wt.% in the coarse product and 0.03 wt.% in the fine product, with overall mass recovery of 87.7 wt.%, and maiden drilling of up to 1,500 meters is targeted to start in the fourth quarter of 2026. Black Bay has no mineral resource or reserve.
What One Outside Fund Concluded
The Bedford Park Opportunities Fund says it generally does not buy pre-revenue companies, initially bought shares in February 2026 and placed Atlas Salt in its special situations bucket. A later site visit in Newfoundland and meetings with management and board members reinforced its confidence in the asset and the management team. Atlas Salt's management and board bring experience across mine development, underground construction, finance and salt operations.
The fund holds the stock, and its read of the market is that investors undervalue the company. It says investors appear to value Atlas Salt as a speculative development-stage mining company, and believes the stock is still largely unknown in the broad investment community.
The company's ownership estimate fits that picture. Known institutions and strategics hold about 12% of basic shares, against 56% for retail and other holders, even though they took about 71% of the June raise. Analysts at Raymond James and Ventum Financial cover the stock, so institutions looking at the company have published research to draw on.
Equity Validation Does Not Fund the Build
The October 2025 and June 2026 raises advanced civil engineering work and early planning and development at the project. The C$589 million in pre-production capital in the 2025 updated feasibility study is what the financing package is meant to cover. Net cash is C$23.9 million, including assumed option and warrant exercise proceeds. The study's after-tax net present value at an 8% discount rate is C$920 million, with a 21.3% internal rate of return and a 4.2-year payback, which is what lenders would be asked to fund.
Chief Executive Officer of Atlas Salt, Nolan Peterson, said the financing package is being assembled from various sources:
"Securing the capital from various sources, not necessarily raising through the equity markets, but there'll be potentially some involvement of that."
Atlas Salt has secured financing letters of interest above C$300 million. They include senior debt letters of interest of up to C$225 million, made up of C$150 million from Export Development Canada and C$75 million from a foreign export credit agency, plus a C$79 million Sandvik letter of interest for mining equipment.
What the Fund Says Comes Next
The fund names financing as the most important near-term challenge. It says Atlas Salt is deeply engaged with potential lenders and believes it is a question of when, not if, the company secures the financing. The company's own milestone list shows the same priority: securing the financing package, with Endeavour Financial engaged for project finance.
FAQs (AI-Generated)
Analyst's Notes





Subscribe to Our Channel


Stay Informed


