




Marimaca's US$587M Financing Mix Will Set Shareholder Dilution on Its Chile Copper Build


Marimaca adds ex-Ma'aden CFO Louis Irvine as lender selection and gearing for the US$587M MOD copper build in Chile set how much value reaches shareholders.
- Louis Irvine, former Chief Financial Officer of Ma'aden and Endeavour Mining, joined the Marimaca Copper board as an independent director effective November 1, 2026, and has experience developing and financing copper projects in Peru, including Las Bambas, Quellaveco and Antapaccay.
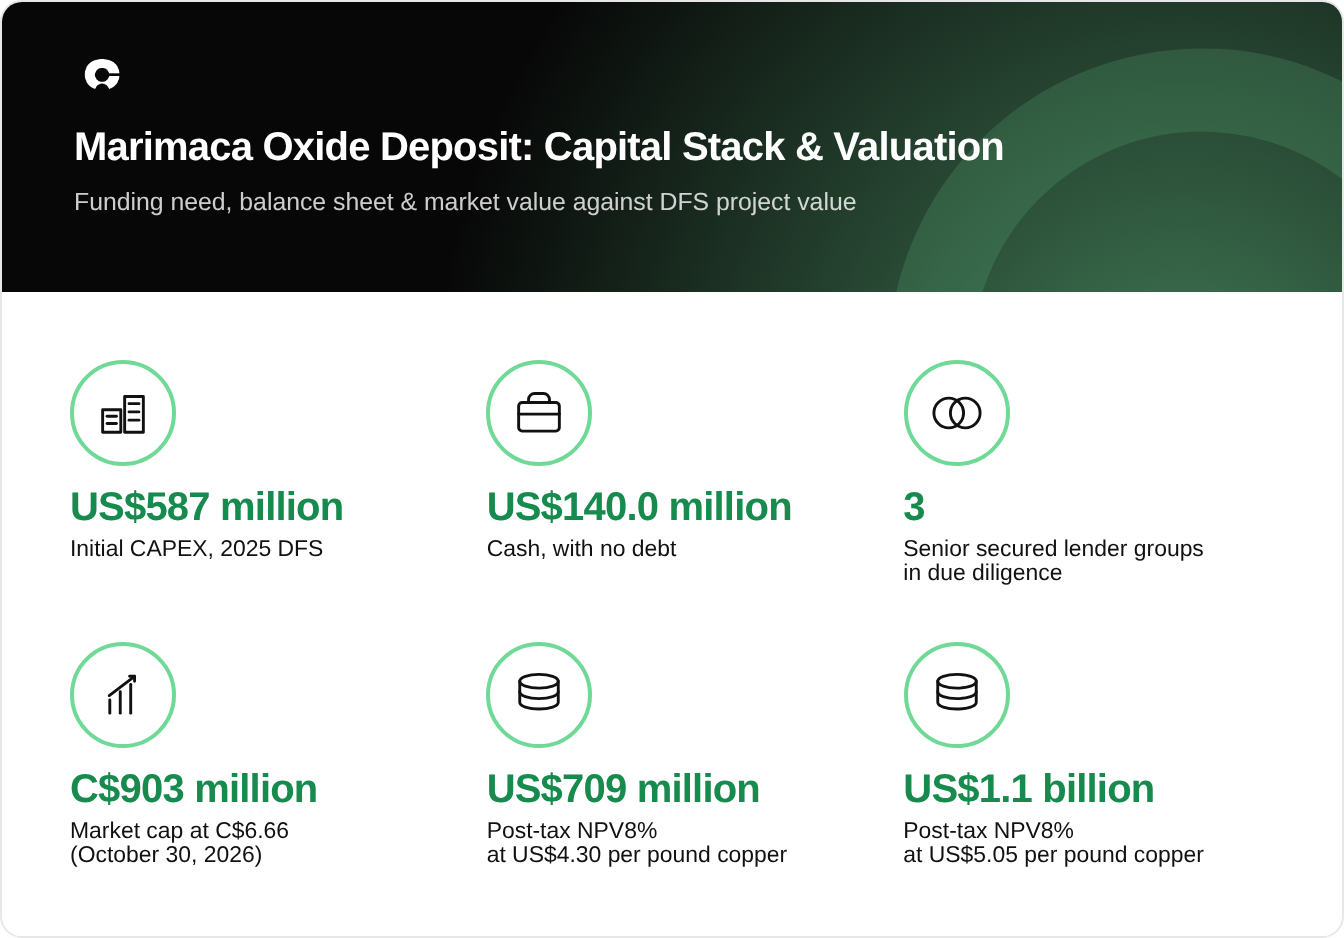
- The Marimaca Oxide Deposit (MOD) requires US$587 million of initial project capital, against US$140.0 million in cash and no debt.
- 3 senior secured lender groups are completing due diligence, with 1 to receive an exclusive mandate and long-form documentation targeted by mid-2027.
- Management favors conservative gearing and no hedging but has not disclosed a debt-to-equity target, so the financing mix is the main unknown for per-share value against a post-tax net present value (NPV8%) of US$709 million.
- Pampa Medina receives no value in the project economics; a 30,000-meter extensional drilling program is defining its footprint, and management is targeting a maiden resource on a small subset of the deposit.
A Project Financier Joins Before the Debt Is Set
Marimaca Copper Corp. (TSX: MARI | ASX: MC2 | OTCQX: MARIF) announced on November 2, 2026, the appointment of Louis Irvine as an Independent Non-Executive Director, effective November 1, 2026. Irvine is a chartered accountant with more than 30 years in mining. He was Chief Financial Officer (CFO) of Ma'aden (Saudi Arabian Mining Company) from 2022 until his retirement in mid-2025, with responsibility for financial strategy and capital allocation, and earlier served as CFO of Endeavour Mining, Executive Head of Strategy and Business Development at Anglo American, and CFO of Copper at Xstrata.
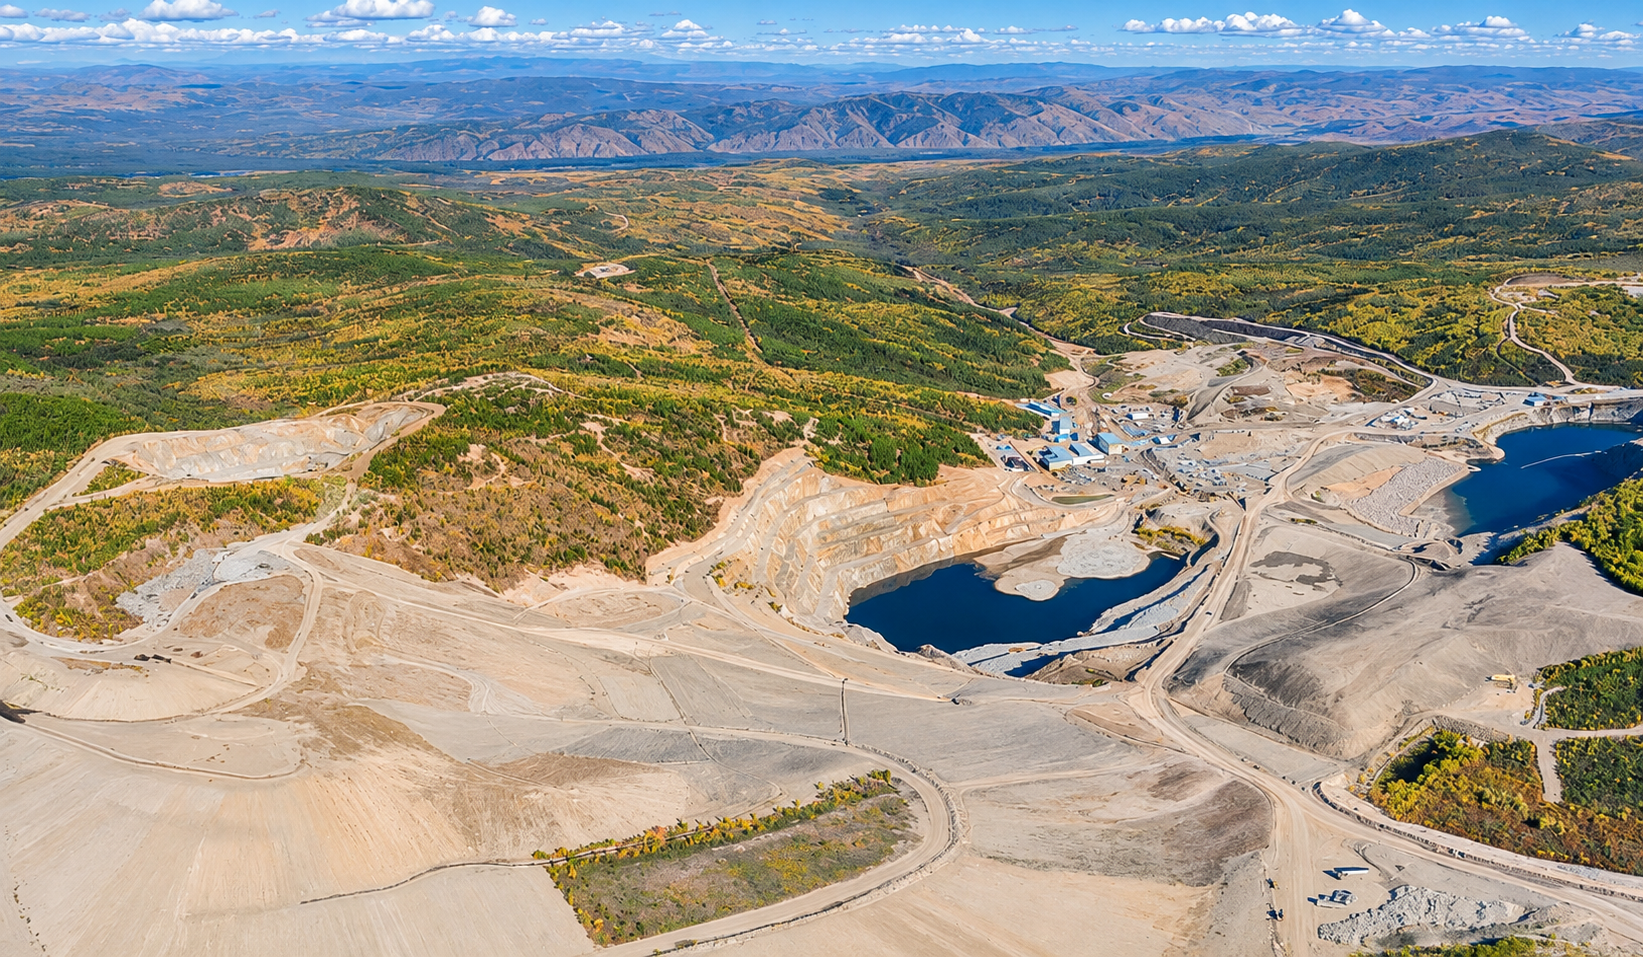
The copper record is the part of that résumé most relevant to Marimaca. Irvine worked on developing and financing Las Bambas, Quellaveco and Antapaccay in Peru. Marimaca is now assembling the funding for US$587 million of initial capital at the Marimaca Oxide Deposit (MOD), a permitted oxide copper project 25 kilometers from the Port of Mejillones in Chile's Antofagasta Region.
The Independent Chair of Marimaca, Giancarlo Bruno Lagomarsino, linked the appointment directly to the financing timetable:
"Louis brings first-hand experience financing mining projects through the development and construction phases, into operations across various commodities and jurisdictions. He joins at a pivotal time for Marimaca, as we prepare the project financing package for the MOD and advance towards a full construction decision."
The Capital Stack Will Set Shareholder Dilution
The 2025 definitive feasibility study (DFS), led by Ausenco, set initial capital at US$587 million for an open pit, heap leach and solvent extraction-electrowinning operation producing 50,000 tonnes per year of copper cathode at steady state over a 13-year mine life. Marimaca holds US$140.0 million in cash and no debt, with 135,546,318 shares outstanding as of October 8, 2026. Strategic holders include Assore with 19.6%, Ithaki Limited with 14.8%, Greenstone with 6.3% and Mitsubishi Corporation with 3.4% as of August 26, 2026, and the company's disclosure lists equity, debt and hybrid instruments as possible funding forms, on terms that may dilute existing shareholders.
The company narrowed a broad search for funding partners to 3 groups, all traditional senior secured lenders, which are completing technical due diligence that includes site visits. The company will then select a single group for exclusivity, followed by legal due diligence and long-form documentation, which management is targeting to complete by mid-2027.
Chief Executive Officer (CEO) Hayden Locke described the structure the company wants from that process:
"Our philosophy as a management team is very much one of not over-leveraging, so we're going to take a relatively conservative approach to our debt-to-equity ratio, and we're trying not to hedge. I think that's one of the things we don't want to do, so we'll manage our risk elsewhere."
Marimaca has disclosed the capital requirement, cash balance, number of lender groups, gearing preference, and timetable, but not a debt-to-equity target. Lower gearing would reduce the project's financial leverage and the associated debt-service obligations, but increase the share of initial capital that has to come from equity, while avoiding hedging keeps project revenue exposed to the copper price, which the DFS sensitivity analysis models. Management wants to avoid entering construction without enough money to complete it, so the size and pricing of any equity component will determine how much dilution existing shareholders absorb. Irvine's experience financing projects through construction is relevant to that decision, though the company and its chosen lender will set the terms.
What the DFS Economics Offer Lenders
At the DFS long-term copper price of US$4.30 per pound, the project returns a post-tax net present value (NPV8%) of US$709 million, a post-tax internal rate of return (IRR) of 31% and a 2.5-year payback. At US$5.05 per pound, the 3-month average COMEX price as of August 25, 2025, the DFS reports an NPV8% of US$1.1 billion and an IRR of 39%. Capital intensity of US$11,700 per tonne of annual copper production ranks among the lowest of North and South American development projects in the company's WoodMac-based benchmarking. The capital estimate is AACE Class 3, with an expected accuracy range of -20% to +25%, budget quotes for 80% of mechanical equipment and a US$53 million contingency equal to 10% of direct, indirect and owner's costs, and long-lead items with delivery times of more than 50 weeks have yet to be secured.
Over the first 5 years of steady state, the DFS projects average annual earnings before interest, taxes, depreciation and amortization (EBITDA) of US$326 million and post-tax unlevered free cash flow (FCF) of US$222 million, with C1 cash costs of US$1.45 per pound and all-in sustaining costs of US$1.97 per pound. At DFS operating costs, the post-tax IRR falls from 31% at US$4.30 per pound to 20% at a copper price 20% lower, and to 15% if operating costs are also 20% higher. Those downside cases are the ones an unhedged, conservatively geared structure would have to absorb.
At C$6.66 per share on October 30, 2026, Marimaca's market capitalization was C$903 million. The NPV8% figures are not a like-for-like comparison: they are in US dollars, they measure project value and not attributable equity value, they come before financing costs and any new shares, and they are based on study assumptions, not operating results. The financing package converts project value into per-share value. A larger senior debt tranche on acceptable terms leaves more of the project NPV8% with existing shares, and a larger equity component spreads it across a bigger register.
Pampa Medina Adds an Exploration Opportunity Outside the Debt Case
Pampa Medina lies about 25 kilometers from the MOD within Marimaca's 14,500-hectare Sierra de Medina land package and receives no value in the DFS. Management plans for Pampa Medina oxides to use MOD infrastructure, and has sized the MOD water pipeline with capacity to deliver 100,000 tonnes of cathode per year. That is infrastructure capacity, not a production target; the DFS production target remains 50,000 tonnes per year.
Marimaca is currently executing a 30,000-meter extensional drilling program to define the footprint of a sediment-hosted copper-silver system. At a 0.5% copper threshold, 88% of drill holes exceed a grade-thickness of 20%-meters, which the company compares with its reference figures of roughly 7%-meters for the Kupferschiefer and 16%-meters for Kamoa-Kakula; those are geological comparisons, not indicators of comparable economics. Management is targeting a maiden resource on a small subset of a drilled area of roughly 3 kilometers by 2 kilometers, and a resource on that scale would not by itself define an economic deposit. Locke placed the sulfide opportunity on a separate timetable from the MOD:
"In terms of the sulfide opportunity, it is a big project and it's going to take a lot of drilling for us to fully understand what the project is and how we should best approach it."
Vice President of Exploration Sergio Rivera now works exclusively on exploration, with a separate team on development. Keeping the sulfide opportunity outside the lender case leaves the debt package resting on DFS economics, while any exploration value accrues to the equity.
What Must Happen Before Construction
Technical due diligence by the 3 lender groups and detailed design and engineering are under way, site early works are planned ahead of the construction decision, and sectorial permits are progressing in line with the master schedule. Still to come are selection of 1 lender for exclusivity, legal due diligence, long-form documentation targeted for mid-2027 and procurement of long-lead equipment. Management would ideally begin site setup for full construction toward the end of 2026, with full construction targeted during 2027.
Irvine joins a board that includes Bruno, a former CEO of Mantos Copper and Vice President Chile for Capstone Copper; Zenon Wozniak, who has more than 40 years leading multi-billion-dollar mining projects and delivered construction of copper mines including Cobre Panama; Nicole Porcile, with leadership experience at Codelco and Antofagasta Minerals; and Kieran Daly, Managing Director of Assore International Holdings. CFO Peter Garner-Winship previously served as Head of Integrated Planning at Anglo American. The variables for shareholders are the final debt-to-equity split, the pricing of any equity, and whether long-lead equipment and construction costs land within the DFS estimate.
The Investment Thesis for Marimaca Copper
- Marimaca appointed a former Chief Financial Officer of Ma'aden and Endeavour Mining to its board as it prepares the financing package for the Marimaca Oxide Deposit.
- Initial project capital of US$587 million compares with US$140.0 million in cash and no debt, so the funding mix will set the dilution outcome for shareholders.
- 3 senior secured lender groups are completing due diligence, with exclusivity and long-form documentation targeted by mid-2027 and full construction targeted during 2027.
- Management favors conservative gearing and no hedging but has not disclosed a debt-to-equity target, which is the main unknown between the definitive feasibility study's post-tax net present value at an 8% discount rate of US$709 million and per-share value.
- Pampa Medina is excluded from the definitive feasibility study and the lender case, so a maiden resource there would add a value input that accrues to equity holders.
Marimaca has a permitted, low-capital-intensity oxide project and a board that now includes copper project finance experience from Peru. The lender mandate terms and the size of any equity raise are the next disclosures that will determine how much of the project value reaches each share.
TL;DR
Marimaca added former Ma'aden CFO Louis Irvine to its board as 3 lender groups complete due diligence on the US$587 million MOD. Management favors low gearing and no hedging, but the undisclosed debt-to-equity split will decide how much dilution shareholders take on.
FAQs (AI-Generated)
Analyst's Notes





Subscribe to Our Channel


Stay Informed


