Integra Sets 2027 for the Study That Reprices Nevada North


Integra's third gold asset holds 1,324,000 ounces, but its published economics are based on a 2023 study priced at US$1,700 per ounce.
Project Overview
Nevada North is the third and least advanced of the three assets Integra Resources (TSXV: ITR | NYSE American: ITRG) holds in the Great Basin, behind the producing Florida Canyon mine and the DeLamar development project. It combines two deposits under one project name, and both remain at the preliminary economic assessment (PEA) stage.
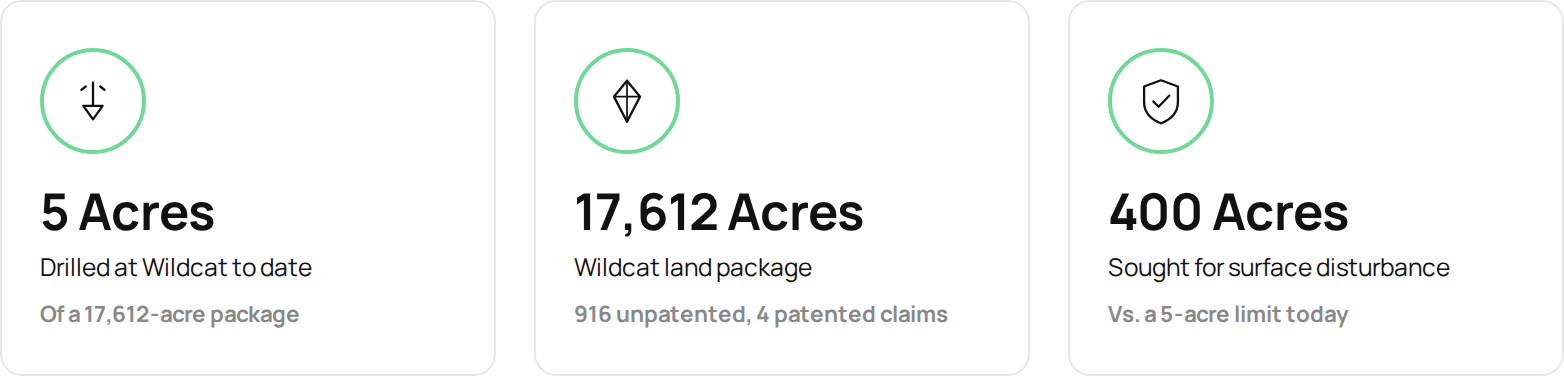
Wildcat is a gold-silver deposit in the Farrell Mining District, about 56 kilometers (km) from the town of Lovelock, on a 17,612-acre land package made up of 916 unpatented and 4 patented claims. Mountain View is a comparable deposit in the Deephole Mining District, about 24 km from the town of Gerlach, on a 5,476-acre package of 284 unpatented claims. Wildcat lies about 30 miles from the operating Florida Canyon mine.
Between them, the deposits hold an indicated resource of 88.6 million metric tons at 0.46 grams per metric ton (g/t) gold and 3.45 g/t silver, for 1,324,000 ounces of gold and 9.8 million ounces of silver, plus a further 26.6 million metric tons at 0.32 g/t gold and 2.60 g/t silver in the inferred category. The ounce count is substantial for a project the market has barely repriced.
1. The Economics on Offer Date From 2023
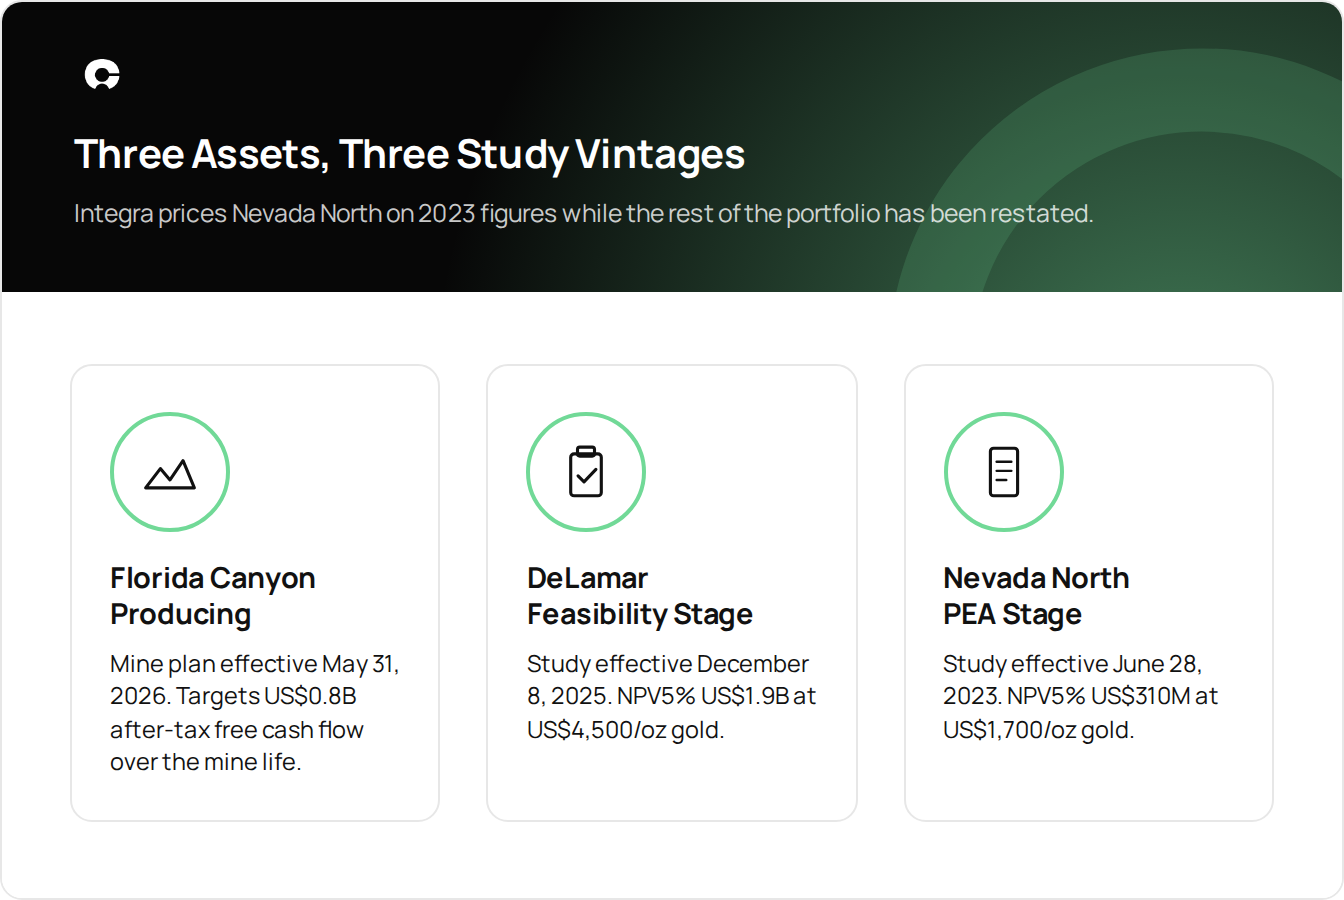
Every economic figure that Integra publishes for Nevada North comes from a study with an effective date of June 28, 2023.
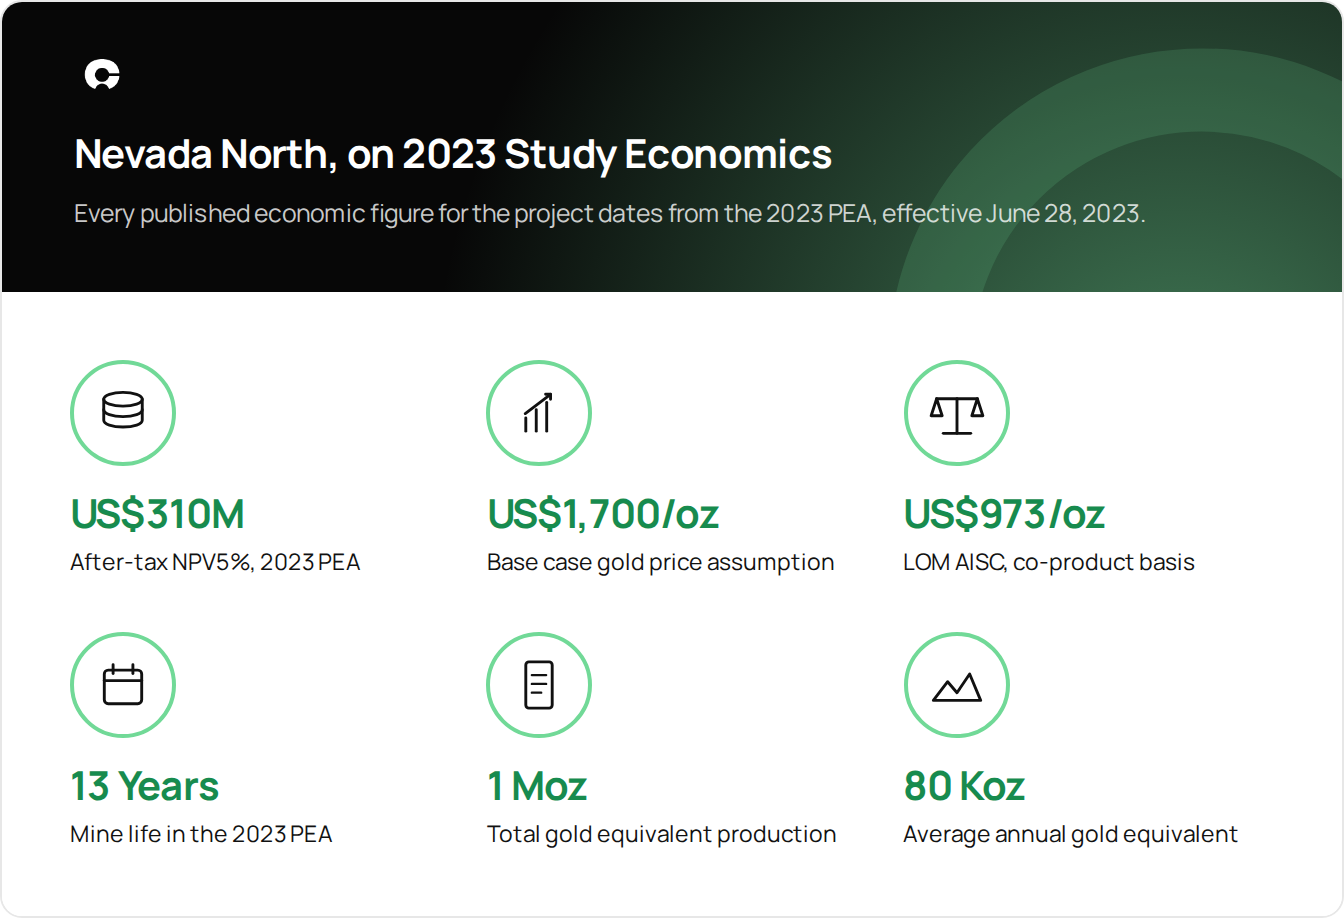
The PEA covering Wildcat and Mountain View outlines a 13-year mine life mining 100 million metric tons of ore, producing 1 million ounces of gold equivalent in total and averaging about 80,000 ounces of gold equivalent a year, at a life-of-mine all-in sustaining cost of US$973 per ounce on a co-product basis, with a 3-year after-tax payback. An investor pricing the third asset works from those figures today. Florida Canyon's updated mine plan has an effective date of May 31, 2026, and DeLamar's feasibility study has an effective date of December 8, 2025.
2. The Gold Price Underneath Them
The project's headline return is calculated at US$1,700 per ounce for gold.
Nevada North shows an after-tax net present value at a 5% discount rate (NPV5%) of US$310 million and an internal rate of return (IRR) of 37%, based on base-case prices of US$1,700 per ounce for gold and US$21.50 per ounce for silver. A second and separate assumption prices the resource feeding those economics: the 0.15 g/t gold cut-off grade applied at both Wildcat and Mountain View was calculated using a gold price of US$1,800 per ounce.
Integra presents DeLamar on an entirely different basis. That project's feasibility study shows an after-tax NPV5% of US$1.9 billion and an IRR of 97% using current metal prices of US$4,500 per ounce for gold and US$65 per ounce for silver. The same portfolio, therefore, contains one asset priced at today's gold market and one priced at 2023's.
3. What the Resource Is, and What It Is Not
Nevada North's ounces sit in resource categories only, with no mineral reserve behind them.
The measured category is empty; the entire 1,324,000 ounces of gold falls into the indicated category; and the project appears in Integra's reserve and resource tables under resources alone, with no proven or probable line. The study behind those ounces states its own limits: it is preliminary; it includes inferred mineral resources deemed too geologically speculative to warrant economic consideration; and there is no certainty that the study will be realized. Micon International Limited reviewed and validated the estimate for both deposits.
President, Chief Executive Officer, and Director of Integra Resources, George Salamis, applies the same standard to the foundation of any mine plan:
"We hear this sentence issued often by mining companies, which is resource and reserves are the foundation that the house is built on, right? And you need to have confidence in that foundation."
At Nevada North, that foundation has not been rebuilt since 2023, and no mineral reserve has been declared on it.
4. Wildcat Has Been Drilled on About 5 Acres
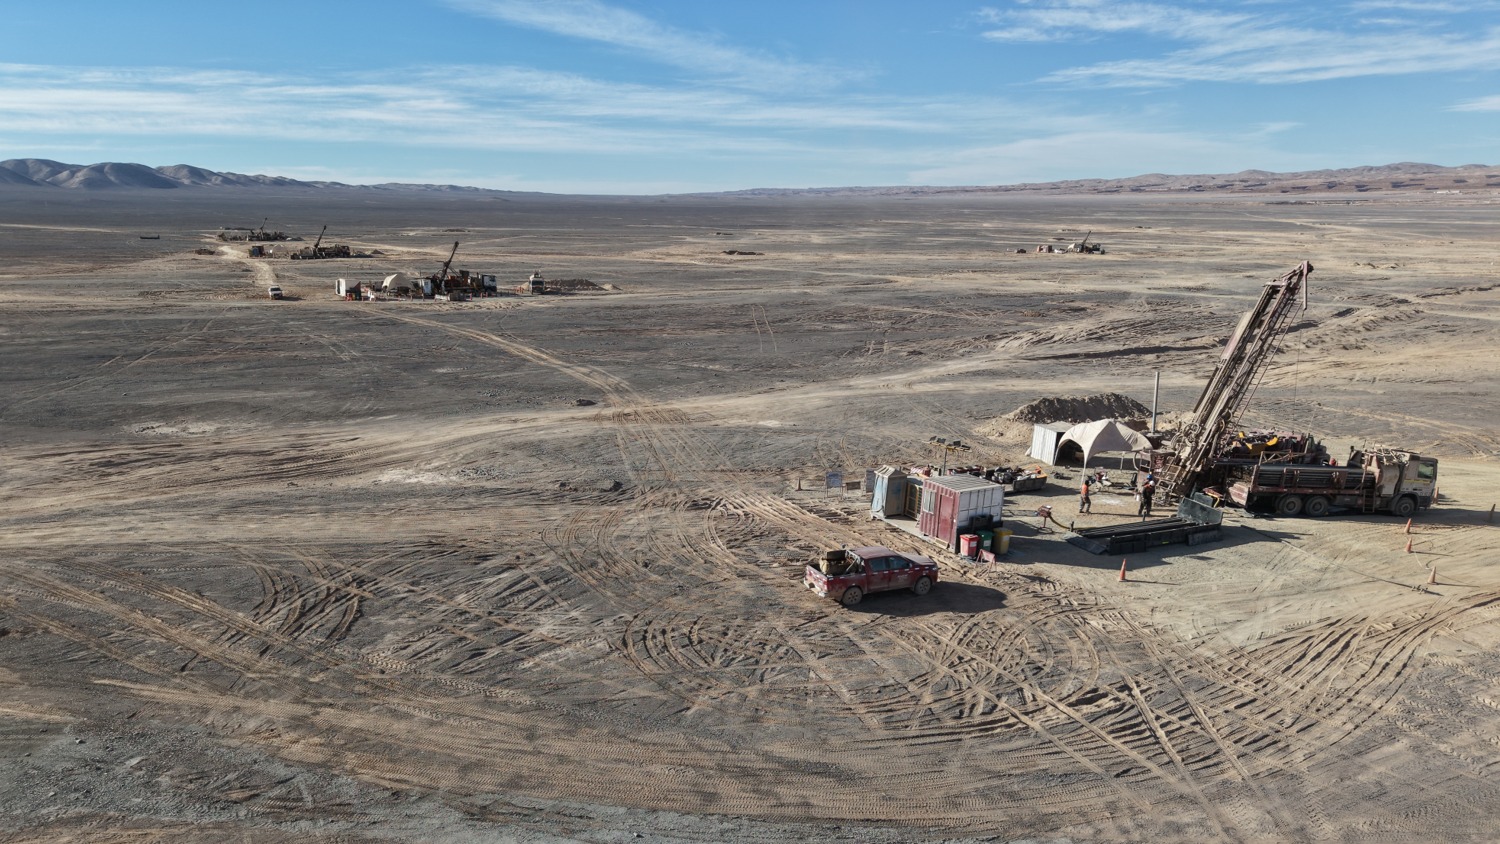
Wildcat's resource rests on drilling across roughly 5 acres within a land package totaling over 17,000 acres.
The mineralized footprint at Wildcat was expanded in 2022 to about 3.0 km by 2.0 km, from 1.5 km by 1.5 km previously. Inside the 2023 study, the estimate holds 746,297 ounces of gold in the measured and indicated categories and 209,662 ounces inferred, a pit-constrained gold figure narrower than the 829,000 ounces of gold equivalent quoted for the Wildcat deposit as a whole.
Drilling completed in 2024 confirmed continuity of mineralization and returned 0.25 g/t gold over 213.8 meters (m) and 0.27 g/t oxide gold over 147.5 m. The geological model Integra is testing at the Breccia Pipe target survived that drilling intact.
5. The Permit That Decides How Much Can Be Drilled
A 5-acre surface disturbance limit has bounded the drilling, and the exploration plan Integra submitted seeks 400 acres.
Under the notice of operation currently governing Wildcat, Integra may disturb up to 5 acres of surface area. The exploration plan of operations submitted to the Bureau of Land Management would allow 400 acres of surface disturbance instead. The permit and the drilled area are the same constraint, seen twice: about 5 acres have been drilled because that is what the current authorization allows.
Integra's stated 2026 work at Nevada North is de-risking activity and exploration drilling in support of an updated technical report, alongside pre-permitting. The 2023 study is replaced when that work produces the updated report.
6. Surface Targets Lie Outside the 2023 Pit
The targets Integra names at Wildcat fall outside the pit on which the 2023 study was built.
Mineralized targets were found at the surface beyond the current pit outline, and surface samples collected in 2022 returned grades up to 30 g/t oxide gold. Four are named outside the pit outline: Crossroads, Breccia Pipe, North, and Rhyolite Ridge. Mineralized rock continues beneath the volcanic cover next to the 2023 pit outline, which is where the untested ground begins.
The 2022 results are surface sample grades, not drill intercepts, and the mine life extension Integra shows in years 7, 8, 9, and 13 is tied to near-term exploration, not a resource. The 2023 study could not price either of them. The next study can.
7. The Restatement Is a 2027 Item
Integra places the updated Nevada North technical report in 2027, after the 2026 drill program that feeds it.
Nevada North's share of the 50,000-m portfolio program is 5,500 m, aimed at resource conversion alongside hydrogeological, metallurgical and geotechnical work, with the updated technical report as its stated output. The 2027 milestones Integra lists place the Nevada North technical report alongside Florida Canyon production growth to 80,000 to 85,000 ounces, the DeLamar permitting decision in the second half of 2027, and project financing at DeLamar drawn on accumulated cash flow.
Integra places Nevada North in the studies and permitting stage, with an updated technical report and permitting activities still ahead, on internal estimates dated February 2026 and subject to change. Throughout the drilling year, the 2023 figures remain the published economics for the asset.
8. What Pays for It, and in What Order
Nevada North is funded from Florida Canyon's cash flow behind DeLamar, so two other assets have to perform first.
Florida Canyon generates cash flow to support the advancement of both development projects, and its updated mine plan targets US$0.8 billion in after-tax free cash flow over the mine life, averaging US$90 million per year in the plan's base case. The company's long-term objective is a multi-asset platform producing 250,000 to 300,000 ounces of gold equivalent a year.
Salamis puts Florida Canyon and Nevada North in production together, not one behind the other:
"I do believe that those two assets will actually be in production in parallel at some stage."
The order he describes for the money is strictly sequential, and Nevada North is at the end of it:
"And again, once DeLamar and Florida Canyon are running in parallel, that will then clearly pay for Nevada North ultimately in the development plan."
The third asset, therefore, waits behind a producing mine and a project still working toward its construction decision, and its study has waited with it.
Key Takeaway for Investors
- Three years of gold price movement separate the study Nevada North is presented on from the prices at which the rest of Integra's portfolio is presented, and only an updated technical report closes that gap.
- A 5-acre drilling footprint on a land package of over 17,000 acres means the resource describes only a small tested area, not the deposit's full extent, and the exploration plan of operations seeking 400 acres would broaden the ground a drill program can reach.
- The absence of a mineral reserve at Nevada North places it a full technical stage behind DeLamar and two behind Florida Canyon, so the ounces are counted but not yet economically demonstrated.
- The 2027 timing of the updated technical report means the third asset stays priced on preliminary economic assessment figures throughout the 2026 drilling year.
Bottom Line
Nevada North is the part of Integra's three-asset case that has not yet been re-underwritten. The ounces are counted and independently validated; the ground around them is largely untested; and the economics an investor can point to were modeled for a gold price the market has long since left well behind. Three things move it: an exploration plan of operations that widens the drillable area from 5 acres to 400 acres, a portfolio drill program running through 2026, and an updated technical report that Integra has placed in 2027. Until that report lands, the sensible way to value the third asset is as a large, largely untested land position with a known resource on it, and to treat the 2023 returns as the floor of the argument rather than its conclusion.
Analyst's Notes





Subscribe to Our Channel

Stay Informed