




Marimaca Enters Final Due Diligence on a 2027 Copper Build With 3 Lenders


Marimaca Copper has narrowed debt financing for its Chilean project to 3 lenders in technical due diligence, with leverage and hedging already decided.
- Marimaca Copper has narrowed the debt financing for the Marimaca Oxide Deposit (MOD) to 3 lender groups.
- Technical due diligence is the remaining step, and lending partners visited the site in September 2026.
- All 3 remaining parties are traditional senior secured lenders.
- Management is targeting a relatively conservative debt-to-equity ratio and is trying to avoid hedging.
- The financing paperwork extends into the middle of 2027, with full construction during that year.
What Has Happened
Marimaca Copper (TSX: MARI | ASX: MC2) has narrowed the field of potential debt providers for its Chilean copper project to 3 groups, each now working through technical due diligence. Those lenders were on site during the week of September 8, 2026, inspecting the Marimaca Oxide Deposit (MOD) ahead of the decision that will determine how the mine is paid for.
Management has conducted a broad search for funding partners, evaluating alignment with the company's plans and the cost of capital they offer, and has reached the point where one of the 3 will be selected for exclusive negotiations. What those lenders are examining is a permitted open-pit heap leach project with a completed feasibility study, not a concept.
The Shortlist & What Is Left to Clear
Every remaining step before the financing package closes is procedural, and each one has a place in a stated sequence.
Chief Executive Officer of Marimaca Copper, Hayden Locke, put a number on how far the search has narrowed:
"We have run a fairly comprehensive and broad, far-reaching process to go out and identify funding partners that are both aligned with our sort of future goals, but also providing us a really competitive cost of capital, and we've whittled that down to three groups."
The lenders are testing a design that is not yet closed out: detailed engineering is advancing, with an execution strategy still to be defined; preferred contracting partners are being identified; and the site early works sit ahead of a final investment decision, not after one.
Locke cuts the remaining work to one item:
"The technical due diligence is the final piece of the puzzle that we need to take care of."
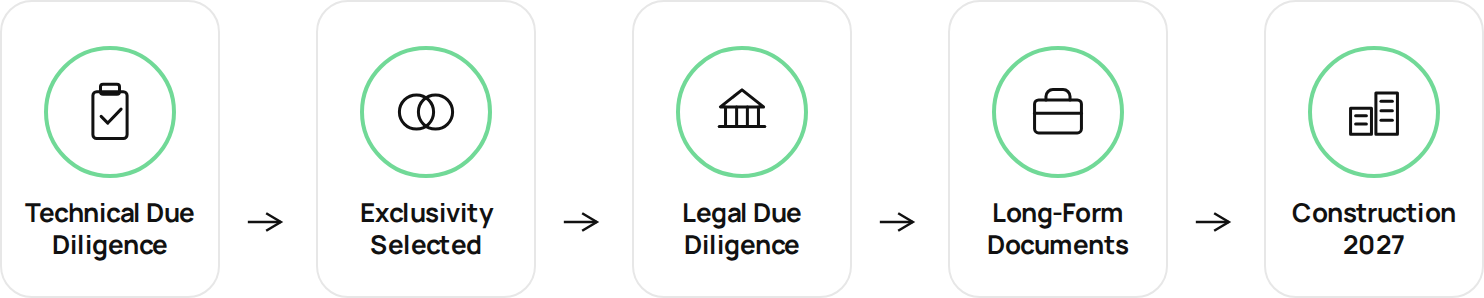
Once a group is selected for exclusivity, legal due diligence follows, and management says the company has been through that process several times already, including its public listing and capital raisings. Long-form documentation comes after that and extends into the middle of 2027. Full construction is targeted for 2027, and management would prefer to set up the site ahead of that, toward the end of 2026, though an earlier start is an aspiration. Management describes itself as committed to taking the MOD into a construction decision and into production. None of those steps turns on the copper price.
What Management Has Ruled Out
The shape of the package has been narrowed before a lender has been chosen, which limits what the final terms can look like, regardless of which group wins exclusivity. Both the leverage and hedging questions have already been answered.
Locke sets the ceiling on leverage and rules out price hedging in one answer:
"So we're going to take a relatively conservative approach to our debt-to-equity ratio. And we're trying not to hedge."
An unhedged borrower keeps its revenue exposed to the copper price in both directions instead of locking part of it into a forward sale, and management says it will manage that risk elsewhere in the business. The lender type is settled as well: all 3 remaining parties are traditional senior secured lenders, the kind that rank first for repayment, and management does not expect anything off-market or unusual in the structure, on the grounds that the company does not need it. The company had cash of US$140.0 million as at June 30, 2026, and no debt.
Management's stated concern as construction begins is having sufficient funds to complete the build. Post-tax average annual free cash flow is US$222 million over the first 5 years of steady state and US$160 million over the life of the mine, unlevered and across operating years 1 to 23, at a long-term copper price of US$4.30 per pound. Management also intends to keep drilling through that period and to continue showing shareholders the upside.
The Project the Lenders Are Examining
The asset being underwritten is specified down to its reserve, its production rate, and its capital cost. The MOD carries proven and probable reserves of 179 million metric tons (t) at 0.42% copper, for 748,000 t of contained copper, over a 13-year mine life. The steady-state production target is 50,000 t of copper cathode a year, with the first 10 years averaging 48,000 t of Grade A cathode, including a 1-year ramp-up period. It is a simple open pit with a life-of-mine strip ratio of 0.8 to 1, including pre-stripped material.
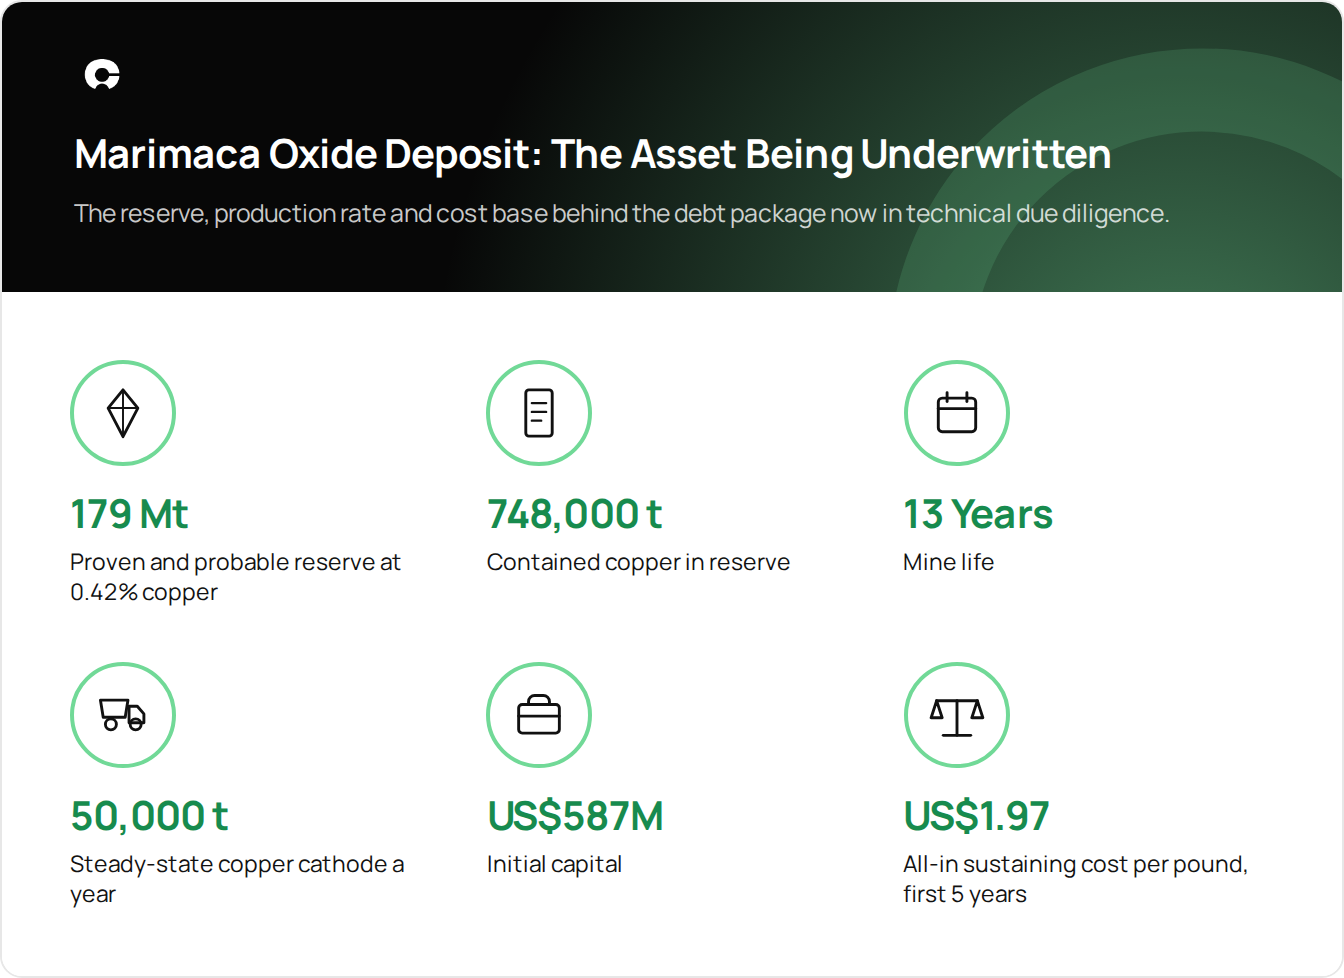
Initial capital is US$587 million, with an initial capital intensity of US$11,700 per t of annual copper production capacity, and a life-of-mine capital of US$1,198 million. At a long-term copper price of US$4.30 per pound, the project yields a net present value of US$709 million at an 8% discount rate, an internal rate of return of 31%, and a payback period of 2.5 years. At a 3-month average price of US$5.05 per pound for copper as of August 25, 2025, those same figures become US$1.1 billion, 39% and a 2.2-year payback.
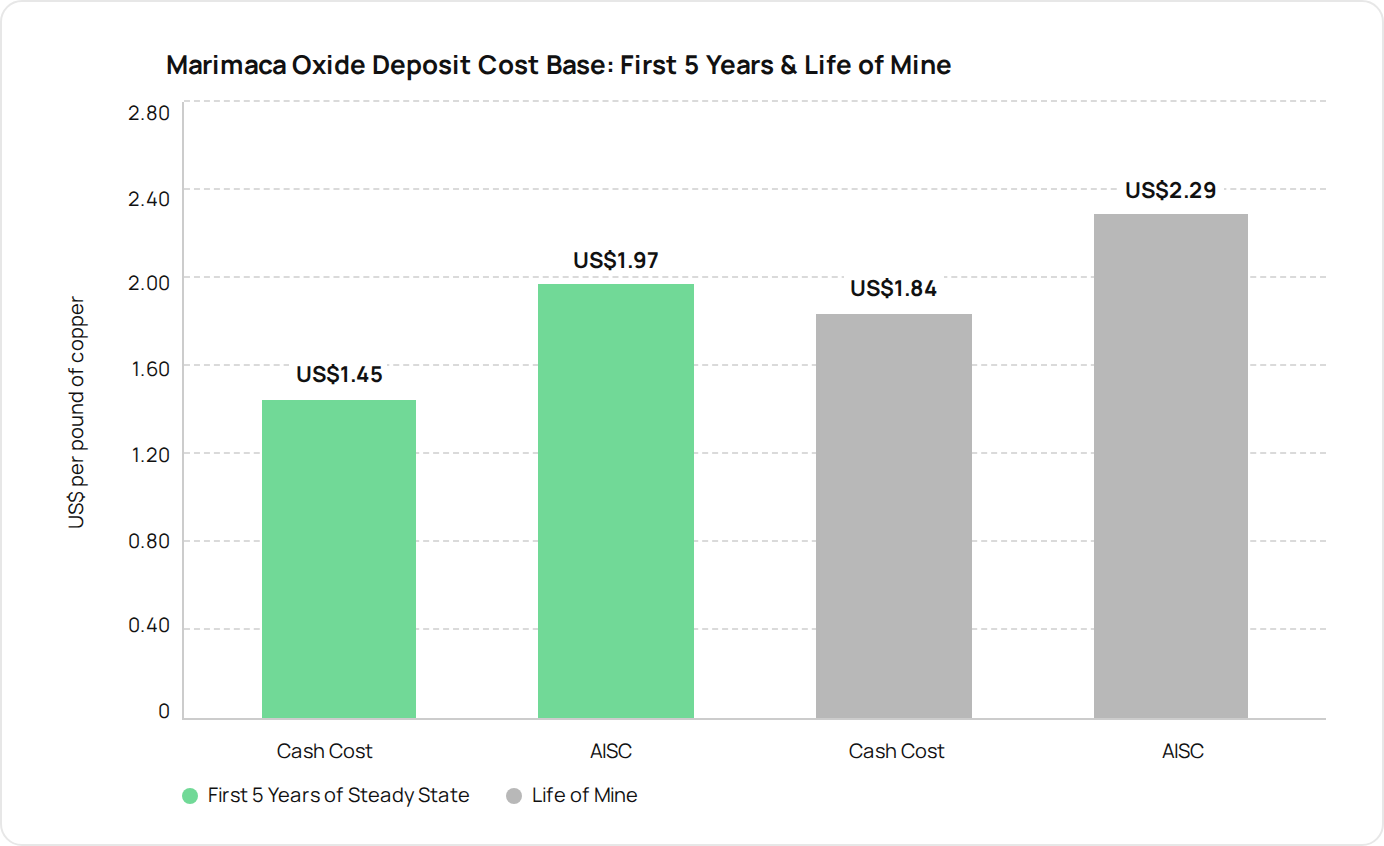
Operating costs provide lenders with their margin of cover. Cash costs are US$1.45 per pound over the first 5 years of steady state and US$1.84 per pound over the life of the mine, at a long-term copper price of US$4.30 per pound, which the company places in the 2nd quartile of the cost curve. All-in sustaining costs are US$1.97 and US$2.29 per pound on those same two bases. Average annual earnings before interest, taxes, depreciation, and amortization are US$326 million over the first 5 years and US$241 million over the life of the mine, on a 58% margin. Environmental approval for the deposit came in the fourth quarter of 2025.
Broader Context
The build being financed has been sized with a second asset in mind. Pampa Medina, approximately 28 kilometers (km) east of the MOD, returned 216 meters (m) at 0.96% copper from 466m on 150m centers, including 62m at 2.20% copper, as part of a 30,000m program for 2026. That drilling should finish at the end of October, ahead of an initial resource covering a small subset of the deposit, and the company has split its teams so that its Vice President of Exploration, Sergio Rivera, runs exploration while a separate group handles development. Management describes the sulfide opportunity as a major project that will require extensive drilling to understand, not a short-term decision.
Marimaca Copper had a market capitalization of C$1,137 million at a share price of C$8.41 as of August 31, 2026, on 135,156,927 shares outstanding as of July 27, 2026, with a further 4,607,808 options, warrants, and restricted share units. Its register as of August 26, 2026, listed Assore at 19.6%, Ithaki Limited at 14.9%, Greenstone at 6.4%, and Mitsubishi Corp. at 3.4%.
For a copper developer building on Chile's coastal belt, the binding constraints are utilities rather than geology. Management reviewed what would limit adding a Pampa Medina operation onto the MOD infrastructure, narrowed the answer to power consumption, power availability, and water availability, and oversized the water pipeline accordingly. The company describes market conditions as supportive of a competitive financing process, and management points to the copper price and broader tailwinds as reasons to move now.
What to Watch Next
The next observable marker is the name of the group that wins exclusivity, which comes at the close of the due diligence phase. Everything after that is documentary, and the calendar rather than the copper market sets its pace.
Two items on the build side remain open. The long-lead equipment items with delivery of more than 50 weeks have still to be secured, and the secondary construction permits are in line with the master schedule. The initial resource at Pampa Medina is the other item on the timetable.
A reader watching this company through to a construction decision already knows the terms on which it will be struck. Leverage, hedging, and lender type were settled before the winner was picked, so the news in the exclusivity announcement will be the name, not the structure.
FAQs (AI-Generated)
Analyst's Notes





Subscribe to Our Channel


Stay Informed


